P.S. Free & New AFP-Exam-1 dumps are available on Google Drive shared by RealValidExam: https://drive.google.com/open?id=1EeIXsZ0kHATZ_GRs6lTYEXeuIqqoi90_
Our professional experts are very excellent on the compiling the content of the AFP-Exam-1 exam questions and design the displays. Moreover, they impart you information in the format of the AFP-Exam-1 questions and answers that is actually the format of your real certification test. Hence not only you get the required knowledge, but also you find the opportunity to practice real exam scenario. We have three versions of the AFP-Exam-1 Training Materials: the PDF, Software and APP online. And the Software version can simulate the real exam.
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Technical Competencies | 84% | - Risk Management and Insurance - Retirement Planning - Asset and Liability Management - Estate Planning - Investment Planning - Tax Planning |
You must make a decision as soon as possible! I don't know where you heard about AFP-Exam-1 actual exam, but you must know that there are many users of our AFP-Exam-1 study materials. Some of these users have already purchased a lot of information. They completed their goals with our AFP-Exam-1 learning braindumps. Now they have a better life. As you know the company will prefer to employ the staffs with the AFP-Exam-1 certification.
NEW QUESTION # 20
A client's portfolio target is 50% equities and 50% fixed income. After a strong equity market, the portfolio is now 68% equities. The client's circumstances and objectives have not changed. What should the planner recommend?
Answer: B
Explanation:
Portfolio drift changes risk. If the approved allocation is 50% equities and the current allocation is 68%, the portfolio now has materially more equity exposure than the client agreed to hold. Rebalancing restores the risk profile and imposes discipline after market movement. Option B is performance chasing; it uses recent returns as a reason to increase concentration without revisiting suitability. Option C overcorrects and may sacrifice the return required to meet long-term goals. Option D contradicts the monitoring function of an investment plan. A proper rebalancing recommendation should consider tax consequences, transaction costs, registered versus non-registered accounts, thresholds, and whether contributions or withdrawals can be directed to underweight asset classes. The rationale is not that equities are expected to fall. The rationale is that the client's portfolio should continue to reflect the documented objectives, constraints, and risk profile.
References/topics: rebalancing, portfolio monitoring, strategic allocation, risk discipline. Rebalancing thresholds should be stated before market movement occurs.
NEW QUESTION # 21
What information is least important for Harry as a financial planner in his assessment for insurance coverage for his client with respect to estate planning purposes?
Answer: D
Explanation:
Estate insurance analysis focuses on amounts that create liquidity needs at death. Age affects underwriting, premium cost, and life expectancy assumptions. Income may indicate lifestyle replacement needs, support obligations, or survivor dependency. The fair market value of a non-principal residence is directly relevant because accrued capital gains may create a tax liability on deemed disposition at death. Work location, by contrast, has little bearing on estate liquidity unless the scenario adds an occupational risk or employer benefit issue, which it does not. The planner should gather asset values, ownership form, liabilities, beneficiary designations, tax exposure, family obligations, and existing insurance before recommending coverage. In this question, option B is least important because it does not help calculate probate exposure, final tax, debt repayment, or survivor capital requirements. Study Guide focus: estate liquidity, deemed disposition, life insurance needs analysis, taxable assets, and client data collection. The file should therefore emphasize estate value, tax exposure, liquidity, and beneficiary obligations rather than workplace geography.
NEW QUESTION # 22
Todd, a financial planner, is meeting with Vanessa, a new client, to review her investment goals and objectives. During the meeting, Vanessa states that she believes the markets are very efficient and should reflect all available information in the price of securities. She is looking for an investment option that will reflect a similar level of risk and return characteristics as the Canadian market. What investment option should Todd recommend with Vanessa that would reflect her opinions?
Answer: C
Explanation:
Vanessa's belief points directly to passive market exposure. If she accepts that markets are efficient and wants risk and return characteristics similar to the Canadian market, an exchange-traded fund tracking a broad Canadian equity index is the most consistent recommendation. An ETF can provide diversified Canadian market exposure, transparent holdings, intraday liquidity, and typically lower management cost than many actively managed strategies. A Canadian value mutual fund is an active or style-biased mandate and may depart materially from total market characteristics. A neutral balanced fund includes fixed income and therefore will not mirror the Canadian equity market. A hedge fund may use leverage, short positions, derivatives, or absolute-return strategies, which do not match her stated view. Todd must still confirm KYC information and suitability, but among the options, the Canadian ETF best operationalizes an efficient-market philosophy. Study Guide focus: passive investing, ETFs, diversification, efficient markets, and investment objective alignment. The recommendation should still be framed inside Vanessa's KYC profile rather than presented as a universal market rule.
NEW QUESTION # 23
Jenny and Herman are looking for tax strategies that will help them better manage their marginal annual tax rates. Jenny is currently the primary income earner in the household. She has a large non-registered portfolio that holds only plain vanilla S & P 500 index funds. Jenny and Herman have a 14-year-old daughter, and they would also like to know what income-splitting opportunities exist. They've presented several ideas to their tax planner, Isaac, for review. Which of the following will likely result in tax attribution to Jenny?
Answer: B
Explanation:
Jenny's gift to her minor daughter is the transaction most likely to trigger attribution back to Jenny. When a high-income parent transfers income-producing property to a minor child, income such as interest and dividends generally attributes back to the parent. The rule prevents simple income splitting by gift. A spousal RRSP converted to a RRIF can avoid attribution on required minimum RRIF withdrawals, subject to detailed timing rules. A sale of securities to Herman at fair market value can avoid attribution if proper consideration is paid and the transaction is documented. A prescribed-rate loan to Herman can also avoid attribution if interest is charged at the prescribed rate and paid by the required deadline. The key AFP issue is distinguishing prohibited income splitting from properly structured transfers or loans. The minor-child gift in option A is the clearly attributive arrangement. Study Guide focus: attribution rules, minor children, spousal transfers, prescribed-rate loans, and family tax planning.
NEW QUESTION # 24
Consider the following information for a client's portfolio: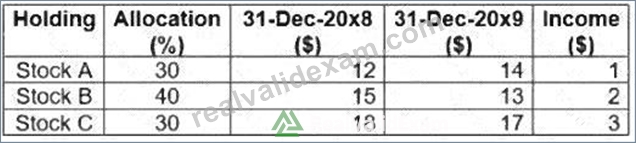
What is the annual rate of return for this portfolio?
Answer: C
Explanation:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
NEW QUESTION # 25
......
Cease to struggle and you cease to live. Only by continuous learning can we not be surpassed by others. Many people do not like to study and think that learning is a very vexing thing. This kind of cognition makes their careers stagnate. AFP-Exam-1 test question will change your perception. AFP-Exam-1 learning dumps aim to help students learn easily and effectively that has been developed over many years by many industry experts. For the online version, unlike other materials that limit one person online, AFP-Exam-1 learning dumps does not limit the number of concurrent users and the number of online users. You can practice anytime, anywhere, practice repeatedly, practice with others, and even purchase together with othersAFP-Exam-1 learning dumps make every effort to help you save money and effort, so that you can pass the exam with the least cost.
Latest AFP-Exam-1 Test Labs: https://www.realvalidexam.com/AFP-Exam-1-real-exam-dumps.html
DOWNLOAD the newest RealValidExam AFP-Exam-1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1EeIXsZ0kHATZ_GRs6lTYEXeuIqqoi90_