BONUS!!! Download part of Lead1Pass PF1 dumps for free: https://drive.google.com/open?id=1gu0NGjaVANHhkgSoIvxu-IodTgcuh3Wh
Our PF1 exam questions not only includes the examination process, but more importantly, the specific content of the exam. In previous years' examinations, the hit rate of PF1 learning quiz was far ahead in the industry. We know that if you really want to pass the exam, our study materials will definitely help you by improving your hit rate as a development priority. After using PF1 training prep, you will be more calm and it is inevitable that you will get a good result.
| Section | Objectives |
|---|---|
| Topic 1: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Topic 2: New Employee Information | - Employee setup and documentation
|
| Topic 3: Workers’ Compensation | - Workers compensation administration
|
| Topic 4: Federal Remittances | - Government remittance obligations
|
| Topic 5: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 6: Non-Regular Payments | - Special payroll payments
|
| Topic 7: Payroll Accounting | - Payroll accounting practices
|
| Topic 8: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 9: Provincial Remittances | - Provincial payroll requirements
|
| Topic 10: Termination of Employment | - Termination processing
|
| Topic 11: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 12: Commission Payments | - Commission payroll processing
|
| Topic 13: Record of Employment | - ROE processing
|
The Payroll Fundamentals 1Exam (PF1) practice questions are designed by experienced and qualified PF1 exam trainers. They have the expertise, knowledge, and experience to design and maintain the top standard of National Payroll Institute PF1 exam dumps. So rest assured that with the Payroll Fundamentals 1Exam (PF1) exam real questions you can not only ace your Payroll Fundamentals 1Exam (PF1) exam dumps preparation but also get deep insight knowledge about Payroll Fundamentals 1Exam (PF1) exam topics. So download Payroll Fundamentals 1Exam (PF1) exam questions now and start this journey.
NEW QUESTION # 48
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
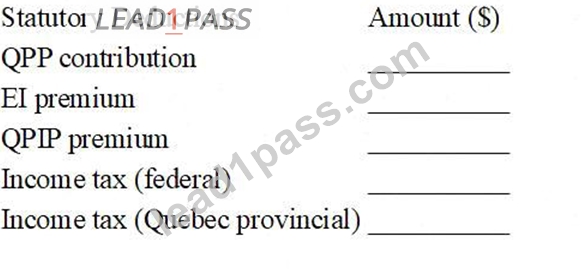
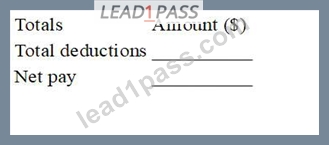
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases

Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 49
Rosa joined Avion Electronics in April 1983. Her employment was terminated on November 30, 2015 and she was paid a $62,500.00 retiring allowance. Rosa joined her company's pension plan in 1986 and was fully vested on termination of employment. Calculate the non-eligible portion of the retiring allowance.
Answer:
Explanation:
$32,000.00 non-eligible portion
Explanation:
CRA requires separating a retiring allowance into an eligible and non-eligible portion. The eligible portion is the maximum that can be transferred to an RRSP/RPP under the special rules (without using regular RRSP room). The formula is: $2,000 for each year (or part-year) of service before 1996, plus an additional $1,500 for each year (or part-year) before 1989 in which the employee had no employer pension/DPSP benefit vested at the time of payment (or previously paid).
Rosa worked from 1983 to 1995 (inclusive) for pre-1996 service: 13 years × $2,000 = $26,000.
For the extra pre-1989 amount: she joined the pension plan in 1986 and was fully vested when paid the retiring allowance in 2015, so 1986-1988 do not qualify for the extra $1,500. However, 1983-1985 were years before 1989 when she had no vested employer pension benefit, so 3 years × $1,500 = $4,500.
Eligible portion = $26,000 + $4,500 = $30,500.
Non-eligible portion = $62,500 # $30,500 = $32,000.
NEW QUESTION # 50
In which province or territory is the employer-paid premium for private health insurance coverage that includes dental and prescription coverage considered to be a non-cash taxable benefit?
Answer: B
Explanation:
In Quebec, employer-paid premiums (contributions) to a group insurance plan, including a private health services plan (which commonly covers items like dental and prescription drugs), are treated as a taxable benefit for the employee for Quebec purposes. Revenu Quebec explicitly states that contributions (premiums) an employer pays under a group insurance plan for coverage received by an employee constitute a taxable benefit.
Because the employer is paying the premium directly to the insurer (the employee receives coverage rather than cash), this is treated as a non-cash taxable benefit in payroll classification terms. The payroll impact is that this taxable benefit must be included in the employee's Quebec taxable income and reported on the RL-1 (and handled according to Quebec source deduction rules).
Outside Quebec, employer-paid health/dental plan premiums are generally not treated the same way for provincial taxable benefit purposes, which is why the correct answer among the options is Quebec.
NEW QUESTION # 51
What information is required to calculate thestandby charge, thereduced standby charge, and theoperating cost benefitfor a company-owned automobile?
Answer: D
Explanation:
CRA's automobile benefit calculations require multiple data points because there are usuallytwo components thestandby charge(vehicle availability) and theoperating expense benefit(personal driving where the employer pays operating costs). CRA's guidance on employer-provided automobiles explains that standby charge calculations use the automobile'scost (capital cost) including applicable taxesand the time the vehicle wasavailableto the employee, while the reduced standby charge and operating benefit depend on kilometres drivenand the split betweenbusiness and personal use.
To determine whether areduced standby chargeapplies, you need availability plusbusiness-use requirements(which are evidenced through total/business kilometres). To calculate the operating expense benefit, you needpersonal kilometres(often derived from total kilometres minus business kilometres) or detailed personal km directly.
Therefore, the complete and correct set of required inputs is:capital cost (with sales tax), availability, total kilometres, business kilometres, and personal kilometres-which is optionD.
NEW QUESTION # 52
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 53
......
Latest National Payroll Institute PF1 Dumps are here to help you to pass your National Payroll Institute Certification exam with Lead1Pass' valid, real, and updated PF1 Exam Questions with passing guarantee. The National Payroll Institute PF1 certification is a valuable certificate that is designed to advance the professional career. With the Payroll Fundamentals 1Exam (PF1) certification exam seasonal professionals and beginners get an opportunity to demonstrate their expertise. The Payroll Fundamentals 1Exam exam recognizes successful candidates in the market and provides solid proof of their expertise.
PF1 Certification Dumps: https://www.lead1pass.com/National-Payroll-Institute/PF1-practice-exam-dumps.html
DOWNLOAD the newest Lead1Pass PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1gu0NGjaVANHhkgSoIvxu-IodTgcuh3Wh