For the AFP-Exam-1 web-based practice exam no special software installation is required. because it is a browser-based AFP-Exam-1 practice test. The web-based Applied Financial Planning Certification Exam 1 (AFP) practice exam works on all operating systems like Mac, Linux, iOS, Android, and Windows. In the same way, IE, Firefox, Opera and Safari, and all the major browsers support the web-based CSI AFP-Exam-1 Practice Test. So it requires no special plugins.
| Section | Weight | Objectives |
|---|---|---|
| Asset and Liability Management | 11% | - Debt Management - Personal Balance Sheet Analysis - Budgeting - Cash Flow Management |
| Retirement Planning | 17% | - Retirement Needs Analysis - Registered Retirement Savings Plans - Retirement Income Strategies - Pension Plans |
| Professional Conduct and Regulatory Compliance | 10% | - Compliance Responsibilities - Regulatory Requirements - Ethics and Professional Standards |
| Investment Planning | 17% | - Portfolio Construction - Investment Products - Asset Allocation - Investment Theory |
| Estate Planning | 13% | - Trust and Beneficiary Planning - Wills - Powers of Attorney - Estate Transfer Strategies |
| Client Relationship and Practice Management | 6% | - Client Discovery - Practice Management - Communication and Advisory Process |
| Risk Management and Insurance | 12% | - Disability and Health Insurance - Risk Assessment - Life Insurance - Risk Transfer Strategies |
| Tax Planning | 14% | - Registered Plans - Tax-Efficient Strategies - Tax Deductions and Credits - Income Tax Fundamentals |
>> Reliable CSI AFP-Exam-1 Test Tutorial <<
Our society needs all kinds of comprehensive talents, the AFP-Exam-1 latest preparation materials can give you what you want, but not just some boring book knowledge, but flexible use of combination with the social practice. Therefore, it is necessary for us to pass the qualification AFP-Exam-1 examinations, the AFP-Exam-1 study practice question can bring you high quality learning platform. If you want to progress and achieve their ideal life, if you still use the traditional methods by exam, so would you please choose the AFP-Exam-1 test materials, it will surely make you shine at the moment.
NEW QUESTION # 19
Jaycee has created an investment portfolio for his client, Adam, which is designed to achieve his long-term objectives and is consistent with his risk tolerance and constraints. It also has to be reassessed periodically to ensure that the long-term benchmark mix continues to reflect Adam's circumstances. Which asset allocation strategy is Jaycee utilizing?
Answer: D
Explanation:
Jaycee is using strategic asset allocation. The portfolio is built around Adam's long-term objectives, risk tolerance, constraints, and benchmark mix, then reassessed periodically to confirm that the policy allocation still fits his circumstances. Strategic allocation is not an attempt to move aggressively between sectors or asset classes based on near-term forecasts. Tactical allocation would involve short-term deviations from the policy mix to exploit perceived market opportunities. Active management refers to security selection or manager decisions intended to outperform a benchmark. Integrated is not the standard allocation term being tested. The AFP course treatment emphasizes that the long-term asset mix is the primary driver of portfolio risk and return; periodic review and rebalancing keep the portfolio aligned with the plan. Jaycee's process is disciplined, policy-based, and client-specific, which is strategic allocation. Study Guide focus: strategic asset allocation, rebalancing, investment policy, risk tolerance, and long-term benchmark mix. The review does not replace the policy mix; it tests whether the policy mix still remains appropriate.
NEW QUESTION # 20
Barbara, age 50, is meeting with her financial planner, Clark. Barbara has been hired as the Chief Executive Officer of a very successful privately owned business. Her salary will be $200,000 annually, plus a bonus.
Which retirement savings option should Clark recommend for Barbara?
Answer: D
Explanation:
An individual pension plan is the appropriate retirement savings option for Barbara. She is age 50, will earn a high salary as CEO of a successful privately owned business, and is likely in a position where an employer- sponsored defined benefit style arrangement can provide enhanced retirement funding. IPPs are particularly useful for older, high-income incorporated business owners or executives because permitted contributions can exceed RRSP limits under actuarial funding rules. A retirement compensation arrangement can supplement retirement benefits for very high earners, but the standard AFP recommendation in this fact pattern is the IPP.
A general defined benefit plan is not as targeted as an individual pension plan, and a deferred profit-sharing plan is usually less appropriate for maximizing retirement savings for a specific senior executive.
Implementation requires actuarial, legal, and tax administration. Study Guide focus: individual pension plans, executive retirement planning, incorporated businesses, RRSP limits, and tax-assisted savings. The recommendation should be confirmed with actuarial and tax advice because IPPs carry formal funding and administration rules.
NEW QUESTION # 21
Consider the following information for a client's portfolio: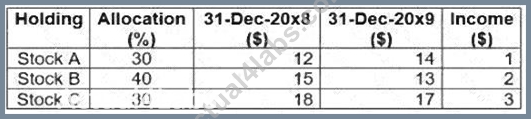
What is the annual rate of return for this portfolio?
Answer: C
Explanation:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
NEW QUESTION # 22
Chris is a self-employed contractor discussing his retirement plans with his financial planner, Joseph. Chris is considering incorporating his business and drawing funds from his corporation to fund his retirement income, yet he wants to ensure it does not impact his business's financial position. What advice should Joseph give to Chris?
Answer: B
Explanation:
Joseph should refer Chris to an accountant because the immediate issue is the tax and financial impact of incorporation and retirement cash extraction. Incorporating can change how income is earned, retained, invested, and withdrawn through salary, dividends, shareholder loans, or corporate distributions. It can affect CPP participation, RRSP room, passive investment income, corporate cash flow, creditor separation, and after- tax retirement funding. A lawyer is important for legal formation, shareholder agreements, and corporate records, but the facts emphasize the business's financial position and retirement-income funding. An online incorporation service is insufficient for planning. Joseph should not provide detailed corporate tax advice outside his competence or recommend changes without specialist input. The AFP standard is to identify the planning issue, explain the need for coordinated advice, and refer to the appropriate professional. Study Guide focus: incorporation, tax integration, professional referrals, retirement cash flow, and scope of competence.
The referral should occur before Chris restructures compensation, retains corporate surplus, or relies on corporate assets for retirement income.
NEW QUESTION # 23
Evan meets with his financial planner to review his concerns around inflation and its impact on his TFSA investment portfolio. His financial planner researches the current holdings and recommends that he sells one of the portfolio's equity funds. Which replacement option should the financial planner recommend to Evan?
Answer: C
Explanation:
The inflation concern directs the planner toward assets that may respond positively to rising prices. Real estate investment trusts hold income-producing property, and rents or property values may adjust over time as inflation affects replacement cost and lease rates. That does not make REITs risk-free, but they are more directly inflation-sensitive than nominal guaranteed products. GICs and treasury bills preserve nominal capital but may lose purchasing power after inflation and tax. Gold bullion may be used as a speculative inflation hedge, but it produces no income and can be volatile; it is not the best replacement for an equity fund within a diversified TFSA portfolio unless the mandate specifically permits that exposure. The planner should recommend an inflation-aware asset that remains investment-oriented and diversified. AFP investment planning treats inflation as purchasing-power risk, not simply price volatility. Study Guide focus: inflation risk, real assets, REITs, TFSA investment selection, and portfolio construction.
NEW QUESTION # 24
......
The best investment for the future is improving your professional ability and obtaining AFP-Exam-1 certification exam will bring you great benefits for you. For most IT candidates, passing AFP-Exam-1 actual test will make you stand out from the other people in the interview and offer you more opportunity. The matter now is how to prepare the AFP-Exam-1 Questions and answers in a short time, our AFP-Exam-1 study guide is the best effective way to get through the exam and obtain the certification.
AFP-Exam-1 Latest Braindumps Ebook: https://www.actual4labs.com/CSI/AFP-Exam-1-actual-exam-dumps.html