P.S. Free & New IIA-CIA-Part3 dumps are available on Google Drive shared by Pass4suresVCE: https://drive.google.com/open?id=1nQFWQKSwCkoIfOsBpE6a0PLrrnSC7TWq
If you feel difficult in choosing which version of our IIA-CIA-Part3 reliable exam guide, if you want to be simple, PDF version may be suitable for you. PDF version is a normal file. Many candidates are used to printing out and then writing & reading of IIA-CIA-Part3 reliable exam guide on paper. Yes, it is silent and clear. Also if you have some unclearly questions, you can ask or talk with others easily. Others may just think that it is normally practice material. Also you can print out many copies of IIA IIA-CIA-Part3 Reliable Exam Guide and share with others.
IIA-CIA-Part3 certification exam is designed to test the knowledge and skills of candidates in various areas of internal auditing. IIA-CIA-Part3 exam covers a broad range of topics, including the role of internal auditing in organizations, the principles of corporate governance, the management of risks, the use of technology in internal auditing, and the importance of effective communication. Passing the exam requires a solid understanding of these topics and their application in real-world scenarios.
Passing the IIA-CIA-Part3 Exam demonstrates that an individual has a comprehensive understanding of business concepts and their application to internal auditing. It also demonstrates a commitment to professional development and a desire to enhance one's skills and knowledge. Internal Audit Function certification opens up new career opportunities and increases earning potential. Overall, the IIA-CIA-Part3 certification is a valuable asset for internal auditors looking to advance their careers in the business world.
>> IIA-CIA-Part3 Exam Questions Vce <<
Through our investigation and analysis of the real problem over the years, our IIA-CIA-Part3 prepare questions can accurately predict the annual IIA-CIA-Part3 exams. In the actual exam process, users will encounter almost half of the problem is similar in our products. Even if the syllabus is changing every year, the IIA-CIA-Part3 quiz guide’s experts still have the ability to master propositional trends. Believe that such a high hit rate can better help users in the review process to build confidence, and finally help users through the qualification examination to obtain a certificate. All in all, we want you to have the courage to challenge yourself, and our IIA-CIA-Part3 Exam Prep will do the best for the user's expectations.
IIA-CIA-Part3 certification exam is a crucial step for internal auditors who want to demonstrate their proficiency in business knowledge. IIA-CIA-Part3 exam is the third part of the Certified Internal Auditor (CIA) certification process offered by the Institute of Internal Auditors (IIA). IIA-CIA-Part3 Exam is designed to assess a candidate's ability to apply business concepts and principles to internal auditing practices.
NEW QUESTION # 613
Dale has 20 days to complete production of an order for an important customer. The customer wants 96 units of product that may be painted either red or white. The red units can be produced at a rate of 4 per day. The white units, because of a different quality of paint, can be produced at a rate of 7 per day. The materials for the red units cost US $80 each, while the white units cost US $120 each. Dale wants to keep costs at a minimum. What is the constraint that expresses the number of units to be produced?
Answer: A
Explanation:
The constraint function that expresses the number of units to be produced is R + W = 96, but that is not one of the answer choices. Another constraint is that the total quantities of red (R) and white (W) units must be produced in 20 or fewer days at a rate of 4 red units per day and 7 white units per day. Thus, the time constraint is (R / 4) + (W + 7) 20.
NEW QUESTION # 614
An organization has adopted a bring-your-own-device (BYOD) policy, and employees can access organizational data via their smart devices.
Which of the following authentication policy requirements is the most advisable?
Answer: A
Explanation:
The question asks specifically about an authentication policy requirement. The strongest authentication option listed is a passcode followed by a verification response, because this represents multi-factor or two-step authentication. It requires more than a single device passcode and reduces the risk that a stolen or compromised device can access organizational data. A VPN protects communications but is not itself the best authentication requirement. An eight-digit passcode or complicated swipe pattern is only a single authentication factor. Remote wipe and encryption are important mobile security controls, but they are not authentication requirements. Internal auditors reviewing BYOD should distinguish authentication, encryption, remote wipe, device management, and network security. For authentication, Option D is correct.
NEW QUESTION # 615
The current generation of ERP software ERP II) may include an advanced planning and scheduling system that:
Answer: D
Explanation:
An advanced planning and scheduling system may be an element of a supply chain management application for a manufacturer. It controls the flow of materials and components within the chain. Schedules are created given projected costs, lead times, and inventories.
NEW QUESTION # 616
An entity uses the retail method of inventory estimation for interim reporting purposes.
Management expects some normal shrinkage in the inventory because of theft. What effect will the failure to consider this shrinkage have on the computation of1) the cost retail ratio, and2) the estimated ending inventory at retail?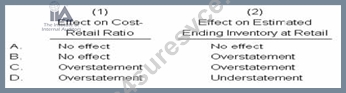
Answer: D
Explanation:
The retail method of inventory estimation applies a cost-retail ratio to the ending inventory at retail to determine ending inventory at cost For example, a popular method calculates the ratio as goods available for sale at cost divided by goods available at retail, with markups but not markdowns included in the calculation of the retail amount. Normal inventory is subtracted from the retail amount of goods available because are not available. However, abnormal amounts of theft, etc., are removed from the cost and retail amounts. The reason for the difference in treatment is that normal but not abnormal inventory losses are anticipated and included in the selling retail value). Accordingly, failure to account for normal inventory shrinkage has no effect on the calculate cost-retail ratio but overstates ending inventory at retail.
NEW QUESTION # 617
According to IIA guidance, which of the following statements is true regarding analytical procedures?
Answer: B
Explanation:
Analytical procedures involve evaluating financial and operational data by examining plausible relationships between numbers, trends, and industry benchmarks. These procedures assume that data relationships exist and will continue unless there is evidence to the contrary.
(A) Data relationships are assumed to exist and to continue where no known conflicting conditions exist. # Correct. Analytical procedures rely on historical trends and logical relationships between data (e.g., revenue vs. expenses, payroll vs. employee count). If no unusual variations or red flags are observed, auditors assume continuity.
IIA GTAG "Auditing Business Intelligence" supports the assumption that data relationships persist unless evidence suggests otherwise.
(B) Analytical procedures are intended primarily to ensure the accuracy of the information being examined.
Incorrect. The primary goal of analytical procedures is not absolute accuracy but rather identifying trends, anomalies, and risks that require further investigation.
(C) Data relationships cannot include comparisons between operational and statistical data.
Incorrect. Operational and statistical data are commonly used in analytical procedures (e.g., comparing production output with raw material consumption, or customer transactions with website visits).
IIA GTAG "Data Analytics: Elevating Internal Audit Performance" highlights the importance of using both financial and operational data in analytical testing.
(D) Analytical procedures can be used to identify unexpected differences, but cannot be used to identify the absence of differences.
Incorrect. Analytical procedures can identify both unexpected variances and expected consistency. Auditors analyze trends, seasonal fluctuations, and relationships, detecting both errors and missing anomalies.
IIA GTAG - "Auditing Business Intelligence"
IIA GTAG - "Data Analytics: Elevating Internal Audit Performance"
IIA Standard 2320 - Analysis and Evaluation
Analysis of Answer Choices:IIA References:Thus, the correct answer is A, as analytical procedures assume data relationships exist and continue unless conflicting conditions arise.
NEW QUESTION # 618
......
IIA-CIA-Part3 Test Free: https://www.pass4suresvce.com/IIA-CIA-Part3-pass4sure-vce-dumps.html
2026 Latest Pass4suresVCE IIA-CIA-Part3 PDF Dumps and IIA-CIA-Part3 Exam Engine Free Share: https://drive.google.com/open?id=1nQFWQKSwCkoIfOsBpE6a0PLrrnSC7TWq