Several advantages we now offer for your reference. On the one hand, our AFP-Exam-1 learning questions engage our working staff in understanding customers’ diverse and evolving expectations and incorporate that understanding into our strategies, thus you can 100% trust our AFP-Exam-1 Exam Engine. On the other hand, the professional AFP-Exam-1 study materials determine the high pass rate. According to the research statistics, we can confidently tell that 99% candidates after using our products have passed the AFP-Exam-1 exam.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Risk Management and Insurance | 12% | - Life Insurance - Disability and Health Insurance - Risk Assessment - Risk Transfer Strategies |
| Topic 2: Retirement Planning | 17% | - Retirement Income Strategies - Registered Retirement Savings Plans - Pension Plans - Retirement Needs Analysis |
| Topic 3: Asset and Liability Management | 11% | - Debt Management - Budgeting - Personal Balance Sheet Analysis - Cash Flow Management |
| Topic 4: Tax Planning | 14% | - Tax Deductions and Credits - Income Tax Fundamentals - Registered Plans - Tax-Efficient Strategies |
| Topic 5: Estate Planning | 13% | - Powers of Attorney - Estate Transfer Strategies - Trust and Beneficiary Planning - Wills |
| Topic 6: Investment Planning | 17% | - Portfolio Construction - Investment Products - Asset Allocation - Investment Theory |
| Topic 7: Client Relationship and Practice Management | 6% | - Communication and Advisory Process - Practice Management - Client Discovery |
| Topic 8: Professional Conduct and Regulatory Compliance | 10% | - Regulatory Requirements - Compliance Responsibilities - Ethics and Professional Standards |
>> CSI AFP-Exam-1 Reliable Practice Materials <<
Being respected and gaining a high social status maybe what you always long for. But if you want to achieve that you must own good abilities and profound knowledge in some certain area. Passing the AFP-Exam-1 certification can prove that and help you realize your goal and if you buy our AFP-Exam-1 Quiz prep you will pass the AFP-Exam-1 exam successfully. Our product is compiled by experts and approved by professionals with years of experiences. You can download and try out our latest AFP-Exam-1 quiz torrent freely before your purchase.
NEW QUESTION # 110
Demario, age 28, has just started his own law firm. He met with his financial planner, Ivy, and she told him that he needs insurance, but Ivy did not specify which type. Demario is single and owns his own home. At this point in his career, his greatest asset is his human capital. Which type of insurance should Ivy have specified to purchase in order for Demario to best protect this asset?
Answer: B
Explanation:
Demario's human capital is his capacity to earn professional income from his law practice. A disability can destroy that earning capacity without causing death and without necessarily triggering critical illness coverage. Disability insurance is therefore the correct product to protect his greatest asset. Term life insurance would be more relevant if he had dependants, estate obligations, or a debt-repayment need at death. Extended health care helps with medical and dental costs but does not replace a lawyer's income if he cannot work.
Critical illness insurance pays on diagnosis of specified illnesses and can supplement planning, but it does not provide the same ongoing income-replacement function as disability coverage. Because Demario is self- employed, policy features such as own-occupation definition, elimination period, benefit period, and business overhead coverage should be reviewed carefully. Study Guide focus: human capital, disability insurance, self- employed professionals, income replacement, and risk management. The recommendation is therefore built around income continuity, not estate creation or reimbursement of medical expenses.
NEW QUESTION # 111
In which life cycle stage would a financial planner identify his client to be if they have a high mortgage balance and an unstable or lower income, and are willing to take on investment risk because of their longer time horizon?
Answer: D
Explanation:
The accumulation stage is characterized by asset building while major liabilities and career uncertainty may still exist. Clients in this stage often have mortgages, young families or early career responsibilities, and a long time horizon before retirement. Because the investment horizon is long, they may be able to accept more growth exposure, provided cash flow, emergency reserves, and debt servicing are under control. The consolidation stage usually occurs later, when income is stronger, debts are falling, and retirement funding accelerates. Financial independence refers to clients who can maintain lifestyle without employment income.
Gifting generally occurs after core lifetime needs are secure and surplus wealth can be transferred. The scenario states high mortgage balance, unstable or lower income, and willingness to take investment risk due to a long horizon; that is the accumulation phase. Study Guide focus: client life-cycle stages, risk capacity, accumulation planning, mortgage debt, and time horizon. Insurance planning and emergency reserves are usually reviewed alongside investments because human-capital protection is critical in this stage.
NEW QUESTION # 112
Carla, a financial planner, is meeting with a long-standing client, Jonathan. Jonathan informs Carla that he is upset and disappointed with the negative returns experienced with his investment portfolio. After acknowledging Jonathan's concerns, what should Carla's first step be in addressing his complaint?
Answer: D
Explanation:
After acknowledging Jonathan's concern, Carla should revisit his goals, objectives, and risk tolerance. A complaint about negative returns may indicate normal market volatility, unsuitable risk exposure, changed circumstances, or misunderstanding of the investment plan. The planner should not immediately recommend replacement investments before confirming whether the current portfolio still fits the client's KYC profile.
Simply reminding Jonathan that investing is long term may sound dismissive and does not address suitability.
Repeating that investments involve volatility may be accurate but incomplete. The first professional step is to re-open the planning conversation, confirm objectives, time horizon, liquidity needs, risk tolerance, risk capacity, and expectations, then determine whether any portfolio change or complaint process is required.
AFP practice emphasizes review and documentation when a client expresses dissatisfaction with investment outcomes. Study Guide focus: client review meetings, complaints, risk tolerance, portfolio suitability, and relationship management. The review may show that no product change is required, but that conclusion must be supported by updated facts.
NEW QUESTION # 113
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.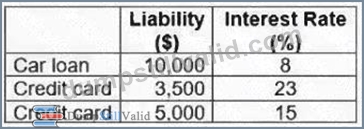
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: A
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 114
A higher-income spouse contributes to a spousal RRSP for the lower-income spouse. The lower-income spouse withdraws the contribution amount the following year. What should the planner warn them about?
Answer: D
Explanation:
Spousal RRSPs support retirement income splitting, but the attribution rules prevent short-term deduction-and- withdrawal planning. If the annuitant spouse withdraws amounts from a spousal RRSP within the attribution period, recent contributions may be included in the contributing spouse's income rather than the annuitant's income. Option A is wrong because RRSP withdrawals are taxable unless a specific program or offset applies.
Option C is wrong because RRSP withdrawals are ordinary income, not capital gains. Option D misstates the mechanics; RRSP contribution room belongs to the contributor and is affected by contributions, but spousal RRSP room is not a separate permanent account destroyed by one contribution. A planner should review timing, contribution history, expected retirement brackets, pension income, and cash flow needs before recommending withdrawals. The strategy works best when used for longer-term retirement income planning rather than immediate tax arbitrage. References/topics: spousal RRSP, attribution rules, retirement income splitting, taxable withdrawals. Timing records are essential because attribution depends on recent contributions.
NEW QUESTION # 115
......
Using our AFP-Exam-1 study braindumps, you will find you can learn about the knowledge of your exam in a short time. Because you just need to spend twenty to thirty hours on the practice exam, our AFP-Exam-1 study materials will help you learn about all knowledge, you will successfully pass the AFP-Exam-1 Exam and get your certificate. So if you think time is very important for you, please try to use our AFP-Exam-1 study materials, it will help you save your time.
Exam AFP-Exam-1 Topic: https://www.dumpstillvalid.com/AFP-Exam-1-prep4sure-review.html