What's more, part of that Actual4test ClaimCenter-Business-Analysts dumps now are free: https://drive.google.com/open?id=1qfyoc8EKFEd7MSpY7OEl-nO-ltWBlkAG
With the development of technology, our ClaimCenter-Business-Analysts training engine will be updated regularly. Actually, we never stop researching the new functions of the study materials. Normally, we will release our new version of the ClaimCenter-Business-Analysts exam simulation on our website once it passed the tests. Many details will be perfected in the new version of our ClaimCenter-Business-Analysts Study Materials not not on the content, but also on the displays. And we have been in this career for over ten years, our ClaimCenter-Business-Analysts learning guide is perfect.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
>> ClaimCenter-Business-Analysts Reliable Study Guide <<
We will continue to pursue our passion for better performance and human-centric technology of latest ClaimCenter-Business-Analysts quiz prep. And we guarantee you to pass the exam for we have confidence to make it with our technological strength. A good deal of researches has been made to figure out how to help different kinds of candidates to get the ClaimCenter-Business-Analysts certification. We treasure time as all customers do. Therefore, fast delivery is another highlight of our laTest ClaimCenter-Business-Analysts Quiz prep. We are making efforts to save your time and help you obtain our product as quickly as possible. We will send our ClaimCenter-Business-Analysts exam guide within 10 minutes after your payment. You can check your mailbox ten minutes after payment to see if our ClaimCenter-Business-Analysts exam guide are in.
NEW QUESTION # 40
Succeed Insurance allows field Adjusters to write checks directly to the insured to cover damage costs for minor claims such as:
* Personal auto claims involving cracked windshields
* Homeowners claims involving minor glass breakage
The Adjuster uses the Manual Check Wizard to record the check number and amount against a reserve line.
Succeed requires Supervisor approval for all manual checks to ensure that the paper checks are verified against the payment information in ClaimCenter.
Which two limits or rules must be configured in ClaimCenter to ensure that these manual payments are sent to the correct person for approval? (Choose two.)
Answer: A,C
Explanation:
To enforce an approval workflow for a specific type of financial transaction (like "Manual Checks") regardless of the dollar amount, a Business Analyst must leverage both Authority Limits and Transaction Approval Rules.
* Authority Limits (D):These are the primary controls for financial exposure. While typically used for amounts (e.g., "Limit of $5,000"), they are the foundational mechanism that triggers the system's
"Pending Approval" state. For this scenario, an authority limit could be set to $0 for the specific payment method of "Manual Check" to force all such payments into the approval workflow.
* Transaction Approval Rules (C):These rules allow for more granular, logic-based approval triggers beyond simple amounts. Since the requirement specifies "all manual checks" (implying a condition based on themethodof payment, not just the amount), aTransaction Approval Ruleis the best practice configuration. The rule would be written to state:"If Payment Method is Manual, then Approval is Required."
* Why not A (Approval Routing)?While Approval Routing rules determinewhoreceives the request (the
"correct person"), the default behavior in ClaimCenter is to route approvals to the user's Supervisor.
Since the requirement is simply "Succeed requires Supervisor approval," the standard routing logic likely suffices without needing new custom configuration. The critical configuration needed is the trigger(C and D) to stop the payment in the first place.
NEW QUESTION # 41
An Adjuster at Succeed Insurance is handling a homeowners claim with a dwelling exposure for damage to the insured's home. The Adjuster's Authority Limit Profile has the following limits: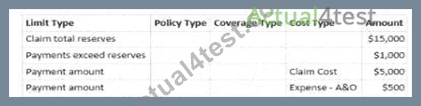
The table below is a view of the property claims organization within Succeed Insurance. The Adjuster is a member of the group Property - Team A.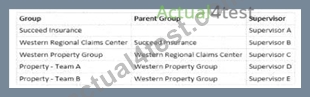
The Adjuster creates a payment in the amount of $6,500 for repairs to the insured's home. How will it be processed assuming that the claim has sufficient reserves for the payment?
Answer: B
Explanation:
This scenario involves checking financial Authority Limits and determining the correct Approval Routing hierarchy in Guidewire ClaimCenter.
* Check Authority Limits:First, compare the transaction amount against the user's specific limits.
* The payment is for "repairs to the insured's home," which is classified asClaim Cost(Indemnity).
* According to the provided Authority Limit Profile, the Adjuster has a "Payment amount" limit of
$5,000for Claim Cost.
* The transaction amount is$6,500.
* Since$6,500 > $5,000, the limit is exceeded, meaning the paymentrequires approval(Ruling out Option B).
* Determine Routing:When a financial transaction requires approval, ClaimCenter routes the approval activity to the supervisor of the group to which the user belongs.
* The Adjuster is a member ofProperty - Team A.
* According to the Organization chart provided, the Supervisor for "Property - Team A" is Supervisor D.
* Therefore, the system will generate an approval activity and assign it specifically to Supervisor D). Supervisor C is the manager of theparentgroup (Western Property Group), so the activity would only go to them if Supervisor Dalsolacked the authority to approve the $6,500, requiring further escalation. However, the initial routing is always to the immediate supervisor.
Why other options are incorrect:
* Option A:Supervisor C is the "Grand-boss" (Supervisor of the parent group), not the immediate supervisor.
* Option B:The amount ($6,500) clearly exceeds the defined limit ($5,000), so automatic processing is impossible.
* Option C:Supervisor A is at the top of the hierarchy (Succeed Insurance), far removed from the initial approval step.
NEW QUESTION # 42
Succeed Insurance has a strategic initiative to offer pay-as-you-drive personal auto insurance to compete with other large carriers. Customers who choose these policies must either own a vehicle that is equipped with a monitoring device or agree to install a device provided by Succeed. The monitoring device collects information about how the drivers of a covered vehicle drive, including how fast they drive, how hard they brake, and how many miles/kilometers the vehicle travels within a policy period.
This information is logged, and premiums are based on how the insured's driving behavior is categorized.
When a claim is reported, the log files must be obtained in order to
analyze the information captured by the monitoring device at the time of the incident.
Succeed plans to collect and evaluate the Vehicle Monitoring Log files in the first implementation phase, which is scheduled for release in 60 days. The project sponsors have instructed the implementation team to use base product functionality over customization. Integration should be leveraged where possible to avoid manual data entry.
The New Claim Wizard must capture whether or not the vehicle has a monitoring device installed when a personal auto claim is created against a pay-as-you-drive policy.
Which feature of the base product enforces this claim creation requirement?
Answer: D
Explanation:
In Guidewire ClaimCenter, Validation Rules are used to enforce data integrity and business requirements at specific stages of the claim lifecycle. These stages are defined by Validation Levels.
* New Loss Completion (Option B):This validation level is specifically designed as the "gatekeeper" for the New Claim Wizard (FNOL). Rules triggered at this level run when the user attempts to click
"Finish" to submit the new claim. If a rule fails (e.g., "If Policy Type = Pay-as-you-drive AND Monitoring Device is Null"), the system prevents the claim from being created and highlights the missing field. This directly meets the requirement to enforce data capture "when a personal auto claim is created." Why other options are incorrect:
* Ability to Pay (A):This level runs when a user tries to issue a check. Using this would allow the claim to be createdwithoutthe device info, only blocking the user later when they try to pay, which is too late for the requirement.
* Custom Level (C):Creating custom levels is possible but discouraged when a standard level fits the purpose, aligning with the "use base product functionality" principle.
* Load and Save (D):This level runs every time the claim is saved (even as a draft). Enforcing mandatory fields here can frustrate users who need to save their work partially complete.
NEW QUESTION # 43
Drivers for Rideshare companies need insurance that provides protection when they are driving the vehicle for personal reasons. This will be the Succeed Insurance standard Personal Auto Policy. However, they also need insurance to protect them from the increased risks associated with working as a Rideshare Driver. This would include when they are logged in to the Rideshare application waiting for a customer match, on their way to pick up a customer, but not when a customer has entered the vehicle.
When a driver is working as a Rideshare Driver, this new Rideshare coverage will protect them from the following types of risks, and there is a need to be able to collect the appropriate information about the losses:
. Injury to a first-party driver
. Damaged personal property of the third-party passengers
Which two exposures need to be configured? (Choose two.)
Answer: A,C
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
To satisfy the requirements for the new "Rideshare" coverage product, the Business Analyst must map the described risks to the correct Exposure Types in the ClaimCenter data model.
* Risk: Injury to a first-party driver:In insurance terminology, "First Party" refers to the insured (the driver). Coverage for injuries sustained by the driver themselves is typically handled byMedical Payments(MedPay) or Personal Injury Protection (PIP). Among the choices provided,Rideshare Medical Payments (Option C)is the correct exposure type to cover medical costs for the driver regardless of fault. (Option E, Liability Bodily Injury, would cover injuries toothersthat the driver hit).
* Risk: Damaged personal property of third-party passengers:This refers to liability for damage to property belonging to others. While typically "Property Damage Liability," the specific option provided that fits this description isRideshare Personal Property Protection (Option B). This exposure would be configured to capture details about the damaged items (e.g., luggage, electronics) belonging to the passengers.
Why other options are incorrect:
* Option E (Liability Bodily Injury):This is for Third Party injuries (e.g., pedestrians or people in other cars), not the First Party driver.
* Option D (Under Insured Motorist):This applies when the Rideshare driver is hit by someone else who doesn't have enough insurance. The prompt focuses on the risksofthe driver working, not the financial failure of others.
NEW QUESTION # 44
When creating a new Personal Auto claim, Succeed Insurance would like to identify when Rideshare is the primary use for a vehicle. A Business Analyst (BA) thinks that Primary Use already exists as a typekey on the Vehicle Details screen.
What are two ways the BA can confirm whether this field is configured in ClaimCenter and, if it is, which values are available in the typelist? (Choose two.)
Answer: A,C
Explanation:
To verify the configuration of a specific field and its available values (typelist) within a specific implementation (like Succeed Insurance), a Business Analyst must consult the sources that reflect the current, actual system configuration, not just the out-of-the-box documentation.
* Option A (Data Dictionary):TheData Dictionaryis the definitive, generated documentation of the running application's data model. It lists allEntities(such as Vehicle) and theirTypekeys(such as PrimaryUse). By navigating to the Data Dictionary, a BA can confirm if the field exists in the database schema and view the specificTypelistvalues (e.g., "Rideshare", "Commuting", "Pleasure") associated with it. This is a primary tool for BAs to understand the data structure.
* Option D (Guidewire Studio):Guidewire Studiois the Integrated Development Environment (IDE) used to configure the application. It contains the "Source of Truth" for all configuration files. A BA (or a developer assisting them) can open thePage Configuration (PCF)files to see the Vehicle Details screen definition or open theTypelistfiles (.tti/.ttx) directly to see exactly which values are defined and active.
Why other options are incorrect:
* Option B (Application Guide):The Application Guide documents theBase (Out-of-the-Box)product features. It does not contain customer-specific customizations or extensions. If "Primary Use" or
"Rideshare" were added or modified by Succeed Insurance, the Application Guide would not reflect this.
* Option C (UI Inspection with CTRL+F):While logging into the application allows a user to see the dropdown on the screen, the shortcutCTRL + Fis merely the browser's "Find" function. It searches visible text on the page but does not provide configuration metadata, hidden values, or definitive proof of the underlying data model structure. The correct shortcut for inspecting widget properties in Guidewire is Alt + Shift + I (Location Info), but even that is less efficient for viewing a full typelist than the Data Dictionary or Studio.
NEW QUESTION # 45
......
From the time you purchase, use, and pass the ClaimCenter-Business-Analysts exam, we will be with you all the time. You can seek our help anytime, anywhere. If you have experienced a very urgent problem while using ClaimCenter-Business-Analysts exam simulating, you can immediately contact online customer service, you'd praise the staff of ClaimCenter-Business-Analysts study engine, because they can solve any problems you have encountered while using ClaimCenter-Business-Analysts exam simulating. All we do is just want you to concentrate on ClaimCenter-Business-Analysts exam learning, Do not hesitate anymore. You will never regret buying ClaimCenter-Business-Analysts study engine!
Pass4sure ClaimCenter-Business-Analysts Pass Guide: https://www.actual4test.com/ClaimCenter-Business-Analysts_examcollection.html
P.S. Free 2026 Guidewire ClaimCenter-Business-Analysts dumps are available on Google Drive shared by Actual4test: https://drive.google.com/open?id=1qfyoc8EKFEd7MSpY7OEl-nO-ltWBlkAG