DOWNLOAD the newest Itcertmaster L4M2 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=138s9o9begKDFKsnm4Re2cceCQPe05SsA
As we all know, respect and power is gained through knowledge or skill. The society will never welcome lazy people. Do not satisfy what you have owned. Challenge some fresh and meaningful things, and when you complete L4M2 exam, you will find you have reached a broader place where you have never reach. There must be one that suits you best. Your life will become more meaningful because of your new change, and our L4M2 question torrents will be your first step.
Upon successful completion of the CIPS L4M2 exam, candidates will be awarded 12 credits towards the CIPS Level 4 Diploma. This qualification is highly regarded in the procurement and supply chain management industry and can lead to a range of career opportunities. Candidates who pass the CIPS L4M2 Exam will have demonstrated their ability to analyze business needs and make informed procurement decisions that contribute to the success of the business.
It is universally accepted that the exam is a tough nut to crack for the majority of candidates, but the related L4M2 certification is of great significance for workers in this field so that many workers have to meet the challenge. Fortunately, you need not to worry about this sort of question any more, since you can find the best solution in this website--our L4M2 Training Materials. With our continued investment in technology, people and facilities, the future of our company has never looked so bright. There are so many advantages of our L4M2 practice test and I would like to give you a brief introduction now.
The Defining Business Needs module is assessed through an exam that consists of 60 multiple-choice questions. L4M2 exam is designed to test the knowledge and skills acquired by professionals during the module. L4M2 Exam is timed and must be completed within two hours. Professionals who successfully pass the exam will receive a certificate of completion from CIPS.
NEW QUESTION # 53
One of the disadvantages of using standards in specification is that...
Answer: B
Explanation:
Using standards in specification is very convenient. They reduce the time and effort to produce. They tend to be very accurate with correct technical terminologies. They are well recognised and accepted by a wide range of suppliers and buyers. However, since a standard is very specific, complex and lengthy, it requires a lot of time to be drafted and approved. Therefore, standard tends to be static and don't encourage innovation. It may also not accommodate latest technology and trends.
Reference:
LO 3, AC 3.1
NEW QUESTION # 54
Daytona Ltd is developing a new product which is more environmental friendly. Though the objectives are set, the project team has no idea on which functions will be customers' favourites. Which of the following will help them decide the 'should-have' functions of the new product?
Answer: A
Explanation:
The Kano model is useful in gaining a thorough understanding of a customer's needs. You can translate and transform the resulting verbatims using the voice of the customer table that, subse-quently, becomes an excellent input as the whatsin a quality function deployment (QFD) House of Quality.
The model involves two dimensions:
Achievement (the horizontal axis), which goes from the supplier didn't do it at all to the supplier did it very well.
Satisfaction (the vertical axis), which goes from total dissatisfaction with the product or service to total satisfaction with the product or service.
Dr. Noriaki Kano isolated and identified three levels of customer expectations: that is, what it takes to positively impact customer satisfaction. The figure below portrays the three levels of need: expected, normal, and exciting.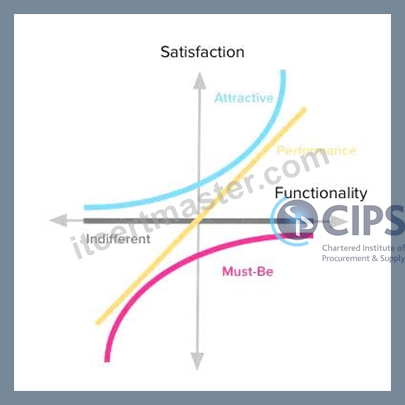
The Thomas-Kilmann Conflict Mode Instrument (TKI) is a conflict style inventory, which is a tool developed to measure an individual's response to conflict situations.
Genichi Taguchi, a Japanese engineer, proposed several approaches to experimental designs that are sometimes called "Taguchi Methods." These methods utilize two-, three-, and mixed-level fractional factorial designs. Large screening designs seem to be particularly favored by Taguchi adherents.
Six Sigma is a method that provides organizations tools to improve the capability of their business processes.
This increase in performance and decrease in process variation helps lead to defect re-duction and improvement in profits, employee morale, and quality of products or services.
Source:
- CIPS study guide page 171-172
- WHAT IS THE KANO MODEL?
LO 3, AC 3.4
NEW QUESTION # 55
Raw materials used in the production of a saleable product are classed as ...
Answer: A
Explanation:
Direct costs are those that can be directly traced to the production of goods or services.
The CIPS L4M2 Study Guide, Chapter 3: Cost Management, defines:
"Direct costs are specifically attributable to a unit of production - for example, raw materials and direct labour used in manufacturing." Option analysis:
* A. Direct costs - Correct. Raw materials are a prime example.
* B. Indirect costs - Include management salaries or admin overheads.
* C. Overheads - Indirect costs like rent or utilities, not materials.
* D. Fixed costs - Do not change with production volume; raw materials vary with production.
Correct answer: A
CIPS Study Guide Reference:
* Module: L4M2 - Defining Business Needs
* Chapter 3: Cost Types
* Section: Direct and Indirect Costs
NEW QUESTION # 56
Which of the following can cause overhead variance? Select TWO that apply:
Answer: B,C
Explanation:
Overhead variances arise when the actual overhead costs incurred differ from the expected amounts. Managers want to understand the reasons for these differences, and so should consider computing one or more of the overhead variances described below. Each of these variances applies to a different aspect of overhead expenditures. It is not necessary to calculate these variances when a manager cannot influence their outcome.
Fixed Overhead Spending Variance
The fixed overhead spending variance is the difference between the actual fixed overhead expense incurred and the budgeted fixed overhead expense. An unfavorable variance means that actual fixed overhead expenses were greater than anticipated. The formula for this variance is:
Actual fixed overhead - Budgeted fixed overhead = Fixed overhead spending variance The amount of expense related to fixed overhead should (as the name implies) be relatively fixed, and so the fixed overhead spending variance should not theoretically vary much from the budget.
Fixed Overhead Volume Variance
The fixed overhead volume variance is the difference between the amount of fixed overhead actually applied to produced goods based on production volume, and the amount that was budgeted to be applied to produced goods. For example, a company budgets for the allocation of $25,000 of fixed overhead costs to produced goods at the rate of $50 per unit produced, with the expectation that 500 units will be produced. However, the actual number of units produced is 600, so a total of $30,000 of fixed overhead costs are allocated. This creates a fixed overhead volume variance of $5,000.
Variable Overhead Efficiency Variance
The variable overhead efficiency variance is the difference between the actual and budgeted hours worked, which are then applied to the standard variable overhead rate per hour. The formula is:
Standard overhead rate x (Actual hours - Standard hours)
= Variable overhead efficiency variance
A favorable variance means that the actual hours worked were less than the budgeted hours, resulting in the application of the standard overhead rate across fewer hours, resulting in less expense being incurred. However, a favorable variance does not necessarily mean that a company has incurred less actual overhead, it simply means that there was an improvement in the allocation base what was used to apply overhead.
Variable Overhead Spending Variance
The variable overhead spending variance is the difference between the actual and budgeted rates of spending on variable overhead. The variance is used to focus attention on those overhead costs that vary from expectations. The formula is:
Actual hours worked x (Actual overhead rate - standard overhead rate)
= Variable overhead spending variance
A favorable variance means that the actual variable overhead expenses incurred per labor hour were less than expected.
In the study guide, CIPS splits overhead variance into volume and expenditure variance. They can be understood as variable and fixed overhead variance respectively.
Reference:
- CIPS study guide page 59
- What are overhead variances? - AccountingTools
LO 1, AC 1.4
NEW QUESTION # 57
Which of these causes variances in budgets?
Quantity discounts
Substitute goods
Loan repayments
Corporation tax
Answer: C
Explanation:
Detailed Explanation:
Quantity discounts: Changes in order quantities can lead to cost savings, impacting budget forecasts.
Substitute goods: Using alternative products can alter planned expenses, causing budget deviations.Loan repayments and taxes are fixed financial obligations and do not directly impact procurement budgeting.
Reference: CIPS Level 4, Cost Management.
NEW QUESTION # 58
......
Exam L4M2 Demo: https://www.itcertmaster.com/L4M2.html
P.S. Free 2026 CIPS L4M2 dumps are available on Google Drive shared by Itcertmaster: https://drive.google.com/open?id=138s9o9begKDFKsnm4Re2cceCQPe05SsA