We have been developing our AFP-Exam-1 practice engine for many years. We have no doubt about our quality. Our experience is definitely what you need. To combine many factors, our AFP-Exam-1 real exam must be your best choice. And our AFP-Exam-1 Exam Questions have been tested by many of our loyal customers, as you can find that the 98% of them all passed their AFP-Exam-1 exam and a lot of them left their warm feedbacks on the website.
| Section | Objectives |
|---|---|
| Financial Planning Foundations | - Ethics and professional standards in financial advising - Financial planning process and client relationship management |
| Retirement Planning | - Retirement savings vehicles and planning principles |
| Investment Planning | - Asset allocation and portfolio basics - Investment products and risk-return profiles |
| Taxation Concepts | - Personal income tax principles - Tax-efficient investment strategies |
| Insurance and Risk Management | - Risk mitigation strategies in financial planning - Life and health insurance fundamentals |
>> AFP-Exam-1 Latest Exam Materials <<
The product is made in three different formats to help customers with different preparation styles meet their needs. One of these formats is CSI AFP-Exam-1 Dumps PDF file which is printable and portable. Users can take CSI AFP-Exam-1 PDF Questions anywhere and use them anytime. They can print these real AFP-Exam-1 questions to save them as paper notes.
NEW QUESTION # 84
Two shareholders sign a buy-sell agreement requiring the surviving shareholder to purchase the deceased shareholder's shares at fair market value. What planning tool most directly funds the death-triggered purchase obligation?
Answer: D
Explanation:
A death-funded buy-sell arrangement requires cash at the precise time a shareholder dies. Life insurance on the shareholders is commonly used because the death benefit provides liquidity when the obligation is triggered. Ownership may be corporate-owned or cross-owned, depending on tax, control, creditor, and agreement design. Option A is irrelevant because an RRSP is a personal retirement account and does not fund a contractual share purchase. Option C is weak because credit may be unavailable or expensive after a shareholder's death, and it shifts the funding risk to the survivor. Option D is too narrow because it pays only for accidental death, not death generally. A properly designed buy-sell plan coordinates the insurance amount, valuation formula, beneficiary or owner structure, agreement wording, tax treatment, and corporate cash flow.
The planner should involve legal and tax advisers because insurance funding must match the binding shareholder agreement. References/topics: buy-sell agreements, business insurance, shareholder planning, liquidity at death.
NEW QUESTION # 85
Jonah is meeting with his client, Muhsina, who owns Myke Inc., a Canadian-controlled private corporation.
Based on current market value, if he decides to sell Myke Inc., Muhsina will have a capital gain of $400.000.
He expects the value of Myke Inc. to increase in future years and has a CNIL balance of $100,000. He wants the future increase in value to be taxed in the hands of his children, Teshi and Kaliyah, and to minimize the cost. What action should Jonah advise Muhsina to take to meet his goal?
Answer: B
Explanation:
Muhsina should sell the shares at fair market value if the objective is to shift future growth to the children while avoiding a below-market transfer problem. A sale for $1 would not avoid tax; related-party tax rules generally deem a disposition at fair market value, and inadequate consideration can create double-tax or attribution complications. Selling at fair market value crystallizes the current value in Muhsina's hands and places future appreciation with Teshi and Kaliyah. The facts mention a current $400,000 capital gain and a CNIL balance, so the planner must coordinate LCGE eligibility and tax cost carefully. Joint accounts do not transfer private corporation growth in a controlled business succession structure and may create ownership and attribution problems. The ideal planning tool might be an estate freeze, but among the available options, a fair-market-value sale is the correct method. Study Guide focus: related-party transfers, fair market value, CNIL, LCGE, business succession, and estate-freeze concepts.
NEW QUESTION # 86
Derek recently inherited $900,000. He asks his financial planner to invest the entire amount in a concentrated portfolio of junior mining stocks. Derek has never invested before, has two young children, and is still deciding whether to purchase a home. What should the planner do first?
Answer: B
Explanation:
The professional issue is suitability under incomplete discovery. A large inheritance, limited investment experience, dependent children, and a possible home purchase all point to the need for a structured review before implementation. The planner must distinguish willingness to speculate from financial capacity to absorb loss. Derek may express high risk appetite, but his liquidity needs and decision uncertainty could make a concentrated junior mining strategy unsuitable. Option A fails because client instructions do not remove the duty to assess suitability and provide appropriate warnings. Option C is premature; the planner can continue if the advice process remains professional and documented. Option D is arbitrary because it imposes a solution before clarifying goals and constraints. The official planning approach is to pause product selection, update KYC, identify short-, medium-, and long-term objectives, quantify emergency reserves and housing needs, and only then design an allocation. References/topics: KYC, suitability, risk capacity, investment planning process.
NEW QUESTION # 87
How should Jenny, a financial planner, explain the benefits of a fee for service method of compensation to a prospective client?
Answer: D
Explanation:
A fee-for-service model reduces the incentive to recommend one product over another because compensation is not driven by product commission. The planner is paid for advice, planning work, or an agreed service arrangement rather than the compensation embedded in a product sale. This does not guarantee perfect objectivity, but it directly addresses product-compensation bias and makes remuneration more transparent.
Option A is not the benefit; charging more because products are complex can create its own conflict if not disclosed. Option B describes performance-based compensation, not fee-for-service financial planning.
Option C is imprecise because compensation is not objectively determined by the quality of the financial plan; it is determined by the fee arrangement. Jenny should explain the model in terms of transparency, alignment, and reduced product-driven incentives. Study Guide focus: planner compensation, fee-for-service advice, conflicts of interest, disclosure, and client relationship management. The compensation discussion should occur before engagement so the client understands what is being paid and why.
NEW QUESTION # 88
Janet's non-registered account holds the funds listed in the following table: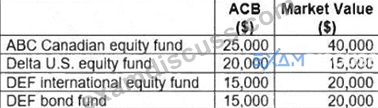
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: C
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 89
......
Are you still feeling uncomfortable about giving up a lot of time to entertain, work or accompany your family and friends in preparation for the exam? Using AFP-Exam-1 Quiz torrent, you can spend less time and effort reviewing and preparing, which will help you save a lot of time and energy. When some candidates trying to overcome an exam, they will all first think of choosing a good study material to prepare for their exam. The Applied Financial Planning Certification Exam 1 (AFP) prep torrent has a variety of self-learning and self-assessment functions to test learning outcome, which will help you increase confidence to pass exam.
AFP-Exam-1 Reliable Exam Test: https://www.examdiscuss.com/CSI/exam/AFP-Exam-1/