BONUS!!! Download part of PDFDumps AFP-Exam-1 dumps for free: https://drive.google.com/open?id=1DMa_kza4lfWhLkcPrWp_GAIwUalbAETC
We have professional technicians to check website at times, therefore if you buy AFP-Exam-1 Study Materials from us, we can ensure you that you can have a clean and safe shopping environment. Moreover AFP-Exam-1 exam braindumps of us is compiled by professional experts, and therefore the quality and accuracy can be guaranteed. We have online and offline chat service stuff, if you have any questions, you can contact us, we will give you reply as quickly as possible.
| Section | Objectives |
|---|---|
| Financial Planning Foundations | - Ethics and professional standards in financial advising - Financial planning process and client relationship management |
| Insurance and Risk Management | - Risk mitigation strategies in financial planning - Life and health insurance fundamentals |
| Retirement Planning | - Retirement savings vehicles and planning principles |
| Investment Planning | - Investment products and risk-return profiles - Asset allocation and portfolio basics |
| Taxation Concepts | - Personal income tax principles - Tax-efficient investment strategies |
>> Valid AFP-Exam-1 Exam Notes <<
To give you an idea before the PDFDumps exam questions purchase, we are offering a free CSI AFP-Exam-1 exam questions demo facility. This demo download facility is available for all three PDFDumps exam question formats. Moreover, we also offer up to 1 year of AFP-Exam-1 Free Exam Questions updates. If you think the AFP-Exam-1 exam questions can help you in AFP-Exam-1 exam preparation then take your buying decision and start preparation. Best of luck!!!
NEW QUESTION # 69
Todd, a financial planner, is meeting with Vanessa, a new client, to review her investment goals and objectives. During the meeting, Vanessa states that she believes the markets are very efficient and should reflect all available information in the price of securities. She is looking for an investment option that will reflect a similar level of risk and return characteristics as the Canadian market. What investment option should Todd recommend with Vanessa that would reflect her opinions?
Answer: A
Explanation:
Vanessa's belief points directly to passive market exposure. If she accepts that markets are efficient and wants risk and return characteristics similar to the Canadian market, an exchange-traded fund tracking a broad Canadian equity index is the most consistent recommendation. An ETF can provide diversified Canadian market exposure, transparent holdings, intraday liquidity, and typically lower management cost than many actively managed strategies. A Canadian value mutual fund is an active or style-biased mandate and may depart materially from total market characteristics. A neutral balanced fund includes fixed income and therefore will not mirror the Canadian equity market. A hedge fund may use leverage, short positions, derivatives, or absolute-return strategies, which do not match her stated view. Todd must still confirm KYC information and suitability, but among the options, the Canadian ETF best operationalizes an efficient-market philosophy. Study Guide focus: passive investing, ETFs, diversification, efficient markets, and investment objective alignment. The recommendation should still be framed inside Vanessa's KYC profile rather than presented as a universal market rule.
NEW QUESTION # 70
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: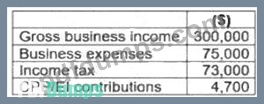
What is Terry's net business income?
Answer: C
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 71
A client asks when his RRSP must generally be converted to a retirement income vehicle. What should the planner explain?
Answer: A
Explanation:
RRSP maturity is age-based. In general, an RRSP must be converted to a retirement income option, such as a RRIF or annuity, by the end of the calendar year in which the annuitant turns 71. Minimum RRIF withdrawals begin the following year if a RRIF is selected. Option B confuses eligibility for some retirement benefits and pension planning milestones with RRSP maturity. Option C is wrong because employment status does not eliminate the conversion requirement. Option D is not required and may be tax-inefficient; a full cash withdrawal could trigger substantial taxable income. A planner should treat conversion as a planning decision, not an administrative afterthought. The client's spouse's age, required income, tax bracket, pension splitting, investment mix, estate goals, and OAS exposure may influence whether to use a RRIF, annuity, or combination. The correct exam answer is the age-71 year-end deadline. References/topics: RRSP maturity, RRIF conversion, annuities, retirement income planning.
NEW QUESTION # 72
Which statement best distinguishes a defined benefit pension plan from a defined contribution pension plan?
Answer: A
Explanation:
A defined benefit pension plan promises a retirement benefit determined by a formula, commonly based on earnings, service, and an accrual rate. The member can estimate retirement income with greater certainty, subject to plan terms and funding rules. A defined contribution plan specifies contributions to an account; the eventual retirement income depends on contributions, investment returns, fees, annuity rates or withdrawal decisions, and longevity. Option A reverses the distinction. Option C is inaccurate because defined benefit plans are employer-sponsored arrangements with plan governance and funding obligations. Option D is wrong because defined contribution members bear significant investment and longevity risk unless they later purchase an annuity or otherwise transfer risk. For planning purposes, the distinction affects retirement projections, RRSP room through pension adjustments, asset allocation, risk capacity, and income sustainability. A planner must not treat all pensions alike; the type of pension determines both certainty of income and the risks remaining with the client. References/topics: defined benefit plans, defined contribution plans, pension risk, retirement projections.
NEW QUESTION # 73
During the discovery process, Greyson and Jacob's financial planner identifies that the couple wants to protect their family from unexpected health events and premature death. Their financial planner coordinates a meeting with an insurance agent for the next steps. What should the insurance agent recommend?
Answer: B
Explanation:
The insurance agent should first complete a capital needs analysis. Greyson and Jacob have broad protection objectives: premature death and unexpected health events. Product selection should follow quantification of the need, not precede it. A capital needs analysis estimates the amount of insurance required by considering debts, final expenses, survivor income, education funding, emergency reserves, existing assets, existing insurance, and the duration of dependency. Accidental insurance is too narrow because most premature deaths are not necessarily accidental. Permanent life insurance may or may not be appropriate depending on whether the need is temporary or permanent. Critical illness insurance may address part of the health-event risk, but it does not replace the need to quantify death and disability-related capital requirements. AFP risk management begins with need identification and measurement before product recommendation. Study Guide focus: capital needs analysis, life insurance planning, health-event risk, family protection, and product suitability. The analysis should normally be completed before deciding between term life, disability, critical illness, or permanent coverage.
NEW QUESTION # 74
......
You can try the free demo version of any AFP-Exam-1 exam dumps format before buying. For your satisfaction, PDFDumps gives you a free demo download facility. You can test the features and then place an order. So, these real and updated CSI AFP-Exam-1 Dumps are essential to pass the AFP-Exam-1 exam on the first try.
AFP-Exam-1 Updated Demo: https://www.pdfdumps.com/AFP-Exam-1-valid-exam.html
DOWNLOAD the newest PDFDumps AFP-Exam-1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1DMa_kza4lfWhLkcPrWp_GAIwUalbAETC