Our experts make these demos very clearly to demonstrate the content in our AFP-Exam-1 torrent prep. For those customers who are not acquainted with our products, these demos can help you familiarize yourself with what our materials contain and they will give you a frank appraisal of our official AFP-Exam-1 Exam Questions. All wordings cannot describe the procession of our products, but if you get them and after checking the content, you will be determined to place order. What are you waiting for?
| Section | Objectives |
|---|---|
| Topic 1: Investment Planning | - Investment products and risk-return profiles - Asset allocation and portfolio basics |
| Topic 2: Financial Planning Foundations | - Ethics and professional standards in financial advising - Financial planning process and client relationship management |
| Topic 3: Retirement Planning | - Retirement savings vehicles and planning principles |
| Topic 4: Taxation Concepts | - Personal income tax principles - Tax-efficient investment strategies |
| Topic 5: Insurance and Risk Management | - Risk mitigation strategies in financial planning - Life and health insurance fundamentals |
>> AFP-Exam-1 Exam Questions <<
For candidates who are going to buying AFP-Exam-1 training materials online, you may pay more attention to the privacy protection. We respect the private information of you. If you choose us, we can ensure you that your personal information such as your name and email address will be protected well. Once the order finishes, your personal information will be concealed. Besides, AFP-Exam-1 Exam Materials contain both questions and answers, and it’s convenient for you to have a check of answers. We have online and offline chat service for AFP-Exam-1 exam materials, if you have any questions, you can have a conversation with them.
NEW QUESTION # 62
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: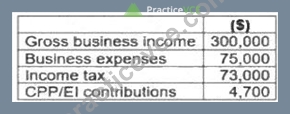
What is Terry's net business income?
Answer: B
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 63
A high-income parent gives $80,000 to a 12-year-old child to invest in a non-registered bond fund. The parent expects the child to report the annual interest income. What rule should the planner identify?
Answer: A
Explanation:
Canadian attribution rules are designed to prevent simple income splitting through transfers to related persons, including minor children. When a parent gifts property to a minor child, income such as interest and dividends from the transferred property may attribute back to the parent. The account name alone does not determine the tax result. Option A therefore misses the anti-avoidance rule. Option C is not practical unless the child has earned income and RRSP room, and it does not address attribution. Option D is too narrow; attribution can apply in several family-transfer situations. A planner should consider alternatives such as RESPs, Canada Child Benefit amounts actually belonging to the child, prescribed-rate loan structures with proper interest payment, or investing for capital gains where appropriate and legally supported. The advice must separate legal ownership, tax reporting, and beneficial source of funds. References/topics: income attribution, minor children, family tax planning, non-registered investments.
NEW QUESTION # 64
Rosa has just learned that her daughter Marissa, age 23, does not intend to return to university. She has been saving for her daughter's education since Marissa was 10 and is concerned there will be a significant tax liability. How should Rosa's financial planner advise her to utilize the funds when she redeems the RESP in order to offset the tax liability?
Answer: C
Explanation:
Rosa should transfer the RESP accumulated income payment, commonly referred to as growth, to her own RRSP if she has sufficient contribution room and the statutory conditions are met. When a beneficiary does not pursue qualifying post-secondary education, original contributions can usually be returned to the subscriber tax-free because they were made with after-tax dollars, while grants may have to be repaid. The taxable accumulated income is the problem. Transferring eligible AIP amounts to the subscriber's RRSP can defer or reduce the special tax that would otherwise apply. Depositing the growth or full balance into the daughter's RRSP is not the standard solution because Marissa may not have contribution room and the subscriber controls the RESP structure. Depositing the full balance into Rosa's RRSP is also inaccurate because contributions and grant amounts have different treatment. Study Guide focus: RESP withdrawals, accumulated income payments, RRSP rollover, grant repayment, and education planning.
NEW QUESTION # 65
A client refuses to provide details about debt balances, tax returns, and monthly expenses but asks the planner to confirm whether retirement at age 55 is achievable. What should the planner do?
Answer: D
Explanation:
The quality of a financial plan depends on the completeness and accuracy of client information. Debt levels, tax position, spending patterns, and cash flow capacity directly affect retirement feasibility. A planner may provide limited analysis when information is missing, but the limitation must be clearly explained and documented. Option A is professionally weak because generic assumptions can create false confidence.
Option B narrows the engagement improperly; investment recommendations cannot be separated from cash flow, tax, and debt constraints. Option D is unacceptable because undisclosed estimates can mislead the client and undermine the planning record. The correct professional response is to explain why the information is needed, request supporting documents, identify the limitations if the client still refuses, and avoid presenting unsupported conclusions as definitive. If the missing data is material, the planner may need to decline to provide a retirement feasibility opinion. References/topics: client discovery, data reliability, scope limitations, documentation.
NEW QUESTION # 66
The Andersons, a young couple, meet with their financial planner to review estate-planning opportunities.
They recently had a third child and are looking for the most cost-effective strategy to put in place during their working years to increase their estate value and reduce the tax burden at death for the benefit of their children.
What should the financial planner recommend?
Answer: D
Explanation:
A term survivorship life insurance policy is the most cost-effective fit for the Andersons' objective. They are a young working couple with children and want to increase estate value and reduce the tax burden at death for the benefit of the children. Survivorship coverage pays on the second death, which is when final estate transfer costs and taxes commonly become due for the next generation. Term coverage keeps the premium lower during the working years compared with permanent insurance. Naming the estate as beneficiary of registered plans can increase probate exposure and does not reduce tax. Permanent individual policies may be useful for lifetime estate liquidity, but they are usually more expensive than required for a cost-sensitive young family. A joint savings account does not create immediate estate liquidity if both parents die early.
Study Guide focus: survivorship insurance, estate liquidity, family protection, term insurance, and cost- effective risk management. The policy should be coordinated with wills, guardianship arrangements, registered plan beneficiaries, and expected final tax exposure.
NEW QUESTION # 67
......
This time set your mind at rest with the help of our AFP-Exam-1 guide quiz. You are free from any loss but focus on your success of the exam firmly this time. If you choose our nearly perfect AFP-Exam-1practice materials with high quality and accuracy, our AFP-Exam-1 Training Questions can enhance the prospects of victory. Choosing our AFP-Exam-1 learning prep is the most useful way to improve your grade and chance to pass the exam.
AFP-Exam-1 Trustworthy Exam Torrent: https://www.practicevce.com/CSI/AFP-Exam-1-practice-exam-dumps.html