We have technicians to check the website every day, and therefore if you choose us, you can enjoy a safe online shopping environment. In addition, AFP-Exam-1 exam materials are compiled and verified by professional specialists, and therefore the questions and answers are valid and correct. AFP-Exam-1 learning materials cover most of knowledge points for the exam, and you can master them as well as improve your professional ability in the process of learning. You can receive the download link and password within ten minutes after paying for AFP-Exam-1 Exam Dumps, if you don’t receive, you can contact us, and we will solve this problem for you.
| Section | Objectives |
|---|---|
| Topic 1: Insurance and Risk Management | - Risk mitigation strategies in financial planning - Life and health insurance fundamentals |
| Topic 2: Financial Planning Foundations | - Financial planning process and client relationship management - Ethics and professional standards in financial advising |
| Topic 3: Retirement Planning | - Retirement savings vehicles and planning principles |
| Topic 4: Taxation Concepts | - Tax-efficient investment strategies - Personal income tax principles |
| Topic 5: Investment Planning | - Asset allocation and portfolio basics - Investment products and risk-return profiles |
>> AFP-Exam-1 Reliable Test Answers <<
Our company is a professional certificate exam materials provider, we have occupied in the field for years, and we also famous for providing high-quality exam dumps. AFP-Exam-1 training materials have the questions and answers, and it will be convenient for you to check your answer. In addition, the pass rate for AFP-Exam-1 Exam Braindumps is 98.75%, and we can guarantee you pass the exam just one time. If you fail to pass the exam, we will refund your money. We also offer you free update for one year after purchasing, and the update version for AFP-Exam-1 training materials will be sent to you automatically.
NEW QUESTION # 78
Which statement best distinguishes a defined benefit pension plan from a defined contribution pension plan?
Answer: B
Explanation:
A defined benefit pension plan promises a retirement benefit determined by a formula, commonly based on earnings, service, and an accrual rate. The member can estimate retirement income with greater certainty, subject to plan terms and funding rules. A defined contribution plan specifies contributions to an account; the eventual retirement income depends on contributions, investment returns, fees, annuity rates or withdrawal decisions, and longevity. Option A reverses the distinction. Option C is inaccurate because defined benefit plans are employer-sponsored arrangements with plan governance and funding obligations. Option D is wrong because defined contribution members bear significant investment and longevity risk unless they later purchase an annuity or otherwise transfer risk. For planning purposes, the distinction affects retirement projections, RRSP room through pension adjustments, asset allocation, risk capacity, and income sustainability. A planner must not treat all pensions alike; the type of pension determines both certainty of income and the risks remaining with the client. References/topics: defined benefit plans, defined contribution plans, pension risk, retirement projections.
NEW QUESTION # 79
A client wants to increase net worth by identifying spending reductions and increasing monthly surplus.
Which document is most useful for this purpose?
Answer: D
Explanation:
Expense control is a cash flow problem. A net worth statement shows assets, liabilities, and net worth at a point in time, but it does not explain where monthly income is going. A current cash flow statement identifies inflows and outflows, while a budget converts that information into a forward-looking spending and savings plan. Option A is incomplete because the balance sheet can show that debt exists but not which behaviours are creating or reducing surplus. Option C relates to estate transfer, not spending control. Option D governs investment objectives and constraints; it does not normally capture household expense categories. To increase net worth, the planner must connect the income statement and balance sheet: reduce unnecessary outflows, direct surplus to debt repayment or savings, and measure progress through updated net worth statements. The practical planning sequence is diagnose cash flow, set a budget, automate surplus allocation, and review outcomes. References/topics: cash flow statement, budgeting, net worth improvement, expense management.
NEW QUESTION # 80
A financial planner, Rachel, is preparing to recommend a discretionary portfolio manager to her client. The portfolio manager is owned by Rachel's former employer, and Rachel receives no referral fee. However, the former employer regularly sends new clients to Rachel's practice. What should Rachel do before making the recommendation?
Answer: D
Explanation:
Course-guide reasoning starts with the conflict, not the commission. A conflict exists when a planner's judgment could reasonably be influenced by a relationship, incentive, expectation, or business arrangement.
Rachel's former employer may not pay her directly, but the reciprocal referral pattern creates a benefit that could affect, or appear to affect, objectivity. Professional conduct requires timely disclosure in plain language before the client acts on the recommendation. Disclosure should explain the relationship, the nature of the benefit, and how Rachel will continue to act in the client's interest. Option A is too narrow because conflicts are not limited to cash compensation. Option C is unnecessarily defensive; a conflicted recommendation may still be made if it is suitable and properly managed. Option D does not cure the conflict because acknowledging investment risk is different from understanding adviser bias. The defensible action is written disclosure, suitability analysis, and clear documentation. References/topics: conflicts of interest, disclosure obligations, objectivity, professional conduct.
NEW QUESTION # 81
Edward is risk averse and has limited investment knowledge. He will only purchase 100% guaranteed products insured by the CDIC. Edward is meeting with his financial planner, Marissa, for the third time this year about rates, and starts the meeting by criticizing her employer for paying such low returns on GICs.
Edward says he is considering taking his business elsewhere. How should Marissa respond to Edward's comments?
Answer: C
Explanation:
Marissa should respond with empathy and accuracy. Edward is risk averse, has limited investment knowledge, and will only purchase CDIC-insured guaranteed products. The correct response is to acknowledge his frustration, explain that the displayed rates are the best she can offer, and allow him to compare alternatives without pressure. Matching competitor rates may be outside her authority and could misrepresent the firm's pricing. Telling him to increase risk tolerance to obtain a better return ignores his stated constraints and may lead to unsuitable advice. Claiming her rate is the highest in the market would be inappropriate unless she can substantiate it, and even then the statement may become stale quickly. In AFP client management, the planner preserves trust by respecting the client's risk profile, communicating honestly, and avoiding product pressure. Study Guide focus: client communication, risk tolerance, guaranteed products, suitability, and relationship management. This response protects suitability because Edward's product universe is defined by capital guarantee and deposit insurance.
NEW QUESTION # 82
Janet's non-registered account holds the funds listed in the following table: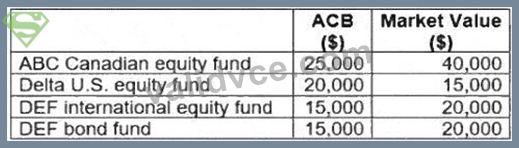
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: B
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 83
......
If you are going to buy AFP-Exam-1 learning materials online, and concern the privacy protection, you can choose us. We respect private information of you. If you choose us, your private information will be protected well. Once the order finishes, your personal information such as your name and email address will be concealed. Moreover, AFP-Exam-1 Exam Materials contain both questions and answers, and it’s convenient for you to have a check after practicing. We offer you free update for one year for AFP-Exam-1 training materials, and the update version will be sent to your email address automatically.
New AFP-Exam-1 Test Pass4sure: https://www.validvce.com/AFP-Exam-1-exam-collection.html