2026 Latest SurePassExams LLQP PDF Dumps and LLQP Exam Engine Free Share: https://drive.google.com/open?id=1DSbvekBZJgD4L2KuhjW-zvYR5BumaqGc
There is no doubt that our Life License Qualification Program (LLQP) guide torrent has a higher pass rate than other study materials. We deeply know that the high pass rate is so important for all people, so we have been trying our best to improve our pass rate all the time. Now our pass rate has reached 99 percent. If you choose our LLQP study torrent as your study tool and learn it carefully, you will find that it will be very soon for you to get the Life License Qualification Program (LLQP) certification in a short time. Do not hesitate and buy our LLQP test torrent, it will be very helpful for you.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
If you choose our LLQP exam question for related learning and training, the system will automatically record your actions and analyze your learning effects. Many people want to get a LLQP certification, but they worry about their ability. So please do not hesitate and join our study. Our LLQP Exam Question will help you to get rid of your worries and help you achieve your wishes. So you will have more opportunities than others and get more confidence. Our LLQP quiz guide is based on the actual situation of the customer.
NEW QUESTION # 27
Jean, who is in business, would like to understand why his segregated funds, which resemble mutual funds, allow this type of asset to be sheltered from creditors. How should Patrice, his financial security advisor, answer?
Answer: A
Explanation:
Comprehensive and Detailed In-Depth Explanation: Segregated funds are investment products offered by life insurers, combining insurance and investment features. Under Quebec's Civil Code (Article 2457), proceeds from life insurance contracts, including annuities, are exempt from seizure if the beneficiary is the policyholder's spouse, ascendant, descendant, or an irrevocable beneficiary. Segregated funds qualify for this protection because they are structured as annuity contracts, distinguishing them from mutual funds. Option A correctly identifies this legal protection tied to beneficiary designation. Option B misattributes the protection to the AMF Guideline, which regulates segregated funds but does not grant seizure exemption-that stems from the Civil Code. Option C overgeneralizes, as not all insurance products are exempt (e.g., recent contributions may be contested under Article 2459). Option D focuses on the guarantee, which is a feature of segregated funds, but the creditor protection hinges on the insurance contract status and beneficiary rules, not the guarantee alone. The Ethics manual requires advisors to explain legal protections accurately.
References: Civil Code of Quebec, Articles 2457-2459; Ethics and Professional Practice (Civil Law) Manual, Section on Segregated Funds and Creditor Protection.
NEW QUESTION # 28
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
Answer: B
Explanation:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence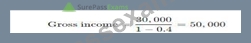
Calculate Required Capital for Income Replacement:
Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence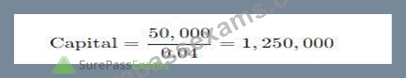
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
NEW QUESTION # 29
(Gregory and Vanessa married at an early age and had three children, who are now in their forties:
Eve, Rick and Max. When the couple retired five years ago, they purchased a joint life annuity. They also had a will drawn up naming the three children as equal beneficiaries of their estate. The will specifies that Eve will act as executor of the estate.
Last week, Gregory and Vanessa both died in a car accident.
Who could make a death claim as regards the annuity?)
Answer: C
Explanation:
Since Gregory and Vanessa bought ajoint life annuity without mention of a guarantee period, the annuity wouldcease payments upon the death of the second annuitant. Therefore,no death claimcan be made on the annuity.
Exact Extract:
"In a joint life annuity with no guarantee period, payments stop upon the death of the second annuitant. No death benefit is payable." (Reference:Segfunds-E313-2020-12-7ED, Chapter 3.2.2.2 Joint Life Contract#53:3 Segfunds-E313-2020-12-
7ED.pdf**)
NEW QUESTION # 30
Eric is an architect who owns his own firm. He employs three staff and is in his fifth year of operation. While recently meeting with his insurance agent for an annual review of his coverage, he mentioned to the agent that he had recently purchased a new printing system and has a sizeable loan on it. In the event of disability, what type of insurance coverage could the agent suggest to ensure the loan payments are made?
Answer: D
Explanation:
Comprehensive and Detailed Explanation:
Business loan protection disability insurance covers loan payments if the owner is disabled, directly addressing Eric's need (Chapter 5:Insurance to Protect Businesses).
Option A: Incorrect; protects business operations.
Option B: Incorrect; covers overhead, not loans.
Option C: Incorrect; for buy-sell agreements.
Option D: Correct; targets loan payments.
Reference: LLQP Accident and Sickness Insurance Manual, Chapter 5:Insurance to Protect Businesses.
NEW QUESTION # 31
Jeremy, aged 35 and Emily, aged 40, are common law spouses and have 3 children, Jack, Maddie, and Grace.
They are reviewing their life insurance coverage with Mark, a local life insurance agent, to ensure they have adequate coverage. Currently, Jeremy and Emily both have term life insurance in the amount of $200,000.
Jeremy recently inherited a family cottage valued at $400,000 (ACB of $200,000), which him and Emily hope to pass on to their children one day. Mark informs Jeremy & Emily of the potential tax liability of passing the cottage to their children and advises them that they should consider purchasing additional life insurance.
How much life insurance should they purchase to cover the future tax liability of the children taking into account a tax rate of 50%?
Answer: D
Explanation:
Comprehensive and Detailed Explanation From Exact Extract:
Capital gains = FMV $400,000 - ACB $200,000 = $200,000.
Taxable portion = 50% × $200,000 = $100,000.
At a 50% tax rate, the total tax liability = $50,000.
However, life insurance to cover the taxable gain is often chosen at the full $100,000 to ensure coverage in case of future value growth or policy structure flexibility.
Reference: Insurance Study Guides Chinese.pdf, Estate Planning - Capital Gains and Tax Liability Coverage
NEW QUESTION # 32
......
All praise and high values lead us to higher standard of LLQP practice engine. So our work ethic is strongly emphasized on your interests which profess high regard for interests of LLQP exam candidates. Our LLQP practice materials capture the essence of professional knowledge and lead you to desirable results effortlessly. Our LLQP Practice Engine has bountiful content that can fulfill your aims and our LLQP learning materials give you higher chance to pass your exam as the pass rate is as high as 99% to 100%.
LLQP Real Dumps Free: https://www.surepassexams.com/LLQP-exam-bootcamp.html
BTW, DOWNLOAD part of SurePassExams LLQP dumps from Cloud Storage: https://drive.google.com/open?id=1DSbvekBZJgD4L2KuhjW-zvYR5BumaqGc