There are many merits of our product on many aspects and we can guarantee the quality of our PF1 practice engine. Firstly, our experienced expert team compile them elaborately based on the real exam. Secondly, both the language and the content of our PF1 study materials are simple. The content emphasizes the focus and seizes the key to use refined PF1 Questions and answers to let the learners master the most important information by using the least practic. Three, we provide varied functions to help the learners learn our study materials and prepare for the exam.
| Section | Weight | Objectives |
|---|---|---|
| Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Individual Pay Calculations | 40% | - Regular earnings
|
| Communication and Compliance | 10% | - Stakeholder communication
|
| Termination and Special Payments | 30% | - Leaves and absences
|
We provide you with two kinds of consulting channels if you are confused about some questions on our PF1 study materials. You can email us or contact our online customer service. We will reply you as soon as possible. You are free to ask questions about PF1 training prep at any time since that we are working 24/7 online. Our staff is really very patient and friendly. They are waiting to give you the most professional suggestions on our PF1 exam questions.
NEW QUESTION # 63
Evangeline earns $1,075.00 weekly plus $154.00 in overtime. Calculate Evangeline's Quebec Parental Insurance Plan (QPIP) premium.
Answer:
Explanation:
$5.28 (employee QPIP premium for the week)
Explanation:
QPIP premiums are calculated on an employee's insurable earnings in Quebec (up to the annual maximum insurable earnings). For 2026, Revenu Quebec shows the employee QPIP premium rate is 0.430% (0.00430) and the maximum insurable earnings are $103,000.
Step 1: Determine Evangeline's weekly insurable earnings (assuming all earnings are QPIP-insurable and the annual maximum will not be exceeded, as the question implies):
Regular earnings $1,075.00 + overtime $154.00 = $1,229.00.
Step 2: Apply the employee QPIP rate:
$1,229.00 × 0.430% = $1,229.00 × 0.00430 = $5.2847.
Step 3: Round to cents (standard payroll practice): $5.28.
Payroll would deduct $5.28 from Evangeline's pay for QPIP for that week and remit it along with other source deductions as required. The deduction continues until the employee reaches the annual QPIP maximum premium (based on the annual insurable earnings limit).
NEW QUESTION # 64
What is piecework?
Answer: A
Explanation:
Piecework (also called piece-rate pay) is a pay method where an employee's earnings are determined by output-they are paid a set amount per unit produced or completed, rather than by hours worked or a fixed salary. This aligns directly with option C. A time-based hourly/daily wage (option A) is a different earnings method, and a fixed pay-per-period arrangement (option B) describes salary. Therefore, "all of the above" is incorrect because these are three distinct compensation structures.
In payroll calculations, piecework earnings are typically calculated as: piece rate × number of units produced in the pay period. Employers still have to ensure compliance with employment standards, such as minimum wage and overtime rules, even where piecework is used. A Canadian payroll educational reference defines piecework as payment for each unit produced "regardless of the amount of time taken."
NEW QUESTION # 65
An interruption of earnings occurs when there is a period of how many days with no insurable earnings?
Answer: A
Explanation:
Service Canada's ROE Guide defines an interruption of earnings under the "7-day rule." It occurs when an employee has had, or is expected to have, 7 consecutive calendar days with no work and no insurable earnings from the employer.
This is specifically calendar days, not business days. That means weekends and holidays count in the seven- day sequence. The rule commonly applies when employees quit, are laid off, or are terminated, and it helps determine when an employer must issue an ROE (subject to certain listed exceptions and special situations, such as some employees with non-standard work patterns or employees mainly paid by commission).
From a payroll operations standpoint, correctly identifying the interruption of earnings is critical because it triggers ROE deadlines and affects the employee's ability to access EI benefits without delay. So the correct answer is Seven calendar days (option D).
NEW QUESTION # 66
Select the correct order of priority for withholding payroll deductions from an employee's earnings.
Answer: B
Explanation:
Payroll deductions are typically applied in a priority order to ensure the employer meets mandatory legal obligations first and avoids creating liability. Standard Canadian payroll training materials commonly present five categories withheld in this order: (1) statutory deductions, (2) legal deductions, (3) union deductions, (4) company-compulsory deductions, and (5) voluntary deductions.
Statutory deductions (CPP/QPP, EI, income tax, and where applicable NWT/Nunavut payroll tax) have top priority because employers are legally required to deduct and remit them.
Legal deductions (such as CRA requirements to pay/garnishments) are next because they are enforced by law and can create employer liability if not followed.
Union deductions follow where required by a collective agreement.
Company-compulsory deductions (for example, required benefit premiums) come after those.
Voluntary deductions (charity, savings plans, etc.) are last and only taken if funds remain.
Therefore, option D is the correct order.
NEW QUESTION # 67
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
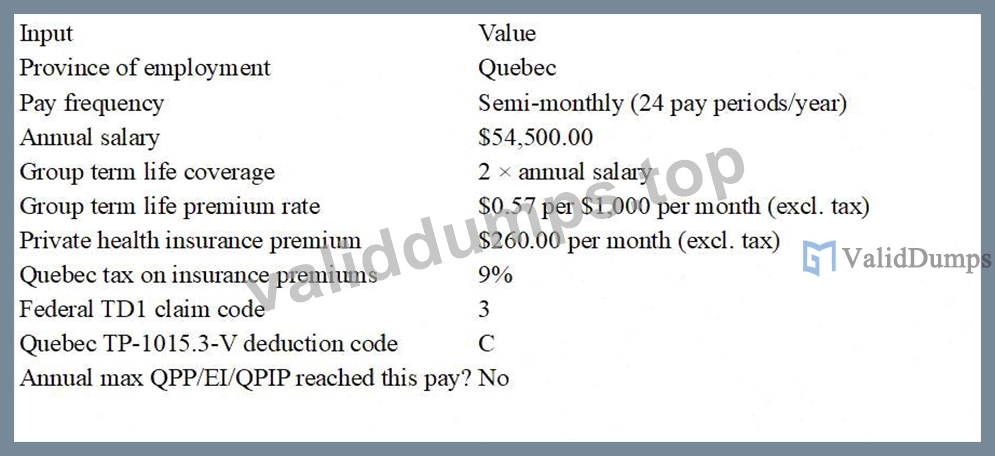
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases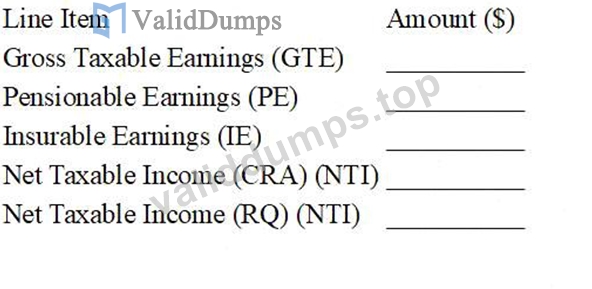
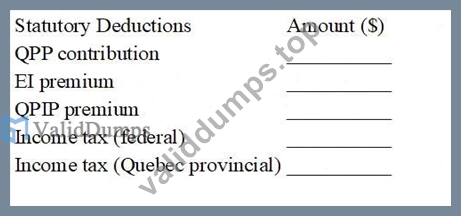
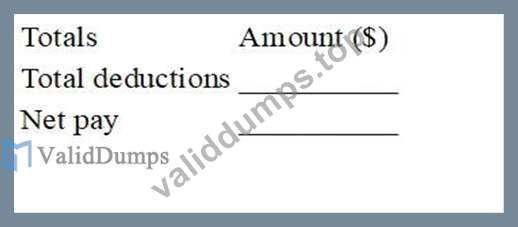
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 68
......
Our technician will check the update of PF1 exam questions every day, and we can guarantee that you can get a free update service from the date of purchase. Once you have any questions and doubts about the PF1 exam questions we will provide you with our customer service before or after the sale, you can contact us if you have question or doubt about our PF1 Exam Materials and the professional personnel can help you solve your issue about using PF1 study materials.
Valid Braindumps PF1 Questions: https://www.validdumps.top/PF1-exam-torrent.html