What's more, part of that Prep4sureExam IIA-CIA-Part3 dumps now are free: https://drive.google.com/open?id=1JN05xjSGTi2xTlXWe9p8A9TUq72mGB9J
The most advantage of our IIA-CIA-Part3 exam torrent is to help you save time. It is known to us that time is very important for you. As the saying goes, an inch of time is an inch of gold; time is money. If time be of all things the most precious, wasting of time must be the greatest prodigality. We believe that you will not want to waste your time, and you must want to pass your IIA-CIA-Part3 Exam in a short time, so it is necessary for you to choose our IIA-CIA-Part3 prep torrent as your study tool. If you use our products, you will just need to spend 20-30 hours to take your exam.
IIA-CIA-Part3 exam is a certification exam offered by the Institute of Internal Auditors (IIA). It is a part of the Certified Internal Auditor (CIA) certification program that is designed to enhance the knowledge and skills of internal auditors. The IIA-CIA-Part3 Exam focuses on business knowledge for internal auditing and is meant for individuals who want to improve their understanding of business operations and management.
>> IIA-CIA-Part3 Latest Torrent <<
Close to 100% passing rate is the best gift that our customers give us. We also hope our IIA-CIA-Part3 exam materials can help more ambitious people pass IIA-CIA-Part3 exam. Our professional team checks the update of every exam materials every day, so please rest assured that the IIA-CIA-Part3 Exam software you are using must contain the latest and most information.
IIA-CIA-Part3 (Business Knowledge for Internal Auditing) Certification Exam is a globally recognized certification program designed for internal auditors who want to enhance their knowledge of business operations and gain a deeper understanding of the internal audit process. IIA-CIA-Part3 exam covers a range of topics, including financial management, strategic planning, risk management, and corporate governance. It is an essential certification for professionals who wish to advance their careers in internal auditing.
IIA-CIA-Part3 (Business Knowledge for Internal Auditing) Exam is an essential certification exam for internal auditors seeking to enhance their knowledge and skills in the field of business. IIA-CIA-Part3 Exam covers a broad range of business topics and is designed to test the candidate's ability to apply business concepts and principles to internal audit activities. Internal Audit Function certification is recognized globally and is highly valued by employers, making it an excellent way for internal auditors to advance their careers.
NEW QUESTION # 60
The following transactions and events occurred during the year: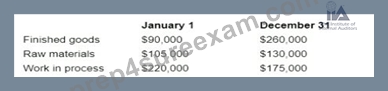
- $300,000 of raw materials were purchased, of which $20,000 were returned because of defects
- $600,000 of direct labor costs were incurred.
- S750.000 of manufacturing overhead costs were incurred.
What is the organization's cost of goods sold for the year?
Answer: D
NEW QUESTION # 61
The carrying amount cost minus accumulated depreciation) of property plant, and equipment disposed of in Year 2 was:
Answer: A
Explanation:
The cost of PPE disposed of is US $20,000$295,000 beginning PPE + 65,000 acquisitions - $340,000 ending PPE). The accumulated depreciation + $30,000 depreciation expense - $119,000 ending encountered depreciation. Thus, the carrying amount of PPE disposed of is US $7,000'.I I Or II i depreciation).
Balance sheets on December 31, Year 1, and December 31, Year 2, are presented below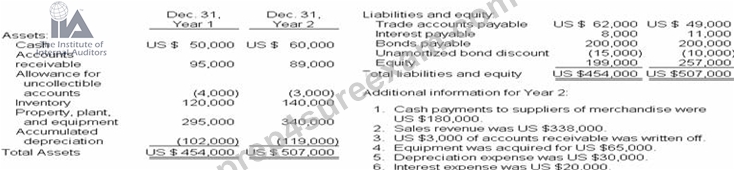
NEW QUESTION # 62
On January 2, Year 1, Kine Co. granted Morgan, its preside -I t. share options to buy 1.000 shares of Kine's US $10 per ordinary stock. The options call for a price of US$20 per share and are exercisable for 3 years following the grant date. Morgan exercised the options on December 31, Year 1. The market price of the shares was US $50 on January 2, Year 1, and US $70 on the following for December 31. The market price of the shares is followed because the fair value of the option is not reliable measurable, by what net amount should equity increased as a result of the grant and exercise of the options?
Answer: C
Explanation:
The measurements January 2, Year 'I_ At that date, the intrinsic value of the options is US $30.000 [1,000 shares$50 market price -$20 option price)]. This US $30,000 will be recorded as both compensation expense and options outstanding. The net effect on equity is 0. When the options are exercised the US $20,0001.000 shares $20 option price)]. This US $30,000 will be recorded as both compensation expense and options outstanding will be allocated to share capital as US $30,000 of options are exercised, the US $ 20,0001,000 shares x $20 exercise price) cash received and the US $30,000 of options are exercised price) cash received and the US $30,000 of options outstanding will be allocated to share capital as US $10,000 ordinary stock and US $40,000 additional paid in capital. The net effect on equity will be a US $20,000 increase.
NEW QUESTION # 63
On January 1, Year 1, International Entity entered into an equity-settled share-based payment transaction with its senior executives. This award of 1,000 share options has a 4year vesting period. The market prices of the options and the related shares on the grant date are US $20 and US $80, respectively. The exercise price is US $85. Assuming that the vesting conditions were not met for 100 of the options because of unexpected events in Year 4, the entry to debit option expense at:
Answer: B
Explanation:
The fair value of each share option is determined at the measurement date, which is the grant date for transactions with employees and others providing 1 similar services thus, the fair value of each share option was set at its market price of US $20 on January 1 Year 1 The periodic expense varies only with the expected number of equity instruments expected to vest. Because the events causing 100 options not b. vest occurred unexpectedly in Year 4, the entity presumably at each balance sheet date for the first 3 years of the vesting period that all options would vest. Total expected expense was thereof US $20,000, and the proportional expense recognize each of the first 3 years was US $5,000 [(1,000 options x $20) / 4 years.
NEW QUESTION # 64
Total quality management in a manufacturing environment is best exemplified by:
Answer: A
Explanation:
Total quality management emphasizes quality as a basic organizational function. TOM is the continuous pursuit of quality in every aspect of organizational activities. One of the basic tenets of TOM is doing it right the first time. Thus, errors should be caught and corrected at the source, and quality should be built in designed in) from the start.
NEW QUESTION # 65
......
Latest IIA-CIA-Part3 Test Sample: https://www.prep4sureexam.com/IIA-CIA-Part3-dumps-torrent.html
P.S. Free & New IIA-CIA-Part3 dumps are available on Google Drive shared by Prep4sureExam: https://drive.google.com/open?id=1JN05xjSGTi2xTlXWe9p8A9TUq72mGB9J