The clients can use the shortest time to prepare the exam and the learning only costs 20-30 hours. The questions and answers of our AFP-Exam-1 study materials are refined and have simplified the most important information so as to let the clients use little time to learn. The clients only need to spare 1-2 hours to learn our AFP-Exam-1 Study Materials each day or learn them in the weekends. Commonly speaking, people like the in-service staff or the students are busy and don’t have enough time to prepare the exam. Learning our AFP-Exam-1 study materials can help them save the time and focus their attentions on their major things.
| Section | Weight | Objectives |
|---|---|---|
| Technical Competencies | 84% | - Estate Planning - Asset and Liability Management - Investment Planning - Retirement Planning - Risk Management and Insurance - Tax Planning |
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
>> AFP-Exam-1 Testking Exam Questions <<
With the rapid development of IT technology, the questions in the IT certification exam are also changing. Therefore, TorrentExam also keeps updating test questions and answers. And if you purchase TorrentExam CSI AFP-Exam-1 Practice Test materials, we will provide you with free updates for a year. As long as the questions updates, TorrentExam will immediately send the latest questions and answers to you which guarantees that you can get the latest materials at any time. TorrentExam can not only help you pass the test, but also help you learn the latest knowledge. Never pass up a good chance to have the substantial materials.
NEW QUESTION # 27
Owen and Lina are looking to purchase a home in the next few months. Owen is the primary income earner for the family. His credit history is weak with several recently paid collections Lina has a perfect credit record but limited income and irregular employment. What will their financial planner advise them about the impact their credit ratings will have on their ability to secure a mortgage?
Answer: A
Explanation:
The weak credit history of the primary income earner is the central mortgage issue. Lenders assess income, debt service ratios, down payment, property, and creditworthiness. Owen supplies the main income needed to qualify, but his recent collections create underwriting risk even if they have been paid. Lina's strong credit record helps the household profile, but it does not fully offset limited income and irregular employment. Paid collections may improve the application compared with unpaid collections, yet they do not automatically qualify the borrowers. Lina's low income alone may not prevent approval if Owen qualifies, but his credit weakness may. The planner should advise them to review the credit bureau, correct errors, reduce revolving debt, avoid new inquiries, and allow time for stronger repayment history before applying. Study Guide focus:
mortgage qualification, credit history, debt service capacity, borrower risk, and liability management. The advice should be delivered before a formal application so avoidable bureau damage and failed underwriting can be reduced.
NEW QUESTION # 28
Daniel, age 55, plans to continue working for AMG Telecommunications Corporation until he retires at age
60. The company has a defined contribution plan and Daniel is looking for the best option that will allow him to receive the highest guaranteed income throughout his retirement. He is not concerned about leaving an estate and feels that interest rates will be at high levels as he nears retirement. What planning strategy should Daniel's financial planner recommend he implement to achieve this objective?
Answer: A
Explanation:
A life annuity is the appropriate recommendation because Daniel wants the highest guaranteed lifetime income, is not concerned about leaving an estate, and expects interest rates to be high near retirement. An annuity transfers longevity risk and investment risk to the insurer in exchange for predictable payments.
Higher interest rates at annuity purchase generally support higher annuity income, all else equal. A principal- protected note is not a guaranteed lifetime income product and can contain complexity and market-linked return risk. A locked-in RRSP with laddered GICs preserves capital but does not guarantee income for life unless annuitized later. A LIRA invested in a target-date fund remains market-exposed and does not provide the highest guaranteed lifetime income. The planner should discuss annuity type, guarantee period, indexing, joint-life options, and loss of liquidity before implementation. Study Guide focus: defined contribution pensions, annuitization, longevity risk, guaranteed income, and retirement product selection. The recommendation must still consider whether Daniel needs indexing because fixed annuity income can lose purchasing power.
NEW QUESTION # 29
Leena and Harry are married and hold RRSPs with a value exceeding $500,000. They are concerned about their final tax liability and want to cover the taxes after they have both died. What would their financial planner recommend them to implement in order for the couple to achieve the objective?
Answer: C
Explanation:
A joint last-to-die permanent life insurance policy is designed for a tax liability that arises after both spouses have died. Leena and Harry are concerned about the final tax exposure on large RRSP balances. If one spouse dies first and the surviving spouse is the beneficiary or successor annuitant, RRSP/RRIF amounts may generally roll to the survivor on a tax-deferred basis. The larger tax problem usually appears on the second death, when no spouse remains for rollover and the registered assets are included in income. Last-to-die coverage pays at that point and can provide estate liquidity for taxes without forcing asset sales. A testamentary trust does not itself fund the tax bill. Updating beneficiaries to each other helps deferral but not the final liability. An inter vivos trust cannot simply receive RRSP assets without tax consequences. Study Guide focus: RRSP/RRIF death taxation, spousal rollover, permanent insurance, estate liquidity, and last-to- die planning.
NEW QUESTION # 30
A client sends an email alleging that a mutual fund recommendation was unsuitable because the fund declined sharply after purchase. The client asks for compensation. What is the financial planner's first professional obligation?
Answer: B
Explanation:
The issue is complaint governance. A written allegation of unsuitable advice and a request for compensation must be treated as a complaint, even if the planner believes the recommendation was defensible. The planner should preserve the communication, record the relevant facts, notify the appropriate supervisory channel, and follow the firm's complaint process. The file should contain the original KYC information, risk-tolerance evidence, fund recommendation rationale, disclosure documents, trade record, and subsequent communications. Option A is improper because compensation should not be promised before the complaint is reviewed under firm policy. Option B is dismissive; market loss alone may not prove unsuitability, but the complaint still requires a formal response. Option C is unacceptable and would create a serious recordkeeping and conduct breach. A professional process protects both parties: the client receives a fair review, and the planner demonstrates procedural discipline, supervision, and documentation. References/topics: complaint handling, suitability review, recordkeeping, regulatory compliance.
NEW QUESTION # 31
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: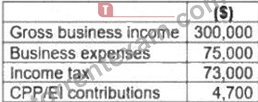
What is Terry's net business income?
Answer: C
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 32
......
The Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) PDF dumps are suitable for smartphones, tablets, and laptops as well. So you can study actual Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) questions in PDF easily anywhere. TorrentExam updates Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) PDF dumps timely as per adjustments in the content of the actual CSI AFP-Exam-1 exam. In the Desktop AFP-Exam-1 practice exam software version of CSI AFP-Exam-1 Practice Test is updated and real. The software is useable on Windows-based computers and laptops. There is a demo of the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) practice exam which is totally free. Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) practice test is very customizable and you can adjust its time and number of questions.
AFP-Exam-1 Exam Sims: https://www.torrentexam.com/AFP-Exam-1-exam-latest-torrent.html