Ohne Zeitaufwand und Anstrengung die WGU Accounting-for-Decision-Makers Prüfung zu bestehen ist unmöglich, daher bemühen wir uns darum, Ihre Belastung der Vorbereitung auf WGU Accounting-for-Decision-Makers zu erleichtern. Standardisierte Simulierungsrüfung und die leicht zu verstehende Erläuterungen können Ihnen helfen, allmählich die Methode für WGU Accounting-for-Decision-Makers Prüfung zu beherrschen. Um mehr Stress von Ihnen zu beseitigen versprechen wir, falls Sie die Prüfung nicht bestehen, geben wir Ihnen volle Rückerstattung der WGU Accounting-for-Decision-Makers Prüfungsunterlagen nach der Überprüfung Ihres Zeugnisses. Zertpruefung ist vertrauenswüdig!
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Budgeting and Decision Making | 10–15% | - Relevant information for decision making
|
| Topic 2: Cost Systems | 20–25% | - Costing methods
|
| Topic 3: Controls and Regulations | 10–15% | - Internal control systems and principles
|
| Topic 4: Profit Planning | 10–15% | - Cost-volume-profit (CVP) analysis
|
| Topic 5: Financial Analysis | 45–50% | - Purpose and components of financial statements
|
>> Accounting-for-Decision-Makers Online Prüfungen <<
Die WGU Accounting-for-Decision-Makers Prüfungsfragen von Zertpruefung sind in Übereinstimmung mit dem neuesten Lehrplan und der echten WGU Accounting-for-Decision-Makers Zertifizierungsprüfung. Wir aktualisieren auch ständig unsere Schulungsunterlagen. Alle Produkte erhalten Sie mit einjährigen kostenlosen Updates. Sie können auch das Abozeit verlängern, so dass Sie mehr Zeit bekommen, um sich besser auf die Prüfung vorzubereiten. Wenn Sie zögert sind oder nicht dafür entscheiden können, ob Sie die WGU Accounting-for-Decision-Makers Schulungsunterlagen von Zertpruefung kaufen oder nicht. Dann können Sie die Demo umsonst auf der Zertpruefung website herunterladen. Wenn es Ihnen passt, dann gehen Sie zum Kaufen ohne Bereuung.
31. Frage
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.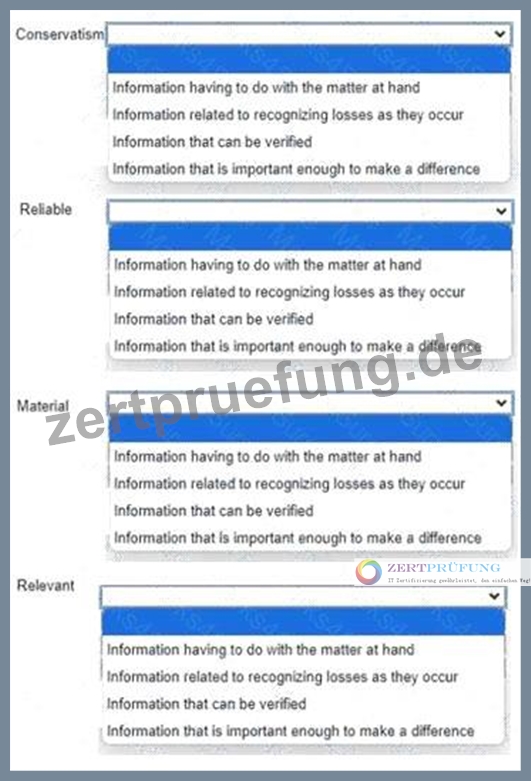
Antwort:
Begründung: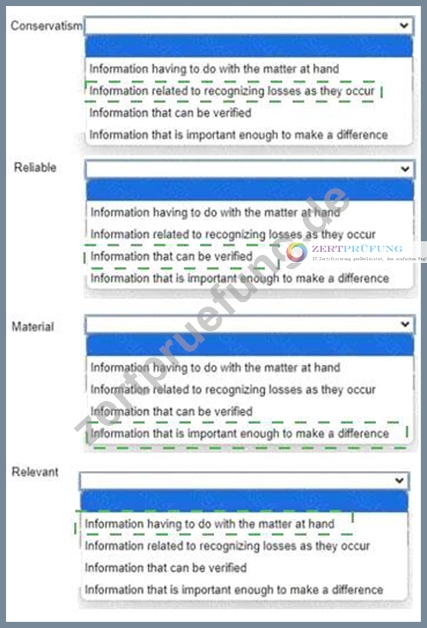
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
32. Frage
Which role do ethical standards have in management accounting?
Antwort: A
Begründung:
The correct answer is D . In management accounting, ethical standards are intended to guide behavior and help resolve ethical dilemmas that professionals may encounter in practice. The IMA Statement of Ethical Professional Practice explains that its principles and standards serve as a guide for ethical conduct in management accounting and include guidance for the resolution of ethical conflict .
Option A is incorrect because ethical standards cannot predict with certainty whether another person will behave ethically. Option B is incorrect because the standards do not guarantee that a management accountant will work only with perfectly ethical companies. Option C is also incorrect because no code can prevent all unethical behavior by everyone involved. Instead, the standards provide a framework based on competence, confidentiality, integrity, and credibility so the accountant can respond appropriately when ethical issues arise.
Therefore, the most accurate role of ethical standards in management accounting is to provide guidance for addressing and resolving ethical conflicts in a professional, structured manner. That makes Option D the correct answer.
33. Frage
Given the following information:
Pairs of shoes expected to be produced = 1,950,000
Pairs of shoes produced = 2,500,000
Overhead rate = $0.75
What is the amount of applied overhead?
Antwort: D
Begründung:
The correct answer is D. $1,875,000 . Applied overhead is calculated by multiplying the predetermined overhead rate by the actual amount of the allocation base used during production. OpenStax explains that a predetermined overhead rate is established in advance and then applied to production using the actual activity level.
The formula is:
Applied overhead = Overhead rate × Actual production
Using the figures provided:
Applied overhead = $0.75 × 2,500,000 = $1,875,000
So the total amount of overhead applied is $1,875,000 . The "expected to be produced" amount helps establish or understand the rate, but once the rate is given, applied overhead is based on the actual production achieved , not the estimated quantity.
Option C, $1,462,500 , would result from multiplying the rate by the expected production of 1,950,000, which is not what the question asks. The question specifically asks for the applied overhead, which uses actual activity. Therefore, with 2,500,000 pairs produced at $0.75 per pair , the correct applied overhead is
$1,875,000 , making Option D the correct answer.
34. Frage
Which ratio provides a measure of how well a company turns sales into profits?
Antwort: D
Begründung:
The correct answer is A. Return on sales . Return on sales, also called profit margin or net profit margin , measures how effectively a company converts sales revenue into net income. It is commonly calculated as Net income ÷ Sales . OpenStax explains that this ratio shows how much of each sales dollar remains as profit after all expenses, including taxes, have been deducted. A higher ratio generally indicates stronger profitability and better cost control relative to revenue.
Option B, return on costs , is not the standard ratio named in basic financial analysis for this purpose. Option C, return on expenses , is also not the conventional measure used in the ratio formulas you listed. Option D, return on profit , is not a recognized standard profitability ratio in introductory accounting frameworks.
Since the question asks specifically about how well a company turns sales into profits , the ratio that directly measures that relationship is return on sales . This ratio is widely used in financial statement analysis to compare operating performance across periods and across firms, especially within the same industry.
35. Frage
Which financial statement is used to determine a company's income and expenses for a specific period?
Antwort: C
Begründung:
The correct answer is D. Income statement . The income statement reports a company's revenues and expenses over a specific period of time and shows whether the company earned a profit or incurred a loss during that period. Standard accounting materials explain that the income statement summarizes revenue and expense activity and presents net income or net loss for the reporting period.
Option A, the balance sheet , is incorrect because it shows financial position at a particular date rather than performance over a period. Option B, the statement of retained earnings , explains changes in retained earnings, including the effects of net income and dividends, but it does not serve as the main report for listing revenues and expenses. Option C, the statement of cash flows , focuses on cash inflows and outflows from operating, investing, and financing activities rather than accrual-based income and expense measurement. In accounting, when the question asks which statement is used to determine income and expenses for a period, the income statement is the direct and correct answer. That is why Option D is the best answer.
36. Frage
......
Zertpruefung ist eine professionelle Webseite, die die neuesten Testaufgaben und Antworten von WGU Accounting-for-Decision-Makers Zertifizierungsprüfung bietet. Es ist sicherlich Ihre beste Wahl, mit unseren Lehrbüchern die WGU Accounting-for-Decision-Makers Prüfung vorzubereiten. Zertpruefung wird Ihnen helfen, in begrenzter Zeit die Accounting-for-Decision-Makers Prüfung so schnell wie möglich zu bestehen. Wenn es irgendein Qualitätsproblem von den Lehrbüchern gibt oder Wenn Sie die Accounting-for-Decision-Makers Prüfung nicht bestehen, versprechen wir Ihnen eine bedingungslose volle Rückerstattung.
Accounting-for-Decision-Makers Prüfungsaufgaben: https://www.zertpruefung.de/Accounting-for-Decision-Makers_exam.html