P.S. Free & New PF1 dumps are available on Google Drive shared by Exam4PDF: https://drive.google.com/open?id=1veJfyYx7BGZ2YZYJnfJUYneA8y3Hl0xm
National Payroll Institute PF1 training materials have won great success in the market. Tens of thousands of the candidates are learning on our PF1 practice engine. First of all, our National Payroll Institute PF1 study dumps cover all related tests about computers. It will be easy for you to find your prepared learning material. If you are suspicious of our PF1 Exam Questions, you can download the free demo from our official websites.
| Section | Objectives |
|---|---|
| Topic 1: Non-Regular Payments | - Special payroll payments
|
| Topic 2: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 3: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 4: Provincial Remittances | - Provincial payroll requirements
|
| Topic 5: Commission Payments | - Commission payroll processing
|
| Topic 6: Payroll Accounting | - Payroll accounting practices
|
| Topic 7: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 8: Termination of Employment | - Termination processing
|
| Topic 9: Record of Employment | - ROE processing
|
| Topic 10: New Employee Information | - Employee setup and documentation
|
| Topic 11: Workers’ Compensation | - Workers compensation administration
|
| Topic 12: Federal Remittances | - Government remittance obligations
|
| Topic 13: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
On one hand, our PF1 study questions can help you increase the efficiency of your work. In the capital market, you are more efficient and you are more favored. Entrepreneurs will definitely hire someone who can do more for him. On the other hand, our PF1 Exam Materials can help you pass the exam with 100% guarantee and obtain the certification. As we all know, an international PF1certificate will speak louder to prove your skills.
NEW QUESTION # 71
Benefits are:
Answer: A
Explanation:
In Canadian payroll, a benefit generally means the employer has provided something of value to the employee (or paid for something on the employee's behalf), rather than paying cash for work performed. The CRA's Employers' Guide - Taxable Benefits and Allowances (T4130)explains that a benefit/allowance may be provided in cash (for example, an allowance) or in a manner other than cash (for example, a parking space or gift), and that employers may have to include the value of that benefit/allowance in the employee's income depending on the circumstances.
Option C best captures this "value of something provided or paid for" concept. Option B describes wages
/salary (earnings for work). Option A aligns more with reimbursements/expense coverage. Option D aligns with allowances for business use of personal property (often treated separately and may be taxable or non- taxable depending on CRA rules and documentation). Payroll's role is to determine whether the benefit is taxable, value it correctly, and apply the right statutory withholdings and reporting.
NEW QUESTION # 72
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
STATUTORY DEDUCTIONS
OTHER DEDUCTIONS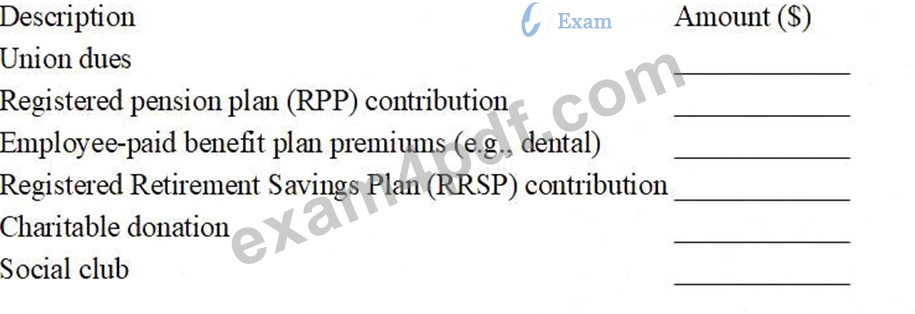
Given Data (Reference)
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
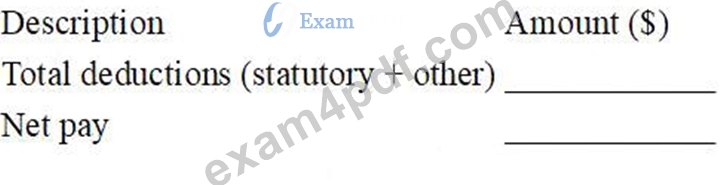
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 73
Dollar values attributed to something the employer has either provided to an employee or paid for on an employee's behalf are:
Answer: D
Explanation:
The CRA defines a benefit as something the employee receives when the employer pays for or gives something that is personal in nature (a good or service), either directly to the employee or through a third party. CRA's T4130 guide describes a benefit as a good or service you give (or arrange for) such as free use of employer property, and it is the value of that benefit that may need to be included in the employee's income if taxable.
This matches the wording in the question: "dollar values attributed to something the employer has either provided...or paid for...on an employee's behalf." By contrast, earnings are pay for work performed (salary, wages, commissions). Allowances are fixed amounts paid to help cover anticipated expenses without receipts (often taxable unless an exception applies). Expense reimbursements repay actual business expenses (typically supported by receipts) and are generally not treated as earnings.
So the correct classification is Benefits.
NEW QUESTION # 74
Dollar amounts that are paid to an employee to cover expenses that they incurred while performing their job, but are not considered in the calculation of an employee's earnings are:
Answer: B
Explanation:
An expense reimbursement is a repayment to an employee for business costs they already paid personally (for example, meals, mileage, supplies), typically supported by receipts or an expense report. CRA's guidance explains that a reimbursement is a payment made to repay amounts the employee spent while conducting the employer's business, and that a reasonable reimbursement is generally not included in the employee's income.
That's why reimbursements are generally not part of "earnings" for payroll calculations-they are not compensation for work performed; they are repayment of a business expense. This differs from an allowance, which is usually a fixed amount paid without requiring receipts; allowances are often taxable unless a specific CRA exception applies.
So the correct term for "dollar amounts paid to cover job expenses incurred, but not considered earnings" is expense reimbursements (option D). Payroll best practice is to ensure reimbursements are properly documented and reasonable to support non-taxable treatment.
NEW QUESTION # 75
Phillip is being paid a severance payment with his final pay. Which block should this payment be reported on the Record of Employment?
Answer: A
Explanation:
On the ROE, separation payments are reported in Block 17. Service Canada explains that Block 17C - Other monies is used to record "any other payments or benefits...paid...because of the separation," whether or not they are insurable.
The ROE Guide specifically lists "Severance pay" as a type of separation money to enter in Block 17C ("Enter 'Severance pay' and the amount").
Crucially, Block 15B and Block 15C are for insurable earnings totals/by pay period. The ROE Guide notes that some amounts reported in Block 17 (like vacation pay) are insurable and must be added into Blocks 15B
/15C; however, retirement leave credits/retiring allowances (a form of severance-type payment) are not insurable and are not added to Blocks 15B/15C even though they are recorded in Block 17C.
So, severance is reported in Block 17C only.
NEW QUESTION # 76
......
If you feel unconfident in self-preparation for your PF1 test and want to get professional aid of questions and answers, Exam4PDF PF1 test questions materials will guide you and help you to pass the certification exams in one shot. If you want to know our PF1 Test Questions materials, you can download our free demo now. Our demo is a small part of the complete charged version. Also you can ask us any questions about PF1 exam any time as you like.
PF1 Test Objectives Pdf: https://www.exam4pdf.com/PF1-dumps-torrent.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by Exam4PDF: https://drive.google.com/open?id=1veJfyYx7BGZ2YZYJnfJUYneA8y3Hl0xm