BTW, DOWNLOAD part of Pass4sures PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1FZBUDOSc3t1QZo3SsHX4bkNGjaUuPQ22
The Pass4sures is committed to ace the PF1 exam preparation at any cost. To achieve this objective the Pass4sures has hired a team of experienced and certified National Payroll Institute PF1 exam trainers. They work together and put all their expertise to offer Pass4sures PF1 Exam Questions in three different formats. These three PF1 exam practice question formats are PDF file, desktop practice test software, and web based practice test software.
| Section | Weight | Objectives |
|---|---|---|
| Communication and Compliance | 10% | - Accuracy and documentation
|
| Individual Pay Calculations | 40% | - Non-regular earnings
|
| Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Termination and Special Payments | 30% | - Leaves and absences
|
If you are going to look for PF1 exam braindumps, you may pay more attention to the quality as well as the pass rate. PF1 training materials are edited by experienced experts, and therefore the quality can be guaranteed. With the pass rate reaching 98.65%, our PF1 exam materials have received many good feedbacks from candidates. Besides, PF1 Exam Materials cover most of knowledge points for the exam, and you can mater them well through practicing as well as improve your ability in the process of training. We offer you free update for 365 days, and the update version for PF1 exam dumps will be auto sent to you.
NEW QUESTION # 15
Feraz Dalia is due $12,523.00 in legislated wages in lieu of notice that will be added to his last weekly pay of
$1,080.00. Calculate Feraz's Employment Insurance (EI) premium, if his employer is situated in Saskatchewan and the yearly maximum contribution will not be exceeded.
Answer:
Explanation:
$221.73 (employee EI premium)
Explanation:
In Saskatchewan (outside Quebec), EI premiums are deducted at the 2026 employee EI premium rate of $1.63 per $100 of insurable earnings (1.63%).
CRA guidance confirms that wages in lieu of termination notice are subject to EI premiums, and to determine statutory deductions you include the wages in lieu with the regular income (if any) for the pay period.
Step 1: Determine total insurable earnings in the final pay (assuming both amounts are insurable and the annual maximum won't be exceeded):
$12,523.00 + $1,080.00 = $13,603.00.
Step 2: Calculate EI premium:
$13,603.00 × 1.63% = $13,603.00 × 0.0163 = $221.7289, which rounds to $221.73.
So, the EI premium to deduct from Feraz's pay for this combined payment is $221.73.
NEW QUESTION # 16
Anthony earns $750.00 per week. He has a cash taxable benefit of $25.00 per week. Anthony is exempt from CPP contributions. Calculate the net taxable income for the week.
Answer:
Explanation:
$775.00
Explanation:
"Net taxable income" for payroll withholding purposes is the amount of income on which income tax is calculated for the pay period. It generally starts with the employee's gross taxable earnings for the period (regular wages plus any taxable benefits/allowances that must be included in income), then subtracts only those deductions that are deductible for tax at source (for example, certain registered pension plan contributions, union dues, etc., if applicable). A cash taxable benefit is treated like additional remuneration and is included in taxable income. (canada.ca) Here, Anthony's weekly taxable earnings are:
$750.00 wages + $25.00 cash taxable benefit = $775.00.
Being exempt from CPP contributions affects whether CPP is deducted, but CPP is not a "net taxable income" subtraction in this question (and in any case, no CPP is being deducted). The question also does not mention any other tax-deductible payroll deductions (like RPP contributions), so there is nothing to subtract from taxable earnings.
Therefore, Anthony's net taxable income for the week is $775.00.
NEW QUESTION # 17
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
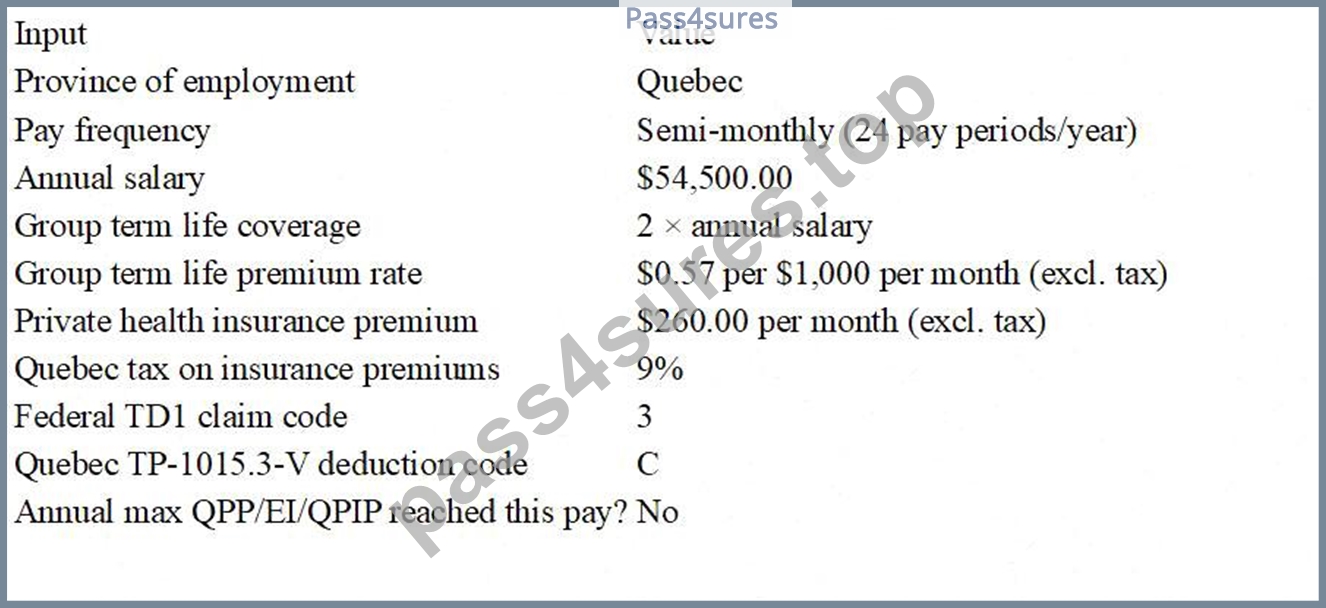
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases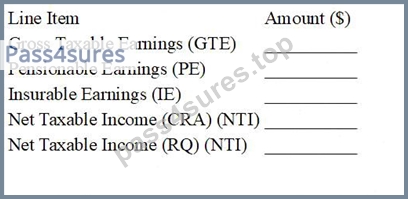
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
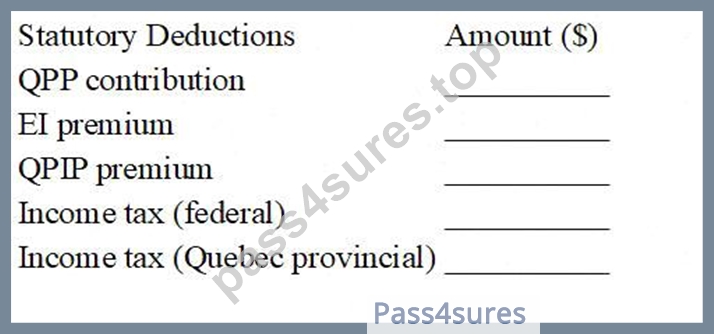
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
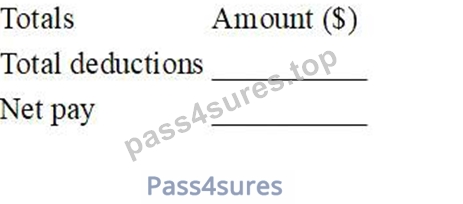
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 18
Alyssa is a member of her employer's Defined Contribution Pension Plan. The plan defines the contribution as 3% of the employee's pensionable earnings, with the employer matching the employee's contribution.
Alyssa's pensionable earnings are $3,400.00 per month. Calculate the total payment to be remitted to Alyssa's Defined Contribution Pension Plan each month.
Answer:
Explanation:
$204.00 per month
Explanation:
In a Defined Contribution (DC) pension plan, contributions are calculated as a set percentage of the employee' s pensionable earnings, and the total remittance is usually the sum of the employee deduction plus the employer's matching contribution, based on the plan text. Here, the plan states the employee contributes 3% of pensionable earnings, and the employer matches the employee contribution.
Step 1: Calculate the employee's pension contribution:
3% × $3,400.00 = 0.03 × 3,400.00 = $102.00.
Step 2: Calculate the employer match:
Because the employer matches the employee contribution, the employer contributes $102.00 as well.
Step 3: Total remittance to the plan:
$102.00 (employee) + $102.00 (employer) = $204.00 each month.
From a payroll processing perspective, the employee amount is withheld from gross pay as a payroll deduction according to plan rules, while the employer match is recorded as an employer expense. Payroll remits both amounts to the plan administrator following the plan's remittance schedule, and should reconcile pensionable earnings and contributions to ensure accuracy and compliance with plan terms.
NEW QUESTION # 19
The employee-employer relationship is deemed to be severed when:
Answer: A
Explanation:
In ROE administration, the key concept is whether the employment relationship is still "active" (that is, whether there is an ongoing expectation the employee will work again). Service Canada's ROE guidance ties ROE issuance to an interruption of earnings and specifically identifies situations where an employee is no longer on the employer's active employment list (for example, no expectation of future work) as a trigger for issuing an ROE.
Options A and B describe circumstances that can still align with an ongoing employment relationship. For example, employees may remain eligible for certain benefits after a last day worked, and a right to recall means the employer may still consider the employee attached to the workplace (often still "active" depending on the arrangement). In contrast, when there is no expectation of work to be performed, the relationship is effectively ended for ROE purposes, and the employer generally proceeds with separation reporting and ROE completion based on the interruption of earnings rules.
NEW QUESTION # 20
......
You deserve this opportunity to win and try to make some difference in your life if you want to attend the PF1 exam and get the certification by the help of our PF1 practice braindumps. As we all know, all companies will pay more attention on the staffs who have more certifications which is a symbol of better understanding and efficiency on the job. Our PF1 Study Materials have the high pass rate as 98% to 100%, hope you can use it fully and pass the exam smoothly.
New PF1 Test Practice: https://www.pass4sures.top/Payroll-Fundamentals/PF1-testking-braindumps.html
What's more, part of that Pass4sures PF1 dumps now are free: https://drive.google.com/open?id=1FZBUDOSc3t1QZo3SsHX4bkNGjaUuPQ22