What's more, part of that Pass4cram ClaimCenter-Business-Analysts dumps now are free: https://drive.google.com/open?id=1A5M8tThBsnVlSz44sIlqwb_xxsedXT93
Pass4cram offers actual and updated Guidewire ClaimCenter-Business-Analysts Dumps after seeing the students struggling to prepare quickly for the test. We have made this product after consulting with a lot of professionals so the students can be successful. Pass4cram has hired a team of professionals who work on a daily basis without caring about themselves to update the Guidewire ClaimCenter-Business-Analysts practice material.
| Section | Objectives |
|---|---|
| Topic 1: Behavior Driven Development (BDD) | - BDD in Guidewire
|
| Topic 2: ClaimCenter Financials & Operations | - Financial Transactions
|
| Topic 3: Guidewire InsuranceSuite Fundamentals | - Platform Overview
|
| Topic 4: Quality Assurance & Business Analysis Fundamentals | - Quality Analyst Basics
|
>> ClaimCenter-Business-Analysts Exam Engine <<
About the upcoming ClaimCenter-Business-Analysts exam, do you have mastered the key parts which the exam will test up to now? Everyone is conscious of the importance and only the smart one with smart way can make it. When new changes or knowledge are updated, our experts add additive content into our ClaimCenter-Business-Analysts latest material. They have always been in a trend of advancement. Admittedly, our ClaimCenter-Business-Analysts Real Questions are your best choice. We also estimate the following trend of exam questions may appear in the next exam according to syllabus. So they are the newest and also the most trustworthy ClaimCenter-Business-Analysts exam prep to obtain.
NEW QUESTION # 16
What are two recommended best practices with user interface (UI) mock-ups in a ClaimCenter implementation project? (Choose two.)
Answer: A,C
Explanation:
In a Guidewire implementation, User Interface (UI) mock-ups serve as critical visual aids to bridge the gap between written business requirements and the final technical solution.
* Best Practice 1 (Option B):While sophisticated prototyping tools (like Balsamiq or Axure) are valuable, they are not always strictly necessary for every change. A "low-fidelity" mock-up is often sufficient and highly effective for minor adjustments. If a BA lacks access to specialized software, the recommended best practice is to take a screenshot of the existing ClaimCenter screen and overlay it with text boxes, arrows, or simple graphics (using tools like Paint or PowerPoint) to clearly indicate where fields should be added, moved, or removed. The goal is clarity of intent, not artistic perfection.
* Best Practice 2 (Option D):Traceability is fundamental to the Agile and hybrid methodologies used in Guidewire projects. Every artifact, including mock-ups, must be traceable back to the specificUser StoryorRequirement Numberit supports. By explicitly documenting the requirement number on or with the mock-up, the BA ensures that developers understand exactly which functionality is being visualized and that QA testers can validate the final screen against the correct scope.
Why other options are incorrect:
* Option A:A live demo shows thecurrentstate. It cannot effectively demonstratefuturechanges (fields that don't exist yet) without a visual mock-up to accompany the explanation.
* Option C:Stating that tools "should not be used" is incorrect; tools are generally encouraged when available to create high-fidelity prototypes.
NEW QUESTION # 17
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.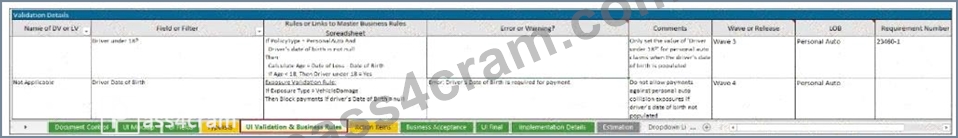
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: C,D
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 18
An auto claim is owned by Adjuster1. The Customer Service Representative (CSR) that created the claim owns one follow-up activity on the claim. An Injury Specialist owns an injury exposure on the claim. All these persons are members of Auto Team 1.
The Team Lead determines that Adjuster1 is overworked and reassigns the claim to Adjuster2, a member of Auto Team 2.
Which three people now have access to the claim? (Choose three.)
Answer: A,D,F
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
In Guidewire ClaimCenter, access to a claim file is determined by Access Control Lists (ACLs), which are dynamically updated based on user roles and ownership. A user is granted access to a claim if they own the claim itself, or if they own a sub-object within that claim, such as an Activity or an Exposure.
* Adjuster2 (Option E):Upon reassignment, Adjuster2 becomes the newClaim Owner. The owner of the claim record always has full view and edit access to the claim.
* CSR (Option C):The CSR retains ownership of a specificActivity(the follow-up task). In the ClaimCenter security model, owning an open activity on a claim grants the user "view" access to the parent claim so they can perform the necessary work to complete their task. Reassigning the claim header does not automatically reassign the activities owned by other users.
* Injury Specialist (Option D):This user owns anExposure(a distinct financial sub-record for a specific coverage feature). Similar to activities, owning an exposure grants access to the parent claim. The reassignment of the main claim file from Adjuster1 to Adjuster2 does not strip the Injury Specialist of their ownership of the specific injury exposure.
Why Adjuster1 loses access:Adjuster1 was the previous owner. Once ownership is transferred to Adjuster2 (who is in a different group, "Auto Team 2"), Adjuster1 no longer meets the criteria for ownership access.
Unless Adjuster1 is explicitly added to the ACL manually or has "Super User" privileges (not stated), they lose the automatic access rights associated with being the owner.
NEW QUESTION # 19
An Adjuster at Succeed Insurance increases the reserve on a claim's exposure from $1,000 to $1,500 to account for inflation in repair costs. A week later, a Supervisor reviews the claim and wants to know specifically who made this change, the exact date and time it was made, and what the previous value was.
The Supervisor needs a chronological audit trail of changes to the claim file without navigating through complex financial ledgers.
Which screen in the ClaimCenter user interface should the Supervisor access to find this information?
Answer: D
NEW QUESTION # 20
Under the Travel loss type, Succeed Insurance offers personal travel policies as part of its travel line of business.
Which two pieces of information in the user interface (UI) will be different for a personal travel claim than for a personal auto or homeowners claim? (Choose two.)
Answer: D,E
Explanation:
Guidewire ClaimCenter is designed to support multiple Lines of Business (LOB), and the User Interface adapts dynamically based on the policy type associated with the claim.
* Incident Types (Option B):The "Incident" is the object that describes what was damaged or lost.
* ForAuto, the UI displaysVehicle Incidents(describing cars).
* ForHomeowners, the UI displaysDwellingorFixed Property Incidents.
* ForTravel, the UI will display distinct incident types such asBaggage Incident(for lost luggage) orTrip Cancellation Incident. These are fundamentally different data objects with different fields.
* Loss Causes (Option C):The LossCause typelist is filtered by the Line of Business.
* Autoclaims show causes like "Collision," "Rear-end," or "Theft of Vehicle."
* Travelclaims will show completely different values such as "Trip Delay," "Lost Baggage,"
"Medical Emergency," or "Cancellation."
Why other options are incorrect:
* Financial Summary (A):The structural format of the Financial Summary screen (displaying Reserve Lines, Payments, and Remaining Reserves) is a core system framework that remains consistent across all lines of business.
* Contact Information (E):The Contact entity (Name, Address, Phone) is a shared entity. The fields used to capture a person's details are generally the same whether they are a driver, a homeowner, or a traveler.
NEW QUESTION # 21
......
Holding a certification in a certain field definitely shows that one have a good command of the ClaimCenter-Business-Analysts knowledge and professional skills in the related field. However, the majority of the candidates for the ClaimCenter-Business-Analysts exam are those who do not have enough spare time. But our company can provide the anecdote for you--our ClaimCenter-Business-Analysts Study Materials. Under the guidance of our ClaimCenter-Business-Analysts exam practice, you can definitely pass the exam as well as getting the related certification with the minimum time and efforts. Our ClaimCenter-Business-Analysts exam questions will never let you down.
Test ClaimCenter-Business-Analysts Questions Vce: https://www.pass4cram.com/ClaimCenter-Business-Analysts_free-download.html
2026 Latest Pass4cram ClaimCenter-Business-Analysts PDF Dumps and ClaimCenter-Business-Analysts Exam Engine Free Share: https://drive.google.com/open?id=1A5M8tThBsnVlSz44sIlqwb_xxsedXT93