What's more, part of that Dumpkiller PF1 dumps now are free: https://drive.google.com/open?id=1_vWqZoLuxynqZV1wNXCtBRMPzCPi5B9t
You may worry that you still fail PF1 exam although you have made full preparation for the exam; or you may afraid that the exam software you purchased is not right for you. Our PF1 exam software developed by our Dumpkiller will clear your worries. Our PF1 exam software will provide two level of insurance for you: the first is the reassuring high pass rate; the second is full refund of your cost you purchased our exam software. Don't worry, if you fail PF1 Exam with our software, we will refund the money you purchased our dumps. What you do is to prepare for the exam confidently, and our Dumpkiller will be in charge of other issues.
| Section | Objectives |
|---|---|
| Topic 1: Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
| Topic 2: Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
| Topic 3: Earnings, Deductions, and Taxation | - Deductions and remittances
|
>> Real National Payroll Institute PF1 Question <<
National Payroll Institute PF1 certification exam is among those popular IT certifications. It is also the dream of ambitious IT professionals. This part of the candidates need to be fully prepared to allow them to get the highest score in the PF1 Exam, make their own configuration files compatible with market demand.
NEW QUESTION # 14
Which of the following is not correct?
Answer: B
Explanation:
Option A is not correct. Service Canada's ROE guidance for paper ROEs explains that if you need to complete Block 15C, you do that first, and then you still enter the total insurable earnings in Block 15B. It also reminds employers to include any insurable separation payments entered in Block 17 in both Block 15C (Pay Period 1) and Block 15B totals.
Option C is correct because retiring allowances (often treated as severance-type amounts) are not insurable, so even if they appear in Block 17C, they are not added to Blocks 15B/15C.
Option D is correct because vacation pay paid on separation is reported in Block 17A, and when it is insurable, it must be included in the insurable earnings totals in Block 15B (and Block 15C P.P.1 where applicable).
NEW QUESTION # 15
Which statutory deductions is salary continuance subject to?
Answer: D
Explanation:
Salary continuance means the employee continues to receive regular pay (and often benefits) for a period after their job ends. In this arrangement, the payments are treated like regular employment income for payroll purposes, so the usual payroll deductions apply. A Government of Canada guidance page explains that when severance is paid as salary continuance, the employee pays income tax like regular employment income and that the usual deductions apply, including CPP (or QPP), EI premiums, and RPP contributions (where applicable).
This aligns with standard payroll obligations in CRA's payroll remittance framework: employers deduct and remit CPP contributions, EI premiums, and income tax on employment income unless a specific exemption applies.
Therefore, the correct option is B (All deductions)-and in Quebec, that "all deductions" concept includes Quebec-specific programs (for example QPP/QPIP where applicable) based on the employee's province of employment and insurability rules.
NEW QUESTION # 16
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
STATUTORY DEDUCTIONS
OTHER DEDUCTIONS

Given Data (Reference)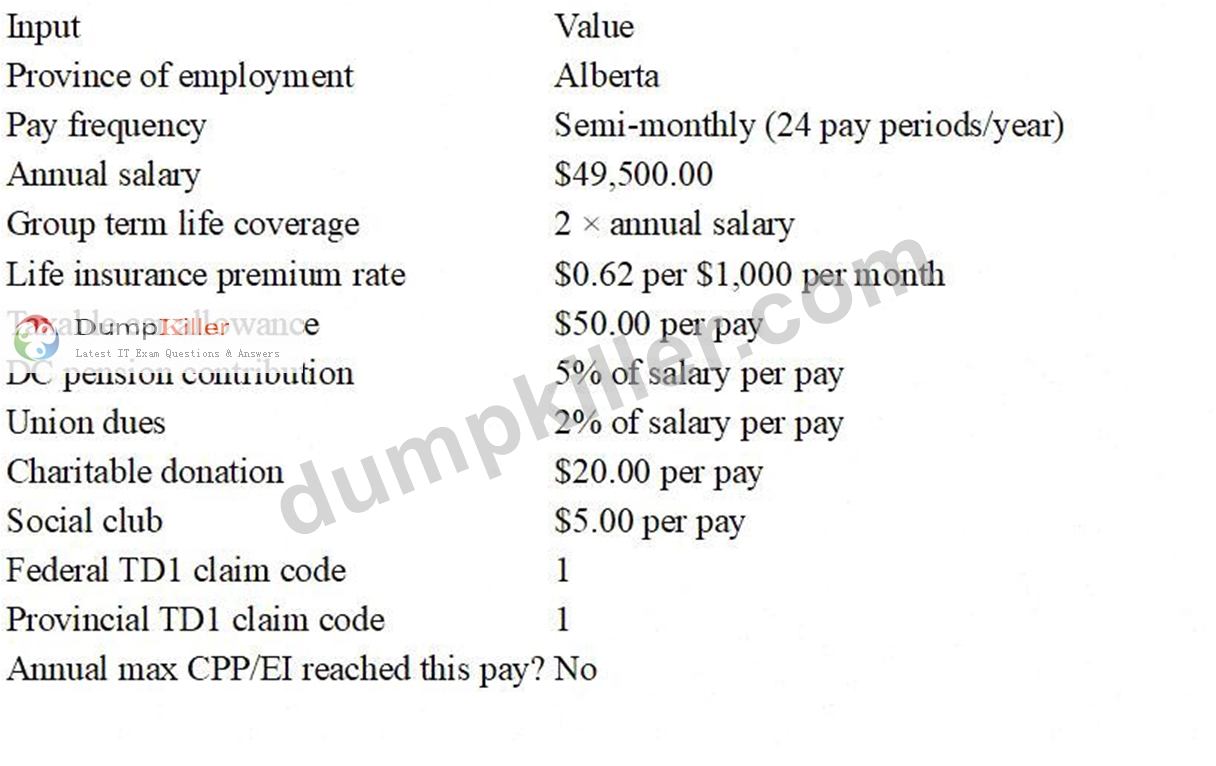
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 17
A paper Record of Employment must be issued:
Answer: D
Explanation:
Service Canada's ROE guidance states that an employer must issue an ROE each time an employee experiences an interruption of earnings and when Service Canada requests one. This makes option A true.
For paper ROEs, the ROE guide is explicit about deadlines: you must issue a paper ROE within 5 calendar days of (1) the first day of an interruption of earnings, or (2) the day the employer becomes aware that an interruption of earnings has occurred. This confirms option B.
An interruption of earnings generally occurs under the 7-day rule-when an employee has had or is anticipated to have 7 consecutive calendar days with no work and no insurable earnings from the employer.
That's why option C is also true: once the employer becomes aware the 7-day threshold is met (or will be met), the ROE requirement is triggered, and the paper ROE must be issued within the time limit above.
NEW QUESTION # 18
By the authority of which Act can the Canada Revenue Agency garnish the wages of an employee who has failed to pay Employment Insurance premiums, Canada Pension Plan contributions, or income tax deductions?
Answer: D
Explanation:
The CRA's wage garnishment tool is commonly issued as a Requirement to Pay (RTP) (and related instruments such as ERTP/DTP), which directs a third party (often the employer) to redirect amounts that would otherwise be paid to the employee, and send them to the government instead. CRA guidance explains that when an employee owes money, the CRA can send the employer a requirement to pay notice, and the employer must remit the amounts as instructed (or the employer can become liable).
The legal authority for the CRA to issue a Requirement to Pay is found in the Income Tax Act, including section 224, which sets out the mechanism and consequences for non-compliance.
In payroll operations, this is a communication-and-compliance issue: payroll must correctly interpret the notice, apply the withholding/remittance as directed, and communicate impacts to internal stakeholders (HR
/finance) and, where appropriate, the affected employee-while ensuring the remittance is made exactly as the CRA notice requires.
NEW QUESTION # 19
......
There is a group of experts in our company which is especially in charge of compiling our PF1 exam engine. There is no doubt that we will never miss any key points in our PF1 training materials. As it has been proven by our customers that with the help of our PF1 Test Prep you can pass the exam as well as getting the related PF1 certification only after 20 to 30 hours' preparation, which means you can only spend the minimum of time and efforts to get the maximum rewards.
Exam PF1 Labs: https://www.dumpkiller.com/PF1_braindumps.html
2026 Latest Dumpkiller PF1 PDF Dumps and PF1 Exam Engine Free Share: https://drive.google.com/open?id=1_vWqZoLuxynqZV1wNXCtBRMPzCPi5B9t