BONUS!!! Download part of Real4Prep IFC dumps for free: https://drive.google.com/open?id=1gT9pn-L9OE9fUNoJu6IaH6c8HcTu7APX
Whole Real4Prep's pertinence exercises about CISI certification IFC exam is very popular. Real4Prep's training materials can not only let you obtain IT expertise knowledge and a lot of related experience, but also make you be well prepared for the exam. Although CISI Certification IFC Exam is difficult, through doing Real4Prep's exercises you will be very confident for the exam. Be assured to choose Real4Prep efficient exercises right now, and you will do a full preparation for CISI certification IFC exam.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
We do gain our high appraisal by our IFC quiz torrent and there is no question that our IFC test prep will be your perfect choice. It is our explicit aim to help you pass it. Our latest IFC exam torrent are perfect paragon in this industry full of elucidating content for exam candidates of various degree to use. Our results of latest IFC Exam Torrent are startlingly amazing, which is more than 98 percent of exam candidates achieved their goal successfully.
NEW QUESTION # 23
Last year Peter's earned income from employment was $50,000.
Last year, after receiving a $2 per share in dividends from 500 shares in ABC Inc., a publicly-traded Canadian corporation, he sold his shares. The sale resulted in a capital gain of $15,000.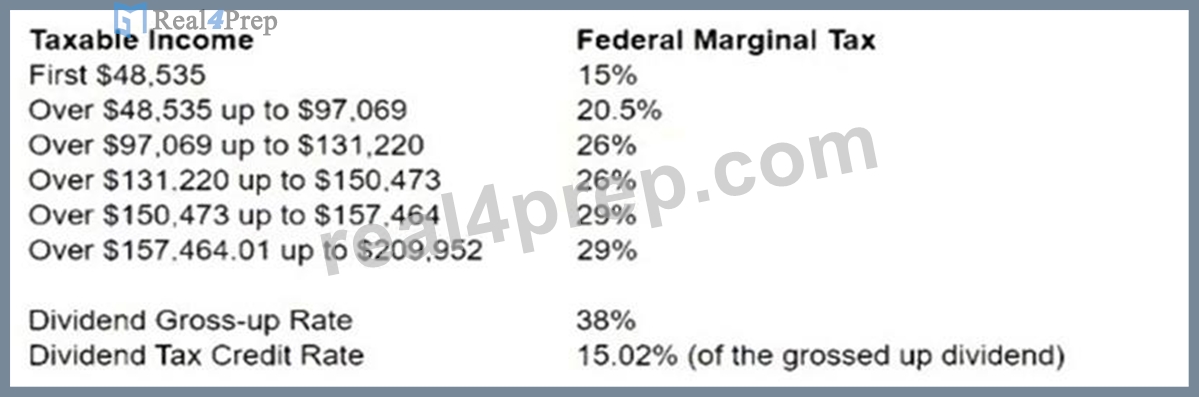
Based on the tax rates mentioned above, what is Peter's net federal tax liability for the year? (Round to 2 decimal places).
Answer: C
Explanation:
To calculate Peter's net federal tax liability for the year, we need to follow these steps:
* Step 1: Calculate Peter's taxable income. This is the amount of income that is subject to federal income tax. It is equal to his earned income from employment plus his net capital gain plus his grossed-up dividend income. A net capital gain is 50% of the capital gain realized from selling an asset. A grossed- up dividend income is the actual dividend received plus a percentage of the dividend that reflects the corporate tax paid by the issuer. According to the image, the dividend gross-up rate is 15.02%.
Therefore, Peter's taxable income is:
50000+0.5×15000+(500×2)×(1+0.1502)=68251.00
* Step 2: Apply the federal tax rates to Peter's taxable income according to the tax brackets shown in the image. The federal tax rates are progressive, meaning that higher income is taxed at higher rates.
Therefore, Peter's federal tax before credits is:
0.15×(48535#0)+0.205×(68251#48535)=11293.69
* Step 3: Subtract the federal tax credits from Peter's federal tax before credits. A tax credit is an amount that reduces the tax payable by a taxpayer. There are two types of federal tax credits: non-refundable and refundable. Non-refundable tax credits can only reduce the tax payable to zero, but not below zero.
Refundable tax credits can reduce the tax payable below zero, resulting in a refund to the taxpayer. In this question, we assume that Peter only has two non-refundable tax credits: the basic personal amount and the dividend tax credit. The basic personal amount is a fixed amount that every taxpayer can claim to reduce their taxable income. According to this site, the basic personal amount for 2021 is $13,808.
The dividend tax credit is a percentage of the grossed-up dividend income that reflects the corporate tax paid by the issuer and avoids double taxation. According to this site, the federal dividend tax credit rate for eligible dividends in 2021 is 15.0198%. Therefore, Peter's federal tax credits are:
0.15×13808+0.150198×(500×2)×0.1502=2100
* Step 4: Subtract Peter's federal tax credits from his federal tax before credits to get his net federal tax liability. This is the amount of federal income tax that Peter has to pay or has overpaid for the year.
Therefore, Peter's net federal tax liability is:
11293.69#2100=9193.69
Hence, option B is correct. References: Federal Income Tax Rates for Canada - TurboTax Canada Tips, Capital Gains Tax in Canada | Wealthsimple, Dividend Tax Credit | TurboTax Canada Tips, Basic Personal Amount (BPA)
NEW QUESTION # 24
Which statement CORRECTLY describes index mutual funds and traditional exchange-traded funds (ETFs)?
Answer: D
Explanation:
Index mutual funds and traditional exchange-traded funds (ETFs) are both types of investment funds that use a passive investment management style, which means they try to track the performance of a specific market index, such as the S&P/TSX Composite Index or the S&P 500 Index. They do so by holding the same securities as the index or a representative sample of them, and by adjusting their portfolio composition and weighting to reflect any changes in the index. However, both types of funds may not be able to exactly replicate the return of the index for various reasons, such as fees, expenses, tracking error, rebalancing frequency, dividend reinvestment, and cash holdings. Therefore, there may be some deviation or difference between the fund's return and the index's return, which is called tracking difference.
1: Canadian Investment Funds Course, Chapter 4: Types of Investments1
NEW QUESTION # 25
Justin and Yvonne both open a Registered Education Savings Plan (RESP) for their daughter Grace. They plan to regularly contribute $1,000 per year until Grace reaches the age of 17.
Which of the following statements relating to RESP is CORRECT?
Answer: A
Explanation:
A Registered Education Savings Plan (RESP) is a tax-advantaged savings plan that helps parents and family members save for a child's post-secondary education. The government also contributes to the plan through the Canada Education Savings Grant (CESG) and the Canada Learning Bond (CLB), depending on the family income and the amount of contributions. However, there are some rules and limits that apply to RESP contributions and government grants. One of them is the lifetime contribution limit, which is the maximum amount that can be contributed to an RESP for a beneficiary from all sources. The lifetime contribution limit is $50,000 per beneficiary, regardless of how many RESPs are opened for them or who contributes to them.
Therefore, statement A is correct. Justin and Yvonne may contribute a combined lifetime maximum of
$50,000 for Grace to their RESP.
The other statements are incorrect for the following reasons:
* Statement B: RESPs are not tax-free investment plans. They are tax-deferred plans, meaning that the contributions are made with after-tax dollars and the investment income earned in the plan is not taxed until it is withdrawn as an educational assistance payment (EAP) for the beneficiary. The EAPs are taxed in the hands of the beneficiary, who usually has little or no income and pays little or no tax.
* Statement C: There is no annual contribution limit for RESP contributions. However, there is an annual limit for the CESG, which is 20% of the first $2,500 contributed per beneficiary per year, up to a maximum of $500 per year. The CESG also has a lifetime limit of $7,200 per beneficiary.
* Statement D: Contributions made to an RESP are not eligible for a tax deduction in the year they are contributed. They are made with after-tax dollars and do not reduce the contributor's taxable income.
1: Canadian Investment Funds Course, Unit 9, Section 9.1
NEW QUESTION # 26
Your client, Rinaldo, wants to know more about the fees associated with his mutual funds. What can you tell him about a mutual fund's management expense ratio (MER)?
Answer: B
Explanation:
C is correct because the management expense ratio (MER) reflects the percentage of each dollar of fund assets that is used to pay for management services and operating expenses of a mutual fund. The MER includes various fees and expenses, such as management fees, administration fees, trailer fees, audit fees, legal fees, and taxes. The MER reduces the return of the fund, as it is deducted from the fund's income and capital gains before they are distributed to investors. Mutual funds are not required to calculate the MER on a daily basis (A), but rather on an annual basis. Trailer and brokerage fees are included in the MER (B), not charged separately. Mutual fund performance is impacted by the MER (D), as it lowers the net return of the fund. Rates of return are published net of fees, but they do not reflect the impact of the MER on the fund's performance.
NEW QUESTION # 27
What is the first step before becoming eligible for registration as a mutual fund dealing representative?
Answer: A
NEW QUESTION # 28
......
In addition, a 24/7 customer assistance is also available at IFC to assist you in using the product during any technical hitch. In summary, getting ready for 60 certification test might be challenging, but with the appropriate strategy and our IFC Actual Exam questions, you can clear the test in a short time.
Test IFC Questions: https://www.real4prep.com/IFC-exam.html
P.S. Free & New IFC dumps are available on Google Drive shared by Real4Prep: https://drive.google.com/open?id=1gT9pn-L9OE9fUNoJu6IaH6c8HcTu7APX