AFP-Exam-1 practice questions are stable and reliable exam questions provider for person who need them for their exam. We have been staying and growing in the market for a long time, and we will be here all the time, because the excellent quality and high pass rate of our AFP-Exam-1 training braindump. As for the safe environment and effective product, there are thousands of candidates are willing to choose our AFP-Exam-1 study guide, why don’t you have a try for our AFP-Exam-1 study material, never let you down!
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Client Relationship and Practice Management - Professional Conduct and Regulatory Compliance |
| Technical Competencies | 84% | - Risk Management and Insurance - Tax Planning - Investment Planning - Asset and Liability Management - Retirement Planning - Estate Planning |
They work together and strive hard to maintain the top standard of CSI AFP-Exam-1 exam practice questions all the time. So you rest assured that with the AFP-Exam-1 Exam Dumps you will ace your CSI AFP-Exam-1 exam preparation and feel confident to solve all questions in the final CSI AFP-Exam-1 exam.
NEW QUESTION # 44
Consider the following information for a client's portfolio: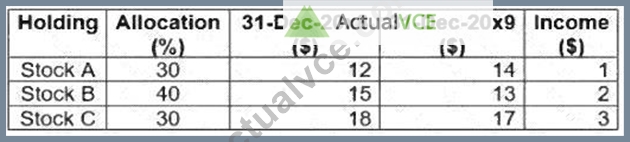
What is the annual rate of return for this portfolio?
Answer: A
Explanation:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
NEW QUESTION # 45
Keitaro, age 42, and Ruth, age 52, are married and have two children - Maximo, age 20, and Hannah, age 16, both from Keitaro's previous marriage. In the event Keitaro dies, he would like to minimize taxes, provide for Ruth for the remainder of her life, and then after her death leave the residual to his children. What estate planning strategy should his financial planner recommend to help Keitaro achieve his goal?
Answer: C
Explanation:
A testamentary spousal trust is the best strategy for Keitaro's blended-family objective. It can provide Ruth with income for life, defer tax on assets transferred at death to a qualifying spouse or spousal trust, and preserve the remaining capital for Maximo and Hannah after Ruth's death. The trust is created through Keitaro's will, so it is testamentary, not inter vivos. The children should be capital beneficiaries, not income beneficiaries during Ruth's lifetime, because the goal is to provide for Ruth first and leave the residual to the children later. Naming the children as income and capital beneficiaries while Ruth is alive would undermine the spousal-trust rollover requirements and the planning objective. The planner should refer Keitaro to an estate lawyer to draft the trust terms precisely. Study Guide focus: testamentary spousal trusts, blended-family planning, spousal rollover, income beneficiary, and capital remainder. The will should also address trustee powers, encroachment rights, tax filings, and the treatment of registered assets.
NEW QUESTION # 46
Demario, age 28, has just started his own law firm. He met with his financial planner, Ivy, and she told him that he needs insurance, but Ivy did not specify which type. Demario is single and owns his own home. At this point in his career, his greatest asset is his human capital. Which type of insurance should Ivy have specified to purchase in order for Demario to best protect this asset?
Answer: C
Explanation:
Demario's human capital is his capacity to earn professional income from his law practice. A disability can destroy that earning capacity without causing death and without necessarily triggering critical illness coverage. Disability insurance is therefore the correct product to protect his greatest asset. Term life insurance would be more relevant if he had dependants, estate obligations, or a debt-repayment need at death. Extended health care helps with medical and dental costs but does not replace a lawyer's income if he cannot work.
Critical illness insurance pays on diagnosis of specified illnesses and can supplement planning, but it does not provide the same ongoing income-replacement function as disability coverage. Because Demario is self- employed, policy features such as own-occupation definition, elimination period, benefit period, and business overhead coverage should be reviewed carefully. Study Guide focus: human capital, disability insurance, self- employed professionals, income replacement, and risk management. The recommendation is therefore built around income continuity, not estate creation or reimbursement of medical expenses.
NEW QUESTION # 47
Keitaro wants his spouse to receive income from his assets for life after his death, but wants the remaining capital to pass to his children from a prior marriage after the spouse dies. Which strategy best fits this objective?
Answer: A
Explanation:
A testamentary spousal trust is a classic blended-family tool. It can provide income or benefit to the surviving spouse during the spouse's lifetime while preserving the remaining capital for children or other remainder beneficiaries. Properly structured, it may also allow a tax-deferred rollover to the trust at death, subject to the spouse-benefit requirements. Option B gives the spouse full control and does not protect the children's remainder interest. Option C can create immediate tax consequences, loss of control, creditor exposure, family law risk, and disputes over beneficial ownership. Option D may increase probate administration and does not, by itself, control the spouse-versus-children distribution problem. The planner should identify the strategy but refer the client to an estate lawyer for drafting. The will must clearly define income rights, capital encroachment rules, trustee powers, tax allocation, and final distribution. References/topics: testamentary spousal trust, blended-family estate planning, tax-deferred rollover, capital beneficiaries. Trustee selection is also central because discretion must be exercised impartially.
NEW QUESTION # 48
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.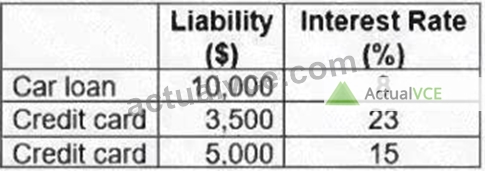
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: C
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 49
......
If you want to be a part of a great company, such as AFP-Exam-1, preparing and taking the exam with AFP-Exam-1 study guide will be your best choice, because there have been more and more big companies to pay real attention to these people who have passed the AFP-Exam-1 Exam and have got the related certification in the past years. It is a generally accepted fact that the AFP-Exam-1 exam has attracted more and more attention and become widely acceptable in the past years.
Exam AFP-Exam-1 Blueprint: https://www.actualvce.com/CSI/AFP-Exam-1-valid-vce-dumps.html