P.S. Free 2026 IFSE Institute LLQP dumps are available on Google Drive shared by DumpsFree: https://drive.google.com/open?id=1Z7T7EWNa_ow0Vj0BUmA-pckFuoyNEpvr
The Life License Qualification Program (LLQP) (LLQP) practice questions are designed by experienced and qualified Life License Qualification Program (LLQP) (LLQP) exam trainers. They have the expertise, knowledge, and experience to design and maintain the top standard of Life License Qualification Program (LLQP) (LLQP) exam dumps. So rest assured that with the Life License Qualification Program (LLQP) (LLQP) exam real questions you can not only ace your Life License Qualification Program (LLQP) (LLQP) exam dumps preparation but also get deep insight knowledge about IFSE Institute LLQP exam topics. So download Life License Qualification Program (LLQP) (LLQP) exam questions now and start this journey.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
In order to ensure the quality of our LLQP actual exam, we have made a lot of efforts. Our company spent a great deal of money on hiring hundreds of experts and they formed a team to write the work. The qualifications of these experts are very high. They have rich knowledge and rich experience on the LLQP Study Guide. So they know every detail about the LLQP exam questions and can make it better. With our LLQP learning guide, you will be bound to pass the exam.
NEW QUESTION # 190
Last month, Suzanne purchased a life insurance policy from a local agent. The agent told her that the policy would accrue a cash value that she could draw from in her retirement years and that the premium would never increase. After recently meeting with a close friend, who is a retired insurance advisor, she was dismayed to learn that what was sold to her is in fact a term policy with no cash value. If Suzanne wishes to make a formal complaint against the agent, which authority can assist her in doing so?
Answer: B
Explanation:
Comprehensive and Detailed in Depth Explanation with Exact Extract from Documents and Guides:
The agent's misrepresentation violates ethical standards. TheIFSE Ethics and Professional Practice Course (Common Law)identifies the OmbudService for Life and Health Insurance (OLHI) as an independent body that assists consumers with complaints against insurance agents or companies when internal resolution fails.
Assuris (A) protects policyholders if an insurer fails, not for agent misconduct. The Canadian Council of Insurance Regulators (C) coordinates policy, not complaints. The Office of the Privacy Commissioner (D) handles privacy issues, not misrepresentation. OLHI is the correct avenue for Suzanne, making B correct.
References:
IFSE Ethics and Professional Practice Course (Common Law), Module 4: Regulatory Environment, Section on "OmbudService for Life and Health Insurance."
NEW QUESTION # 191
(Gertrude wishes to invest her savings while having creditor protection and minimizing risk.
What type of segregated fund would be most suitable for her?)
Answer: A
Explanation:
Money market segregated fundsare considered the least risky because they invest in short-term, high-quality investments and offer principal preservation features. They also benefit from thecreditor protection associated with segregated fund contracts.
Exact Extract:
"Money market funds aim to preserve capital by investing in highly liquid, low-risk instruments. Segregated fund contracts may also offer creditor protection if structured appropriately." (Reference:Segfunds-E313-2020-12-7ED, Chapter 2.2.1 Money Market Funds)
NEW QUESTION # 192
Jasper is the sole breadwinner in his family. His wife Stephanie has chosen to dedicate all of her time to raising their 3 young children. Luckily, Jasper earns a monthly after-tax income of $25,000 working as a family doctor in the local clinic. Jasper meets with his insurance agent Odda to purchase a life insurance policy that will ensure his family will be able to continue to enjoy their current lifestyle in the event of his death. If his average tax rate is 40% and theinvestment return is 4%, how much life insurance should Jasper purchase based on the income replacement approach?
Answer: D
Explanation:
The income replacement approach calculates the amount of life insurance needed to replace Jasper'safter-tax income for his dependents over a given period, accounting for an investment return. To maintain the family's current lifestyle, we need to determine the capital required to generate a monthly after-tax income of $25,000.
Calculate the Annual Income Needed:Monthly income required: $25,000Annual income required: $25,000 ×
12 = $300,000
Adjust for Tax:Since Jasper's income needs to be replaced at a pre-tax level with a tax rate of 40%, his gross income requirement is calculated as follows:
A close-up of a math Description automatically generated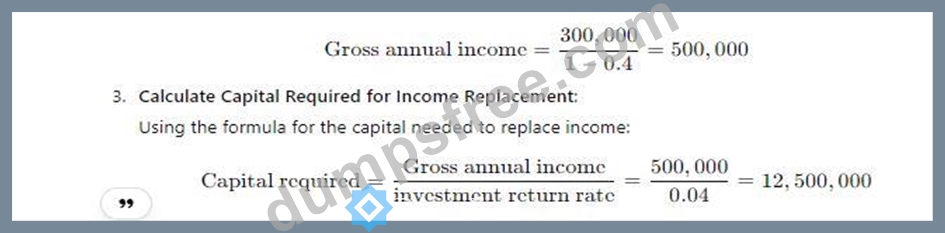
Thus, Jasper needs a life insurance policy worth$12,500,000to replace his income, allowing his family to maintain their lifestyle with a 4% investment return. This calculation aligns with LLQP principles, ensuring that the income replacement fully addresses both current lifestyle needs and tax implications.
NEW QUESTION # 193
President and sole shareholder of the Velos Tourisque company, Paul employs 50 people. Maryse, his financial security advisor, advises him to have his company take out life insurance on him. Who will be the parties to the contract?
Answer: B
Explanation:
Comprehensive and Detailed In-Depth Explanation: In a corporate-owned life insurance policy, the roles of policyholder, insured, and beneficiary must align with legal and insurable interest principles under the Civil Code of Quebec (Articles 2415-2419). The policyholder is the entity that owns and pays for the policy, the insured is the person whose life is covered, and the beneficiary receives the death benefit. Here, Velos Tourisque, the company, is taking out the policy on Paul, its key person, suggesting it will own the policy (policyholder) and benefit from the proceeds (beneficiary) to protect its financial interests-common in key person insurance. Paul, as the individual whose life is insured, is the insured. Option D correctly identifies Velos Tourisque as policyholder and beneficiary, with Paul as the insured. Option A misassigns Velos Tourisque as the insured (a company cannot be insured, only a person can). Option B incorrectlylists Velos Tourisque as the insured. Option C reverses the roles, making Paul the policyholder, which contradicts the company owning the policy. The Ethics and Professional Practice manual highlights advisors' duty to clarify these roles for clients.
References: Civil Code of Quebec, Articles 2415-2419; Ethics and Professional Practice (Civil Law) Manual, Section on Insurance Contract Parties.
NEW QUESTION # 194
(Julia deposited capital into an annuity contract that will start payments in three years and continue for
10 years. She is the annuitant; her son Ethan is the beneficiary.
What type of annuity has Julia purchased?)
Answer: A
Explanation:
Adeferred payout term annuityinvolves depositing funds now with payments starting after a deferment period (in Julia's case, 3 years) and continuing for a set term (10 years).
Exact Extract:
"A deferred payout annuity begins income payments after a specified deferment period. If a fixed period is selected, it is known as a term annuity." (Reference:Segfunds-E313-2020-12-7ED, Chapter 3.2.1.1 Payout Annuity)
NEW QUESTION # 195
......
In order to further strengthen your confidence to buy the LLQP Training Materials of us, we offer you 100% money back guarantee in case you fail the exam. The money will be refund to your account and no extra questions will be asked. Additionally, LLQP exam braindumps of us have helped many candidates pass the exam successfully with their high-quality. And we have professional technicians examine the update every day, and once we have new version, our system will send the latest version to your email automatically.
Detail LLQP Explanation: https://www.dumpsfree.com/LLQP-valid-exam.html
What's more, part of that DumpsFree LLQP dumps now are free: https://drive.google.com/open?id=1Z7T7EWNa_ow0Vj0BUmA-pckFuoyNEpvr