2026 Latest PassTestking AFP-Exam-1 PDF Dumps and AFP-Exam-1 Exam Engine Free Share: https://drive.google.com/open?id=1L-4blcm0U4mCoeQakP5dxXaK1PvgHLIS
With the simulation function, our AFP-Exam-1 training guide is easier to understand and have more vivid explanations to help you learn more knowledge. You can set time to test your study efficiency, so that you can accomplish your test within the given time when you are in the Real AFP-Exam-1 Exam. Besides, you can get the real feeling of taking part in the real exam for our AFP-Exam-1 exam questions have the function of simulating the real exam. So that you can have a better performance when you attend the real exam.
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Technical Competencies | 84% | - Retirement Planning - Asset and Liability Management - Tax Planning - Estate Planning - Risk Management and Insurance - Investment Planning |
In addition to the CSI AFP-Exam-1 PDF questions, we offer desktop Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) practice exam software and web-based Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) practice test to help applicants prepare successfully for the actual Building Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam. These Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) practice exams simulate the actual AFP-Exam-1 exam conditions and provide an accurate assessment of test preparation.
NEW QUESTION # 102
A client's portfolio target is 50% equities and 50% fixed income. After a strong equity market, the portfolio is now 68% equities. The client's circumstances and objectives have not changed. What should the planner recommend?
Answer: D
Explanation:
Portfolio drift changes risk. If the approved allocation is 50% equities and the current allocation is 68%, the portfolio now has materially more equity exposure than the client agreed to hold. Rebalancing restores the risk profile and imposes discipline after market movement. Option B is performance chasing; it uses recent returns as a reason to increase concentration without revisiting suitability. Option C overcorrects and may sacrifice the return required to meet long-term goals. Option D contradicts the monitoring function of an investment plan. A proper rebalancing recommendation should consider tax consequences, transaction costs, registered versus non-registered accounts, thresholds, and whether contributions or withdrawals can be directed to underweight asset classes. The rationale is not that equities are expected to fall. The rationale is that the client's portfolio should continue to reflect the documented objectives, constraints, and risk profile.
References/topics: rebalancing, portfolio monitoring, strategic allocation, risk discipline. Rebalancing thresholds should be stated before market movement occurs.
NEW QUESTION # 103
Rosa has just learned that her daughter Marissa, age 23, does not intend to return to university. She has been saving for her daughter's education since Marissa was 10 and is concerned there will be a significant tax liability. How should Rosa's financial planner advise her to utilize the funds when she redeems the RESP in order to offset the tax liability?
Answer: B
Explanation:
Rosa should transfer the RESP accumulated income payment, commonly referred to as growth, to her own RRSP if she has sufficient contribution room and the statutory conditions are met. When a beneficiary does not pursue qualifying post-secondary education, original contributions can usually be returned to the subscriber tax-free because they were made with after-tax dollars, while grants may have to be repaid. The taxable accumulated income is the problem. Transferring eligible AIP amounts to the subscriber's RRSP can defer or reduce the special tax that would otherwise apply. Depositing the growth or full balance into the daughter's RRSP is not the standard solution because Marissa may not have contribution room and the subscriber controls the RESP structure. Depositing the full balance into Rosa's RRSP is also inaccurate because contributions and grant amounts have different treatment. Study Guide focus: RESP withdrawals, accumulated income payments, RRSP rollover, grant repayment, and education planning.
NEW QUESTION # 104
William and Jennifer are selling their business which qualifies as a Canadian-controlled private corporation.
When the sale is complete at the end of this year, William and Jennifer will each receive $4 million for their common shares which have nominal cost. Jennifer has unused capital losses from previous years. They are meeting with Laurel, their financial planner, to discuss the tax implications of the sale. Based on the information provided, what should Laurel recommend to William and Jennifer so that they are best able to make use of the Lifetime Capital Gains Exemption?
Answer: A
Explanation:
William should claim the Lifetime Capital Gains Exemption, while Jennifer should first use her unused capital losses. The planning issue is not whether both shareholders own qualifying Canadian-controlled private corporation shares; they do. The deciding fact is Jennifer's unused capital losses. In the personal tax calculation, capital losses are applied against taxable capital gains before the capital gains deduction is used.
If Jennifer has available losses, claiming the LCGE may waste exemption room or fail to deliver the intended tax result because the losses already shelter some or all of her taxable capital gain. William has no stated capital-loss pool, so his large gain is the clean use of the exemption. Options that split the exemption or have Jennifer claim it ignore the ordering rules and the clue in the facts. The planner should coordinate the transaction with tax counsel and confirm QSBC eligibility, CNIL effects, and each spouse's remaining exemption room. Study Guide focus: qualified small business corporation shares, capital gains deduction, net capital losses, and LCGE planning.
NEW QUESTION # 105
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: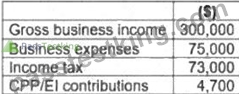
What is Terry's net business income?
Answer: A
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 106
Henri and Jessica have recently moved in together and Henri has been helping Jessica with her investments.
Jessica names Henri trading authority on her TFSA. Henri calls their financial planner requesting to make Jessica's TFSA contribution for this year but first requests the overall balance in Jessica's bank accounts (TFSA, high yield savings, chequing) to know if this is possible. What action would be most appropriate for their financial planner to take?
Answer: C
Explanation:
Henri's authority is limited to trading authority on Jessica's TFSA. That does not give him authority to receive information about Jessica's bank balances, high-interest savings account, chequing account, or broader financial position. Trading authority permits specific account instructions within its scope; it is not a privacy waiver and does not equal power of attorney. The planner must protect Jessica's confidentiality and require Jessica to contact the planner directly or provide proper written authorization. Providing the balances because Henri has some account authority would breach privacy and exceed the mandate. Allowing Henri to contribute from his own account introduces attribution and contribution-room issues and still does not authorize disclosure. Recommending an enduring POA is not the immediate response unless Jessica wants incapacity or management authority planning. Study Guide focus: client confidentiality, third-party authority, trading authorization, privacy, and account documentation. The same privacy standard applies even where the parties are spouses, partners, or informal helpers unless written authority exists.
NEW QUESTION # 107
......
If you can have the certification, you can enter the company you like as well as improve your salary. AFP-Exam-1 training materials of us can offer you such opportunity, since we have a professional team to compile and verify, therefore AFP-Exam-1 exam materials are high quality. You can pass the exam just one time. In addition, AFP-Exam-1 Exam Dumps contain both questions and answers, so that you can have a quick check after practicing. We offer you free update for one year, and the update version for AFP-Exam-1 exam materials will be sent to your email address automatically.
AFP-Exam-1 Exam: https://www.passtestking.com/CSI/AFP-Exam-1-practice-exam-dumps.html
P.S. Free & New AFP-Exam-1 dumps are available on Google Drive shared by PassTestking: https://drive.google.com/open?id=1L-4blcm0U4mCoeQakP5dxXaK1PvgHLIS