2026 Latest Pass4sures PF1 PDF Dumps and PF1 Exam Engine Free Share: https://drive.google.com/open?id=1FZBUDOSc3t1QZo3SsHX4bkNGjaUuPQ22
Just only dozens of money on National Payroll Institute PF1 latest study guide will assist you pass exam and 24-hours worm aid service. These National Payroll Institute PF1 test questions will help you secure the National Payroll Institute PF1 credential on the first attempt. We are aware that students face undue pressure during the National Payroll Institute PF1 certification exam preparation.
| Section | Objectives |
|---|---|
| Record of Employment | - ROE processing
|
| Non-Statutory Deductions | - Voluntary deductions
|
| Termination of Employment | - Termination processing
|
| Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Commission Payments | - Commission payroll processing
|
| Year-End Processing | - Federal and provincial year-end reporting
|
| Provincial Remittances | - Provincial payroll requirements
|
| Non-Regular Payments | - Special payroll payments
|
| Federal Remittances | - Government remittance obligations
|
| Employment Income – Regular Earnings | - Regular payroll calculations
|
| New Employee Information | - Employee setup and documentation
|
| Payroll Accounting | - Payroll accounting practices
|
| Workers’ Compensation | - Workers compensation administration
|
>> National Payroll Institute PF1 Exam Test <<
The Pass4sures Payroll Fundamentals 1Exam (PF1) exam dumps are ready for quick download. Just choose the right PF1 exam questions format and download it after paying an affordable Payroll Fundamentals 1Exam in PF1 Practice Questions charge and start this journey. Best of luck in the National Payroll Institute PF1 exam and career!!!
NEW QUESTION # 27
Phan was employed fromMarch 1, 1992throughJanuary 10, 2007. He was not a member of the organization' s pension plan. Calculate the number of years eligible for the$1,500.00portion of a retiring allowance.
Answer: C
Explanation:
The special$1,500transfer eligibility connected to retiring allowances is based specifically onyears (or part- years) of service before 1989where the employee hadno vested employer pension/DPSP benefitsfor those years. CRA explains that, in addition to the $2,000-per-year pre-1996 rule, you can also transfer an additional
$1,500 for each year or part-year before 1989that meets the vesting condition.
Phan's employment began in1992, which isafter 1989. Because he haszeroservice before 1989, there areno years that can qualify for the $1,500 portion-regardless of whether he belonged to a pension plan.
Therefore, the number of eligible years for the$1,500component is0(option A). Payroll must base this calculation on actual service dates, including any related-employer service if applicable, but here the start date alone makes the $1,500 portion ineligible.
NEW QUESTION # 28
The capital cost of an employer-owned vehicle includes:
Answer: A
Explanation:
For CRA automobile benefit purposes (standby charge on an employer-owned automobile), the "cost" used is the capital cost, which includes more than just the sticker price. CRA guidance states the cost includes the trade-in amount (if applicable), additions, and GST/HST and PST as part of the cost base used in the standby charge calculation.
Option D is the best match because it includes vehicle options/accessories, sales taxes, and additions that add to depreciation value. Importantly, CRA also notes that certain specialized equipment added to meet the requirements of a disabled person or employment (examples include heavy-duty suspension and power winches) is not considered part of the automobile's cost for standby charge purposes. This directly rules out options A and C, since they treat specialized equipment as part of capital cost. Option B is incorrect because CRA includes sales taxes (GST/HST and PST) in the cost base.
NEW QUESTION # 29
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.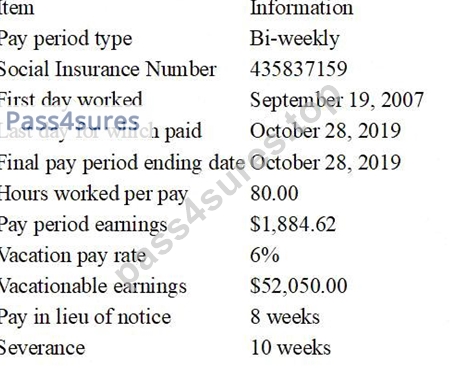
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)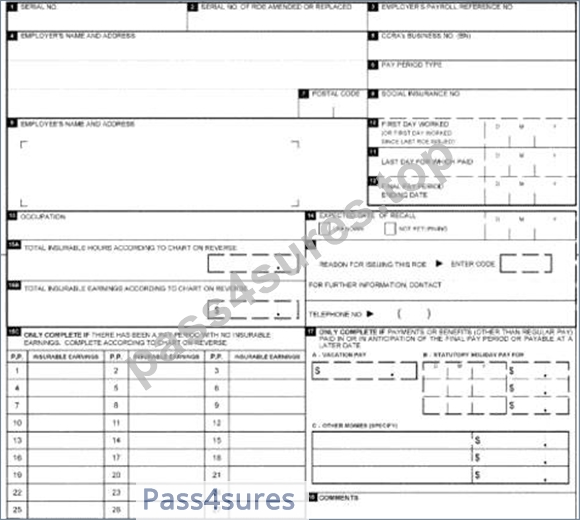
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 30
Which of the following situations would not require an employer to issue a Record of Employment?
Answer: D
Explanation:
An ROE is required when an employee experiences an interruption of earnings, such as 7 consecutive calendar days with no work and no insurable earnings (the "7-day rule"), or when earnings fall below 60% of regular weekly earnings for specific reasons (the "60% rule"). That means a 6-week unpaid leave (A) typically triggers an interruption of earnings, and a drop to 40% of normal earnings (B) meets the "below
60%" threshold (when due to the listed leave reasons). A layoff with no recall (D) also triggers an interruption of earnings under the 7-day rule.
However, Service Canada lists a special situation for a change in ownership: the former employer does not have to issue ROEs if (1) there is no actual break in the employee receiving earnings, and (2) payroll records are available to the new owner and the new owner agrees to issue a single ROE covering both periods if needed. That is exactly option C, so no ROE is required in that scenario.
NEW QUESTION # 31
Select the correct order of priority for withholding payroll deductions from an employee's earnings.
Answer: A
Explanation:
Payroll deductions are typically applied in a priority order to ensure the employer meets mandatory legal obligations first and avoids creating liability. Standard Canadian payroll training materials commonly present five categories withheld in this order: (1) statutory deductions, (2) legal deductions, (3) union deductions, (4) company-compulsory deductions, and (5) voluntary deductions.
Statutory deductions (CPP/QPP, EI, income tax, and where applicable NWT/Nunavut payroll tax) have top priority because employers are legally required to deduct and remit them.
Legal deductions (such as CRA requirements to pay/garnishments) are next because they are enforced by law and can create employer liability if not followed.
Union deductions follow where required by a collective agreement.
Company-compulsory deductions (for example, required benefit premiums) come after those.
Voluntary deductions (charity, savings plans, etc.) are last and only taken if funds remain.
Therefore, option D is the correct order.
NEW QUESTION # 32
......
The passing rate of our PF1 study materials is the issue the client mostly care about and we can promise to the client that the passing rate of our product is 99% and the hit rate is also high. Our PF1 study materials are selected strictly based on the real PF1 exam and refer to the exam papers in the past years. Our expert team devotes a lot of efforts on them and guarantees that each answer and question is useful and valuable. We also update frequently to guarantee that the client can get more PF1 learning resources and follow the trend of the times. So if you use our study materials you will pass the test with high success probability.
Valid PF1 Vce Dumps: https://www.pass4sures.top/Payroll-Fundamentals/PF1-testking-braindumps.html
P.S. Free & New PF1 dumps are available on Google Drive shared by Pass4sures: https://drive.google.com/open?id=1FZBUDOSc3t1QZo3SsHX4bkNGjaUuPQ22