Our PF1 exam questions are designed from the customer's perspective, and experts that we employed will update our PF1 learning materials according to changing trends to ensure the high quality of the PF1 practice materials. What are you still waiting for? Choosing our PF1 guide questions and work for getting the certificate, you will make your life more colorful and successful.
| Section | Objectives |
|---|---|
| Topic 1: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 2: Workers’ Compensation | - Workers compensation administration
|
| Topic 3: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 4: Commission Payments | - Commission payroll processing
|
| Topic 5: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 6: Record of Employment | - ROE processing
|
| Topic 7: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Topic 8: Provincial Remittances | - Provincial payroll requirements
|
| Topic 9: Non-Regular Payments | - Special payroll payments
|
| Topic 10: New Employee Information | - Employee setup and documentation
|
| Topic 11: Termination of Employment | - Termination processing
|
| Topic 12: Federal Remittances | - Government remittance obligations
|
| Topic 13: Payroll Accounting | - Payroll accounting practices
|
>> National Payroll Institute PF1 Valid Test Tips <<
Besides National Payroll Institute PF1 exam is popular, Cisco, IBM, HP and so on are also accepted by many people. If you want to get PF1 certificate, TrainingDump dumps can help you to realize your dream. Not having confidence to pass the exam, you give up taking the exam. You can absolutely achieve your goal by TrainingDump test dumps. After you obtain PF1 certificate, you can also attend other certification exams in IT industry. TrainingDump questions and answers are at your hand, all exams are not a problem.
NEW QUESTION # 64
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)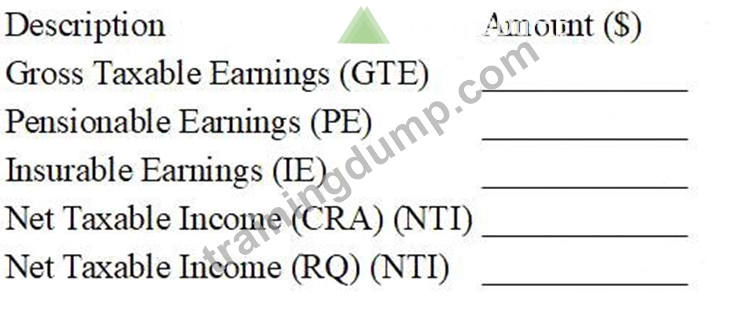
STATUTORY DEDUCTIONS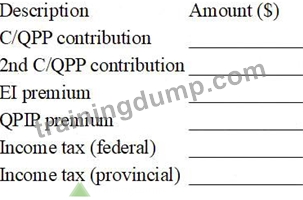
OTHER DEDUCTIONS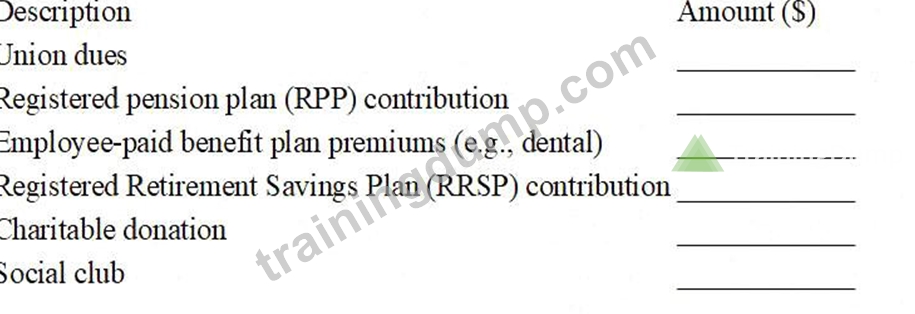
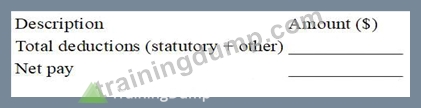
Given Data (Reference)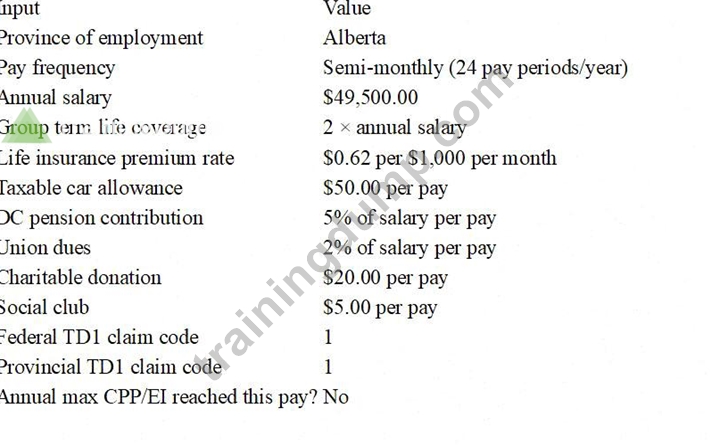
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 65
The Canada Revenue Agency form that is completed to allow a commissioned employee to claim non- reimbursed expenses at source is a:
Answer: C
Explanation:
The CRA form used to adjust payroll income tax withholdings at source for employees who earn commission income and have commission expenses is Form TD1X - Statement of Commission Income and Expenses for Payroll Tax Deductions. The CRA explains that an employee completes TD1X if they receive commission income (or salary plus commission) and want the employer to adjust tax deductions to take commission expenses into account.
This is different from:
TD1, which is the Personal Tax Credits Return used to claim basic/personal credits and determine standard withholding (not commission-expense adjustments).
T777, which is used to claim employment expenses on the employee's personal tax return (not to reduce payroll withholding at source).
TP-1015.R.13.1-V, which is a Quebec form used to request a reduction of Quebec income tax withholding in specific situations (not the CRA commission-expense at-source form).
Operationally, payroll should keep the TD1X on file and apply it to income tax withholding calculations until the employee updates or replaces it.
NEW QUESTION # 66
The capital cost of an employer-owned vehicle includes:
Answer: A
Explanation:
For CRA automobile benefit purposes (standby charge on an employer-owned automobile), the "cost" used is the capital cost, which includes more than just the sticker price. CRA guidance states the cost includes the trade-in amount (if applicable), additions, and GST/HST and PST as part of the cost base used in the standby charge calculation.
Option D is the best match because it includes vehicle options/accessories, sales taxes, and additions that add to depreciation value. Importantly, CRA also notes that certain specialized equipment added to meet the requirements of a disabled person or employment (examples include heavy-duty suspension and power winches) is not considered part of the automobile's cost for standby charge purposes. This directly rules out options A and C, since they treat specialized equipment as part of capital cost. Option B is incorrect because CRA includes sales taxes (GST/HST and PST) in the cost base.
NEW QUESTION # 67
Steve is physically disabled and his employer pays for his parking spot. This is considered:
Answer: A
Explanation:
Employer-provided parking is often a taxable benefit, generally valued at the fair market value of the parking spot. However, the CRA provides a specific exception for employees with disabilities. CRA guidance on employer-provided parking states that if your employee has a disability, the parking benefit is generally not taxable, including situations involving a severe and prolonged mobility impairment or blindness.
In Steve's case, the fact pattern explicitly says he is physically disabled and the employer pays for his parking.
Under CRA's general rule for disability-related parking, this would generally not be included in income as a taxable benefit, meaning it is not a taxable allowance and not a taxable benefit (cash or non-cash) for payroll purposes.
Payroll should still document why the parking is being treated as non-taxable (for example, disability-related need) and ensure the treatment aligns with CRA guidance if questioned. If the facts were different (non- disability parking or preferential parking provided to employees generally), the taxable benefit rules would usually apply.
NEW QUESTION # 68
In Block 6 of the Record of Employment, what pay period type is entered for employees who are paid salary plus regularly paid commission?
Answer: C
Explanation:
In Block 6 (Pay period type), Service Canada instructs employers to enter the employee's actual pay period type-one of the standard types such as weekly, biweekly, semi-monthly, monthly, or 13 pay periods a year.
Service Canada identifies a special rule only for employees "paid solely on commission or on salary plus irregularly paid commission": in those cases, the employer must use a weekly pay period and average earnings using the weekly averaging formula.
Because this question specifies salary plus regularly paid commission (not irregularly paid commission), the
"special situation" rule does not apply. Therefore, you enter the pay period type that matches the employer's normal payroll cycle for that employee (for example, weekly, biweekly, semi-monthly, monthly, etc.).
NEW QUESTION # 69
......
Free demo for PF1 training materials is available, and you can have a try before buying ,so that you can have a deeper understanding of what you are going to buy. We recommend you have a try before buying. In addition, PF1 exam materials contain most of knowledge points of the exam, and you can master major knowledge points as well as improve your professional ability in the process of learning. We also pass guarantee and money back guarantee for PF1 Training Materials , if you fail to pass the exam in your first attempt, we will give you full refund ,and no other questions will be asked.
Complete PF1 Exam Dumps: https://www.trainingdump.com/National-Payroll-Institute/PF1-practice-exam-dumps.html