What's more, part of that DumpsTorrent PF1 dumps now are free: https://drive.google.com/open?id=1OLJi_oBa6pdhbbRFjbnBRxwE0JsGH1gn
Propulsion occurs when using our PF1 preparation quiz. They can even broaden amplitude of your horizon in this line. Of course, knowledge will accrue to you from our PF1 training guide. There is no inextricably problem within our PF1 Learning Materials. Motivated by them downloaded from our website, more than 98 percent of clients conquered the difficulties. So can you as long as you buy our PF1 exam braindumps.
| Section | Weight | Objectives |
|---|---|---|
| Individual Pay Calculations | 40% | - Non-regular earnings
|
| Termination and Special Payments | 30% | - Leaves and absences
|
| Communication and Compliance | 10% | - Accuracy and documentation
|
| Record of Employment (ROE) | 20% | - Submission and deadlines
|
Many candidates like APP test engine of PF1 exam braindumps because it seem very powerful. If you are interested in this version, you can purchase it. This version provides only the questions and answers of PF1 exam braindumps but also some functions easy to practice and master. It can be used on any electronic products if only it can open the browser such as Mobile Phone, Ipad and others. If you always have some fear for the real test or can't control the time to finish your test, APP test engine of National Payroll Institute PF1 Exam Braindumps can set timed test and simulate the real test scene for your practice.
NEW QUESTION # 51
Paula is granted a pay increase. The paperwork informing the payroll department of the pay increase is two pay periods late. What method would be used to calculate income taxes on the separate retroactive payment?
Answer: C
Explanation:
A payment made to "catch up" wages because a pay increase was processed late is a retroactive payment. The CRA provides different income tax calculation approaches depending on the payment type and specifically lists "Retroactive payments" as its own category, separate from regular tax-table calculations, lump-sum, and bonus/irregular methods.
For bonuses and retroactive pay increases, the CRA also points employers to the Payroll Deductions Online Calculator (PDOC) to calculate CPP, EI, and income tax correctly, which aligns with using the appropriate CRA method for retroactive amounts.
Because this situation is explicitly a retroactive adjustment (two pay periods late), the correct choice is the Retroactive tax method (option C), not the bonus/irregular method, not the lump-sum method, and not the regular tax tables.
NEW QUESTION # 52
Which of the following is not correct?
Answer: C
Explanation:
Option A is not correct. Service Canada's ROE guidance for paper ROEs explains that if you need to complete Block 15C, you do that first, and then you still enter the total insurable earnings in Block 15B. It also reminds employers to include any insurable separation payments entered in Block 17 in both Block 15C (Pay Period 1) and Block 15B totals.
Option C is correct because retiring allowances (often treated as severance-type amounts) are not insurable, so even if they appear in Block 17C, they are not added to Blocks 15B/15C.
Option D is correct because vacation pay paid on separation is reported in Block 17A, and when it is insurable, it must be included in the insurable earnings totals in Block 15B (and Block 15C P.P.1 where applicable).
NEW QUESTION # 53
Raminder was hired in January 1997. He was fully vested in the organization's pension plan at the time he received the retiring allowance. His employment was terminated on May 1, 2006 and he was paid a
$10,000.00 retiring allowance. Calculate the eligible portion of the retiring allowance.
Answer: C
Explanation:
The "eligible portion" of a retiring allowance (the part that may be transferred directly to an RRSP/RPP on a tax-deferred basis without using regular RRSP room) is based on years of service before 1996 (and potentially an additional amount for certain pre-1989 years). CRA explains that the eligible part is: $2,000 for each year or part-year of service before 1996, plus an additional $1,500 for each year or part-year of service before 1989 only if no employer-funded pension/DPSP benefits for those years were vested (or previously paid out).
Raminder was hired in January 1997, so he has zero years (or part-years) of service before 1996, and therefore he has no base eligible amount under the $2,000-per-year rule. Because he also has no pre-1989 service, the additional $1,500-per-year rule does not apply either.
So, the eligible portion is $0, meaning none of the $10,000 retiring allowance is eligible (option D).
NEW QUESTION # 54
Jasmine works for a Saskatchewan employer and earns $500.00 weekly. Calculate her Employment Insurance (EI) premium.
Answer:
Explanation:
$8.15 (employee EI premium for the week)
Explanation:
For employees whose province of employment is outside Quebec (including Saskatchewan), EI premiums are calculated by multiplying the employee's insurable earnings by the employee EI premium rate for the year, up to the annual maximum insurable earnings. For 2026, the employee EI premium rate outside Quebec is $1.63 per $100 of insurable earnings (which is 1.63%).
Jasmine earns $500.00 weekly and (based on the question) we assume all earnings are insurable and she has not reached the annual maximum. Her EI premium is:
$500.00 × 1.63% = $500.00 × 0.0163 = $8.15.
This amount is deducted from the employee's pay and later remitted to the CRA as part of the employer's regular payroll remittance. The maximum insurable earnings for 2026 is $68,900, but at $500 per week she would only hit the maximum later in the year (if at all), so the weekly premium calculation above applies.
NEW QUESTION # 55
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)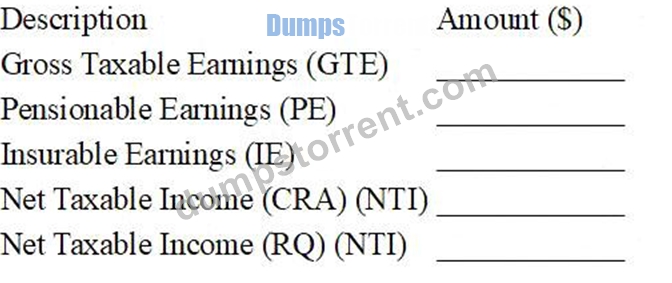
STATUTORY DEDUCTIONS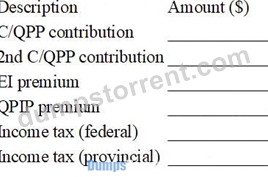
OTHER DEDUCTIONS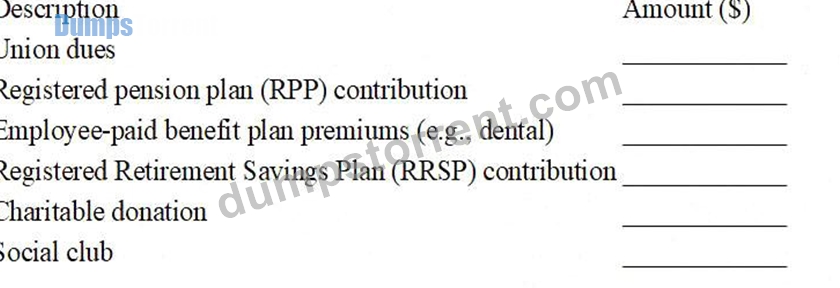
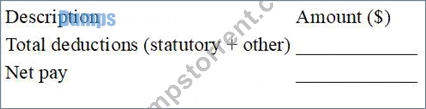
Given Data (Reference)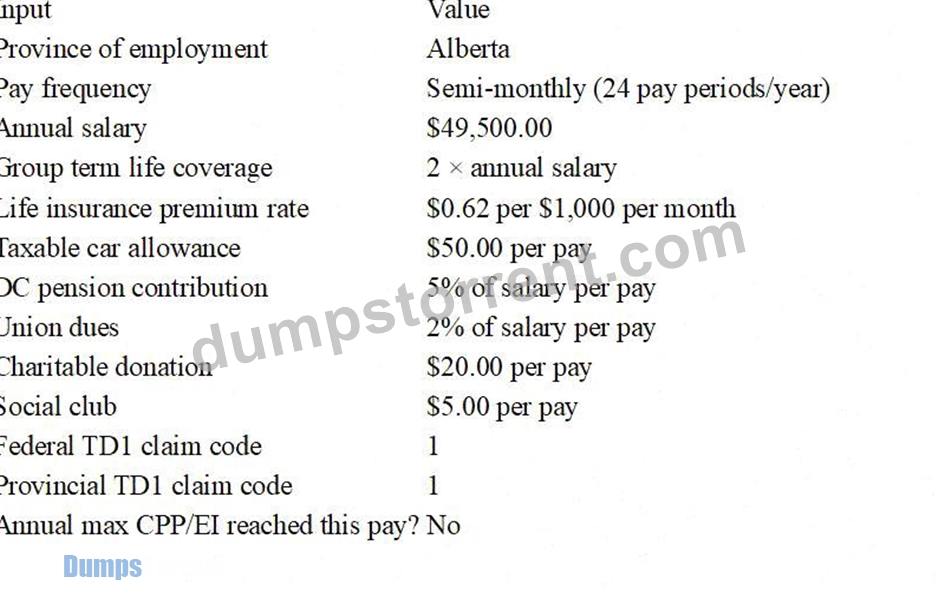
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 56
......
Our PF1 PDF file is portable which means customers can carry this real questions document to any place. You just need smartphones, or laptops, to access this Payroll Fundamentals 1Exam (PF1) PDF format. These Payroll Fundamentals 1Exam (PF1) questions PDFs are also printable. So candidates who prefer to study in the old way which is paper study can print PF1 PDF questions as well.
Actual PF1 Test Pdf: https://www.dumpstorrent.com/PF1-exam-dumps-torrent.html
BTW, DOWNLOAD part of DumpsTorrent PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1OLJi_oBa6pdhbbRFjbnBRxwE0JsGH1gn