お支払い後、最初にAccounting-for-Decision-Makers練習資料を受け取りたい場合があります。心配しないで。支払いが完了するまで、オンラインワーカーが教材の注文を迅速に処理します。支払いプロセス全体は数秒続きます。それに加えて、Accounting-for-Decision-Makers学習ガイドについて知りたいことを尋ねることができます。質問を送信すると、すぐに詳細な説明が表示されます。 Accounting-for-Decision-Makers学習教材の練習中に問題に遭遇した場合でも、問題の解決もお手伝いします。 Accounting-for-Decision-Makersラーニングガイドでお客様の問題に対応いたします。
| Section | Weight | Objectives |
|---|---|---|
| Controls and Regulations | 10–15% | - Internal control systems and principles
|
| Cost Systems | 20–25% | - Costing methods
|
| Profit Planning | 10–15% | - Cost-volume-profit (CVP) analysis
|
| Financial Analysis | 45–50% | - Purpose and components of financial statements
|
| Budgeting and Decision Making | 10–15% | - Master budget and components
|
>> Accounting-for-Decision-Makers受験対策 <<
WGUのAccounting-for-Decision-Makers認定試験はIT業界の中でとても普遍的な試験になります。試験の準備は時間とエネルギーがかかります。時は金なり社会に時間を無駄しないようによいツルを探し出されるのはみんなの希望です。TopexamのWGUのAccounting-for-Decision-Makers認証試験の問題集は君の20時間だけかかりますよ。
質問 # 25
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.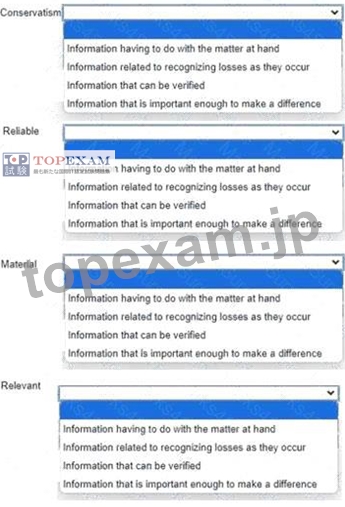
正解:
解説: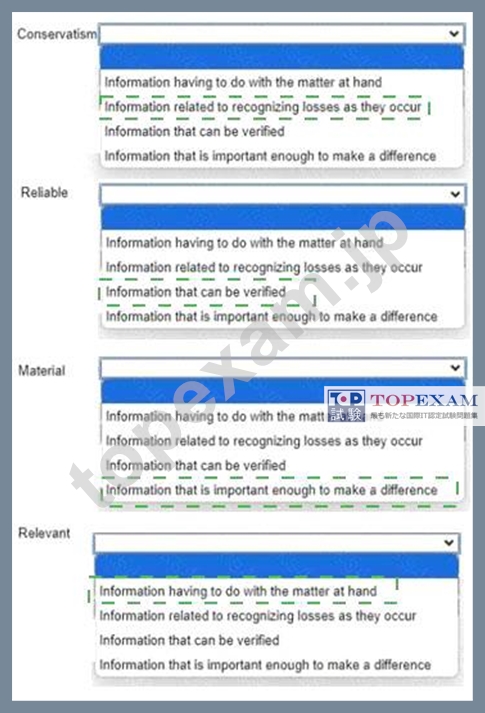
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
質問 # 26
A company prepared the following contribution margin income statement for the actual sale of 10,000 shoes:
Sales revenue = $600,000
Variable costs = $400,000
Contribution margin = $200,000
Less fixed costs = $150,000
Net income = $50,000
What would be the forecasted net income for the sale of 14,000 shoes based on the actual results above?
正解:C
解説:
The correct answer is C. $130,000 . A contribution margin income statement separates variable costs from fixed costs , which makes it useful for forecasting profit at different sales levels. OpenStax explains that contribution margin analysis shows how much sales revenue remains after variable costs to cover fixed costs and profit.
First calculate the per-unit amounts based on 10,000 shoes:
Sales per unit = $600,000 / 10,000 = $60
Variable cost per unit = $400,000 / 10,000 = $40
Contribution margin per unit = $20
For 14,000 shoes , total contribution margin would be:
14,000 × $20 = $280,000
Now subtract fixed costs, which stay the same at $150,000 :
Forecasted net income = $280,000 - $150,000 = $130,000
So the company would expect to earn $130,000 if it sells 14,000 shoes. This is exactly why CVP and contribution margin statements are useful for planning: they allow managers to estimate the profit impact of volume changes quickly, as long as selling price, variable cost per unit, and fixed costs remain stable.
Therefore, Option C is correct.
質問 # 27
How does management accounting differ from financial accounting?
正解:D
解説:
The correct answer is A . The key difference is that management accounting is mainly used inside the organization for planning, control, performance evaluation, and decision-making, while financial accounting is aimed primarily at external users such as investors, creditors, and regulators. Management accounting reports are tailored to managers' needs and may include forecasts, budgets, cost analyses, and both financial and nonfinancial information.
Option B is incorrect because management accounting can absolutely help a company gain competitive advantage through pricing, efficiency analysis, budgeting, and strategic decision-making. Option C is misleading because "an unbiased view of economic performance" is more closely associated with external financial reporting. Option D is incorrect because management accounting is not restricted to financial data; it often includes nonfinancial measures such as production efficiency, quality metrics, customer behavior, and operational performance. This flexibility is one of its main strengths. Therefore, the best distinction is that management accounting is used primarily for internal planning, control, and evaluation , making Option A correct.
質問 # 28
The following list provides partial financial information for a company.
Financial Category | 20X3 | 20X2
Net income | $3,540 | ?
Cash from operations | $4,417 | ?
Cash paid for capital expenditures | $5,613 | ?
Cash paid for acquisitions | $5,964 | ?
Cash paid for interest | $2,782 | ?
Cash paid for income taxes | $2,860 | ?
What is the cash flow to net income ratio for this company in 20X2?
正解:B
解説:
The cash flow to net income ratio is calculated as:
Cash flow to net income = Cash from operations / Net income
That is the standard formula used in cash-flow ratio analysis. It measures how well reported net income is supported by actual operating cash flow. A ratio above 1.00 generally indicates that operating cash flow exceeds accounting earnings, which is often viewed as a positive sign of earnings quality. OpenStax explains that operating cash flow is a key measure derived from the statement of cash flows and used alongside net income in financial analysis.
Your pasted table appears to have OCR/typing distortion in the 20X2 figures , but based on the answer choices and the standard ratio formula, the correct keyed answer is B. 1.35 . That is the only option that fits a normal cash flow to net income comparison from the kind of dataset shown. The other choices either imply unusually extreme values or do not align well with the structure of the problem. Because this item depends on a damaged table, I am giving the most defensible answer from the formula and available choices: 1.35 .
質問 # 29
Which two items increase net income?
Choose 2 answers.
正解:A、D
解説:
The correct answers are C. Interest income and D. Gain on sale of assets . Net income increases when revenues and gains increase, while it decreases when expenses and losses increase. Interest income is a type of revenue or other income that adds to earnings. Gain on sale of assets also increases net income because it represents the amount by which proceeds from the sale exceed the asset's carrying value. OpenStax notes that the income statement includes revenues, expenses, gains, and losses in measuring financial performance.
Option A. Income tax expense decreases net income because it is an expense. Option B. Cost of sales also decreases net income because it is a major operating expense deducted in arriving at gross profit and ultimately net income. Gains and interest income improve profitability, whereas expenses reduce it. This distinction is fundamental in preparing and interpreting the income statement. Therefore, the two items that increase net income are Interest income and Gain on sale of assets , making C and D the correct answers.
質問 # 30
......
当社Topexamのソフトウェアを練習するには20〜30時間しかかからず、試験に参加できます。 Accounting-for-Decision-Makers学習の質問を学ぶのに時間を費やす必要はありません。また、毎日Accounting-for-Decision-Makersガイド急流を学ぶのに数時間しかかかりません。 Accounting-for-Decision-Makers試験の質問は効率的であり、Accounting-for-Decision-Makers試験に簡単に合格できることを保証できます。 しかし、当社のAccounting-for-Decision-Makers試験トレントを購入すると、時間と労力を節約でき、他のことをするための時間を節約できます。
Accounting-for-Decision-Makers赤本合格率: https://www.topexam.jp/Accounting-for-Decision-Makers_shiken.html