P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by PDF4Test: https://drive.google.com/open?id=1wkKhdeXmkINkX23X3vd_JK8HdwN6q0sE
We constantly improve and update our PF1 study materials and infuse new blood into them according to the development needs of the times and the change of the trend in the industry. We try our best to teach the learners all of the related knowledge about the test PF1 Certification in the most simple, efficient and intuitive way. We pay our experts high remuneration to let them play their biggest roles in producing our PF1 study materials.
| Section | Objectives |
|---|---|
| Topic 1: Provincial Remittances | - Provincial payroll requirements
|
| Topic 2: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 3: Federal Remittances | - Government remittance obligations
|
| Topic 4: Non-Regular Payments | - Special payroll payments
|
| Topic 5: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 6: Record of Employment | - ROE processing
|
| Topic 7: Payroll Accounting | - Payroll accounting practices
|
| Topic 8: Commission Payments | - Commission payroll processing
|
| Topic 9: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Topic 10: Workers’ Compensation | - Workers compensation administration
|
| Topic 11: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 12: Termination of Employment | - Termination processing
|
| Topic 13: New Employee Information | - Employee setup and documentation
|
We have always been made rapid progress on our National Payroll Institute PF1 training materials because of the merits of high-efficiency and perfect after-sales services online for 24 hours. Studying with our PF1 Actual Exam, you can get the most professional information and achieve your dreaming scores by your first go.
NEW QUESTION # 64
A Third Party Demand is issued by the Canada Revenue Agency for:
Answer: A
Explanation:
A "Third Party Demand" in payroll collections commonly refers to the CRA's Demand on a Third Party (DTP)-a legal garnishment tool used to collect a person's debt to the government by requiring a third party (such as an employer or financial institution) to redirect funds that would otherwise be paid to the debtor.
CRA guidance explains that garnishments may be issued as a Requirement to Pay (RTP), Enhanced Requirement to Pay (ERTP), or Demand on a Third Party (DTP), and that these documents apply when money normally payable to someone who owes a debt to the government must instead be paid to the CRA (or other listed federal bodies).
This aligns with option B: unpaid income tax or unpaid statutory deductions (such as payroll source deductions) can lead to CRA collection action using these legal instruments.
Child support is generally enforced under provincial/territorial family support programs, not via CRA DTP as described here. Overpaid EI benefits are typically handled through EI/Service Canada recovery processes, and
"third-party creditor debt" is not a CRA-administered debt.
NEW QUESTION # 65
Bonus and incentive pays are subject to which statutory deductions?
Answer: C
Explanation:
Bonuses and incentives are treated as taxable remuneration, so they are generally subject to the same core statutory deductions as regular earnings: CPP/QPP, EI, and income tax (and in Quebec, QPIP also applies when the remuneration is subject to EI). The CRA specifically notes that you must deduct EI premiums from bonuses/retroactive pay (up to the annual maximum), and the CRA's guidance for bonuses/irregular amounts uses tools (PDOC/formulas) that calculate CPP contributions, EI premiums, and income tax on these payments.
In Quebec payroll, remuneration that is subject to EI premiums is generally also subject to QPIP premiums, so bonuses/incentives that are EI-insurable are typically QPIP-insurable as well.
In the Northwest Territories and Nunavut, there is also a statutory territorial payroll tax that employers must withhold/remit where applicable, and the NWT guidance explicitly lists bonuses as part of employment income subject to payroll tax.
NEW QUESTION # 66
The employee-employer relationship is deemed to be severed when:
Answer: B
Explanation:
In ROE administration, the key concept is whether the employment relationship is still "active" (that is, whether there is an ongoing expectation the employee will work again). Service Canada's ROE guidance ties ROE issuance to an interruption of earnings and specifically identifies situations where an employee is no longer on the employer's active employment list (for example, no expectation of future work) as a trigger for issuing an ROE.
Options A and B describe circumstances that can still align with an ongoing employment relationship. For example, employees may remain eligible for certain benefits after a last day worked, and a right to recall means the employer may still consider the employee attached to the workplace (often still "active" depending on the arrangement). In contrast, when there is no expectation of work to be performed, the relationship is effectively ended for ROE purposes, and the employer generally proceeds with separation reporting and ROE completion based on the interruption of earnings rules.
NEW QUESTION # 67
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
STATUTORY DEDUCTIONS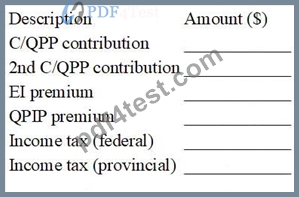
OTHER DEDUCTIONS

Given Data (Reference)
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 68
Charlene receives $50.00 each pay for her meals. This is an example of:
Answer: D
Explanation:
A fixed amount paid to an employee for meals each pay period is typically a meal allowance. CRA guidance distinguishes an allowance from a reimbursement: an allowance is usually a set amount paid without the employee having to submit receipts for actual costs, while a reimbursement repays specific expenses and is generally supported by receipts or an expense claim.
Because Charlene "receives $50.00 each pay for her meals," it is a flat amount, which aligns with an allowance rather than a reimbursement. Whether the allowance is taxable or non-taxable depends on the facts (for example, whether it is reasonable and paid under conditions CRA recognizes as non-taxable for certain travel situations). If it's not a reasonable travel allowance under CRA's exceptions, it is generally a taxable allowance and must be included in income with appropriate deductions.
So the correct classification is A (an allowance).
NEW QUESTION # 69
......
Our website is a pioneer in providing comprehensive National Payroll Institute dumps torrent because we have a group of dedicated IT experts who have more than 10 years of experience in the study of PF1 test questions and answers. They work in advance to make sure that our candidates will get latest and accurate PF1 Exam Prep materials. You will get PF1 passing score with the shortest duration for exam preparation.
PF1 Download: https://www.pdf4test.com/PF1-dump-torrent.html
What's more, part of that PDF4Test PF1 dumps now are free: https://drive.google.com/open?id=1wkKhdeXmkINkX23X3vd_JK8HdwN6q0sE