Itcertkr LLQP 최신 PDF 버전 시험 문제집을 무료로 Google Drive에서 다운로드하세요: https://drive.google.com/open?id=1S_Vr_P_378IsbsAhFaWp5ow-LwDJMoOU
Itcertkr를 선택함으로 여러분은 IFSE Institute 인증LLQP시험에 대한 부담은 사라질 것입니다.우리 Itcertkr는 끊임없는 업데이트로 항상 최신버전의 IFSE Institute 인증LLQP시험덤프임을 보장해드립니다.만약 덤프품질을 확인하고 싶다면Itcertkr 에서 무료로 제공되는IFSE Institute 인증LLQP덤프의 일부분 문제를 체험하시면 됩니다.Itcertkr 는 100%의 보장도를 자랑하며IFSE Institute 인증LLQP시험을 한번에 패스하도록 도와드립니다.
| Section | Objectives |
|---|---|
| Topic 1: Life Insurance | - Policy provisions and riders - Underwriting and risk classification - Life insurance products and policy types |
| Topic 2: Segregated Funds and Annuities | - Annuity structures and guarantees - Investment-linked insurance products |
| Topic 3: Accident and Sickness Insurance | - Health insurance principles - Disability and critical illness coverage |
| Topic 4: Ethics and Professional Practice | - Ethical conduct and suitability - Regulatory framework and compliance |
많은 분들은IFSE Institute LLQP인증시험이 아주 어려운 것은 알고 있습니다. 하지만 우리Itcertkr를 선택함으로IFSE Institute LLQP인증시험은 그렇게 어렵지 않다는 것을 알게 될 것입니다. Pass4Tes의IFSE Institute LLQP합습가이드는 시험의 예상문제부터 전면적이로 만들어진 아주 퍼펙트한 시험자료입니다. 우리의 서비스는IFSE Institute LLQP구매 후 최신버전이 업데이트 시 최신문제와 답을 모두 무료로 제공합니다.
질문 # 141
(Joe and Joy, both aged 65, have $280,000 in savings and a $200,000 joint first-to-die life insurance policy. They want to buy an annuity to provide steady income in retirement.
What type of annuity would best suit their needs?)
정답:D
설명:
Ajoint life annuitythat pays50% to the surviving spouseensures continuous but reduced income after the first death, matching their needs for steady, predictable income while still protecting the surviving spouse.
Exact Extract:
"A joint life annuity continues to pay income after the first death, either fully or at a reduced percentage (e.g.,
50%). This arrangement provides income security for a surviving spouse." (Reference:Segfunds-E313-2020-12-7ED, Chapter 3.2.2.2 Joint Life Contract)
질문 # 142
Harold is a 66-year-old retired school bus mechanic. He receives $900 a month from his defined benefit pension plan (DBPP). His husband Karl is also retired and receives his own pension benefit. Harold would like to know the minimum monthly pension benefit from his DBPP that Karl will receive upon Harold's death.
정답:C
설명:
Defined Benefit Pension Plans (DBPPs) provide a guaranteed income stream to the plan member after retirement, based on a formula considering factors like years of service and salary history. Generally, unless explicitly set up with survivor benefits, DBPPs do not automatically transfer income to a surviving spouse upon the member's death. In Harold's case, if no survivor benefit option was selected during retirement setup, Karl would not receive any income from Harold's DBPP. Therefore, the correct answer isA. $0as no automatic provision ensures Karl receives benefits unless Harold had chosen and paid for survivor benefits.
질문 # 143
(Samuel works for a major company offering a GRRSP and a group TFSA.
How do Samuel's contributions to the GRRSP differ from his contributions to the group TFSA?)
정답:C
설명:
Group TFSA contributionsare made withafter-tax moneyand grow tax-free.GRRSP contributionsreduce taxable income immediately because they aretax-deductible.
Exact Extract:
"Contributions to a TFSA are not deductible and must be made with after-tax dollars. RRSP (andGRRSP) contributions are tax-deductible, reducing taxable income." (Reference:Segfunds-E313-2020-12-7ED, Chapter 1.3.11 Group Plans)
질문 # 144
(Jack is starting a new job with group medical, dental, and retirement benefits. He submits his application but is told he is not immediately eligible.
When might Jack become eligible?)
정답:D
설명:
Most group benefits, including medical, dental, and retirement plans, require employees to complete a standard waiting period(e.g., 3 months) before they become eligible for enrollment.
Exact Extract:
"Group insurance plans often impose a standard waiting period before new employees become eligible for coverage." (Reference:Sickness-E312-2020-12-7ED, Chapter 2.3.3.1 Qualification Period#45:3 Sickness-E312-2020-12-
7ED.pdf**)
질문 # 145
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
정답:A
설명:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence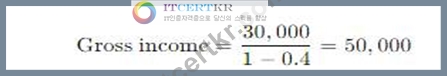
Calculate Required Capital for Income Replacement:
Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence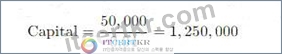
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
질문 # 146
......
Itcertkr는 자격증 응시자에게IFSE Institute LLQP 시험 준비를 위한 현재 그리고 가장 최근의 자료들을 제공하는 이 산업 영역의 리더입니다. Itcertkr는IFSE Institute LLQP덤프를 시험문제변경에 따라 계속 갱신하여 고객님께서 받은 것이IFSE Institute LLQP 시험의 가장 최신 기출문제임을 보증해드립니다.
LLQP인기덤프자료: https://www.itcertkr.com/LLQP_exam.html
참고: Itcertkr에서 Google Drive로 공유하는 무료, 최신 LLQP 시험 문제집이 있습니다: https://drive.google.com/open?id=1S_Vr_P_378IsbsAhFaWp5ow-LwDJMoOU