Perhaps you are in a bad condition and need help to solve all the troubles. Don’t worry, once you realize economic freedom, nothing can disturb your life. Our AFP-Exam-1 exam questions can help you out. Learning is the best way to make money. So you need to learn our AFP-Exam-1 guide materials carefully after you have paid for them. And in fact, our AFP-Exam-1 Practice Braindumps are quite interesting and enjoyable for our professionals have compiled them carefully with the latest information and also designed them to different versions to your needs.
| Section | Objectives |
|---|---|
| Retirement Planning | - Retirement savings vehicles and planning principles |
| Taxation Concepts | - Personal income tax principles - Tax-efficient investment strategies |
| Financial Planning Foundations | - Financial planning process and client relationship management - Ethics and professional standards in financial advising |
| Investment Planning | - Asset allocation and portfolio basics - Investment products and risk-return profiles |
| Insurance and Risk Management | - Risk mitigation strategies in financial planning - Life and health insurance fundamentals |
>> Current AFP-Exam-1 Exam Content <<
We update the AFP-Exam-1 study materials frequently to let the client practice more and follow the change of development in the practice and theory. So that our worthy customers can always receive the most updated and the latest AFP-Exam-1 learning guide. And according to our service, you can enjoy free updates for one year after you pay for the AFP-Exam-1 Exam Questions. So if we update it, then we will auto send it to you. You won't miss any information that you need to pass the exam.
NEW QUESTION # 107
Leena and Harry are married and hold RRSPs with a value exceeding $500,000. They are concerned about their final tax liability and want to cover the taxes after they have both died. What would their financial planner recommend them to implement in order for the couple to achieve the objective?
Answer: B
Explanation:
A joint last-to-die permanent life insurance policy is designed for a tax liability that arises after both spouses have died. Leena and Harry are concerned about the final tax exposure on large RRSP balances. If one spouse dies first and the surviving spouse is the beneficiary or successor annuitant, RRSP/RRIF amounts may generally roll to the survivor on a tax-deferred basis. The larger tax problem usually appears on the second death, when no spouse remains for rollover and the registered assets are included in income. Last-to-die coverage pays at that point and can provide estate liquidity for taxes without forcing asset sales. A testamentary trust does not itself fund the tax bill. Updating beneficiaries to each other helps deferral but not the final liability. An inter vivos trust cannot simply receive RRSP assets without tax consequences. Study Guide focus: RRSP/RRIF death taxation, spousal rollover, permanent insurance, estate liquidity, and last-to- die planning.
NEW QUESTION # 108
Gina plans to take a one-year leave of absence from her employer without pay. Gina has a TFSA invested in equity mutual funds which is currently below book value, an RRSP invested in cash, a Nova Scotia LIRA invested in GICs, and a line of credit. Assuming all have sufficient funds, which plan should Gina access to ensure she meets her goal of budget effectiveness during this time?
Answer: B
Explanation:
Gina needs a practical cash-flow source for a one-year unpaid leave. The LIRA is generally locked in and unavailable for ordinary spending. A line of credit would meet the cash need but would add interest expense and weaken the budget during a period with no salary. Her TFSA is invested in equity mutual funds below book value, so redeeming it would crystallize a market loss and remove the possibility of recovery inside the TFSA. The RRSP is already in cash and Gina's income during the leave will be low, making the withdrawal less tax-costly than it would be in a normal salary year. Although RRSP withdrawals are taxable and reduce retirement assets, in the specific fact pattern it is the best budget-effectiveness choice among the available sources. The planner should still calculate withholding tax and the minimum amount required. Study Guide focus: source-of-funds analysis, registered accounts, LIRA restrictions, tax brackets, and cash-flow planning.
NEW QUESTION # 109
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.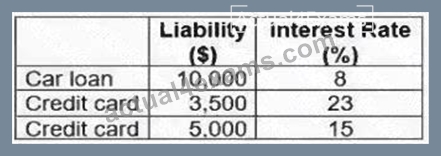
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: A
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 110
Huxley is meeting with his financial planner to review his retirement goals. He has saved $250,000 in an RRSP, currently contributes $10,000 per year, and his portfolio is expected to continue to earn an average of
5% per year. Huxley is hoping to retire in 18 years with $1 million saved in his RRSP. What strategy should Huxley's financial planner recommend to ensure he is on track?
Answer: D
Explanation:
Huxley is not on track under the existing assumptions. His $250,000 RRSP growing at 5% for 18 years, plus
$10,000 annual contributions at the same return, accumulates to approximately $883,000, not $1,000,000. The shortfall is about $117,000 at the target date. Increasing monthly contributions by $350 produces additional future value that is sufficient to close the gap without relying on a much higher risk profile or delaying retirement. Raising the goal to $1,250,000 makes the gap worse. Extending retirement to 25 years may solve the math but changes the client's stated retirement objective. Targeting 12% return is aggressive and may be unsuitable; a planner should not fix a savings gap by assuming unrealistic risk. The most controlled recommendation is higher contributions. Study Guide focus: RRSP accumulation, future value, savings shortfall, contribution planning, and retirement goal feasibility. This keeps the recommendation inside controllable client behaviour rather than relying on market returns outside the planner's control.
NEW QUESTION # 111
A retiree holds most of her investments in interest-bearing GICs inside a non-registered account while her TFSA is invested in cash. She has unused TFSA room and wants to improve after-tax efficiency without increasing total portfolio risk materially. What should the planner consider?
Answer: C
NEW QUESTION # 112
......
Getting the CSI AFP-Exam-1 certification exam is necessary in order to get a job in your desired tech company. Success in the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) certification exam gives you an edge over the others because you will have certified skills. The CSI AFP-Exam-1 certification exam badge will make a good impression on the interviewer. Most of the people planning to attempt the AFP-Exam-1 Exam are confused that how will they prepare and pass AFP-Exam-1 exam with good grades. Many don't find real AFP-Exam-1 exam questions and face loss of money and time.
AFP-Exam-1 Actual Questions: https://www.actual4exams.com/AFP-Exam-1-valid-dump.html