In order to save a lot of unnecessary trouble to users, we have completed our AFP-Exam-1 Learning Materials research and development of online learning platform, users do not need to download and install, only need your digital devices have a browser, can be done online operation of the AFP-Exam-1 study materials. This kind of learning method is very convenient for the user, especially in the time of our fast pace to get CSI certification. In addition, our test data is completely free of user's computer memory, will only consume a small amount of running memory when the user is using our product.
| Section | Objectives |
|---|---|
| Topic 1: Taxation Concepts | - Personal income tax principles - Tax-efficient investment strategies |
| Topic 2: Retirement Planning | - Retirement savings vehicles and planning principles |
| Topic 3: Investment Planning | - Investment products and risk-return profiles - Asset allocation and portfolio basics |
| Topic 4: Insurance and Risk Management | - Risk mitigation strategies in financial planning - Life and health insurance fundamentals |
| Topic 5: Financial Planning Foundations | - Ethics and professional standards in financial advising - Financial planning process and client relationship management |
>> AFP-Exam-1 Valid Real Exam <<
Our AFP-Exam-1 exam materials are formally designed for the exam. With its help, you don't have to worry about the exam any more for it almost guarantees you get what you want. If you think i'm exaggerating, you might as well take a look at our AFP-Exam-1 Actual Exam. With a high pass rate as 98% to 100%, you will be bound to pass the exam. And our AFP-Exam-1 training questions are popular in the market. We believe you will make the right choice.
NEW QUESTION # 35
Huxley is meeting with his financial planner to review his retirement goals. He has saved $250,000 in an RRSP, currently contributes $10,000 per year, and his portfolio is expected to continue to earn an average of
5% per year. Huxley is hoping to retire in 18 years with $1 million saved in his RRSP. What strategy should Huxley's financial planner recommend to ensure he is on track?
Answer: A
Explanation:
Huxley is not on track under the existing assumptions. His $250,000 RRSP growing at 5% for 18 years, plus
$10,000 annual contributions at the same return, accumulates to approximately $883,000, not $1,000,000. The shortfall is about $117,000 at the target date. Increasing monthly contributions by $350 produces additional future value that is sufficient to close the gap without relying on a much higher risk profile or delaying retirement. Raising the goal to $1,250,000 makes the gap worse. Extending retirement to 25 years may solve the math but changes the client's stated retirement objective. Targeting 12% return is aggressive and may be unsuitable; a planner should not fix a savings gap by assuming unrealistic risk. The most controlled recommendation is higher contributions. Study Guide focus: RRSP accumulation, future value, savings shortfall, contribution planning, and retirement goal feasibility. This keeps the recommendation inside controllable client behaviour rather than relying on market returns outside the planner's control.
NEW QUESTION # 36
Mark, a financial planner, is meeting his client Adam for the first time. From the conversation, Mark learned that Adam has some experience on trading stocks. Adam asked Mark to explain about efficient market theory that he overheard a colleague talking about a few days ago. How should Mark respond to Adam's question in simple terms?
Answer: A
Explanation:
The efficient market explanation that fits Adam's request is the semi-strong form: security prices already reflect publicly available information. Mark should keep the response simple because Adam asked for a plain- language explanation, not a technical lecture on market microstructure. The point is that, in an efficient market, new information is incorporated into prices quickly, making it difficult for investors to consistently earn abnormal returns from information that the market already knows. Option B describes learning from past mistakes, which is not efficient market theory. Option C is too absolute; price history may be analyzed by technicians, but the theory focuses on information efficiency rather than saying past prices have no relation to anything. Option D describes behavioural variation among investors, not the core theory. AFP investment planning uses this concept to distinguish passive market exposure from active security selection. Study Guide focus: efficient markets, passive investing, market information, and investment philosophy.
NEW QUESTION # 37
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: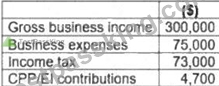
What is Terry's net business income?
Answer: D
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 38
James is visiting Gurjeet, his financial planner, to discuss his financial affairs after the recent passing of his long-time partner Peter. James is concerned that the cost of probate will be a heavy burden. Which holdings should Gurjeet advise James are included in calculating the cost of probate?
Answer: B
Explanation:
Probate is generally calculated on assets that form part of the deceased's estate. A tenancy in common interest is owned by the deceased as a separate property interest and does not pass automatically to the other owner by survivorship. It is therefore included in the estate unless another legal arrangement applies. Insurance contracts with a preferred or named beneficiary usually pay directly to the beneficiary. Assets held in a formal irrevocable trust are owned by the trust, not personally by the deceased. Registered plans with a valid adult child beneficiary designation generally bypass the estate, although tax consequences may still arise on the deceased's terminal return. Gurjeet should distinguish probate inclusion from income tax inclusion; an asset may bypass probate and still create tax. For the probate-cost question, the tenancy in common holding is the correct inclusion. Study Guide focus: probate property, beneficiary designations, trusts, joint ownership, and estate administration.
NEW QUESTION # 39
Tom has two children from a previous marriage. He has been paying $1,000 per month for spousal support and $1,500 per month for child support to his ex-wife. Recently, his ex-wife was awarded increased child support payments from Tom to cover unanticipated university expenses for one of the children. What should Tom's financial planner advise him about how this increased monthly payment may impact his finances?
Answer: B
Explanation:
The increased child support payment reduces Tom's net cash flow by the full amount. Under the standard tax treatment, child support is not deductible to the payer and is not taxable to the recipient. That differs from qualifying periodic spousal support, which may be deductible to the payer and taxable to the recipient when the legal requirements are met. Because the increased amount relates to child support for university expenses, Tom receives no tax deduction and no offsetting tax credit merely because he pays more. The tuition tax credit belongs to the eligible student unless transferred under applicable rules; it is not automatically applied to Tom because he pays support. The planner should update Tom's cash-flow plan, debt ratios, retirement savings ability, and emergency reserve using the full increased payment. Study Guide focus: child support, spousal support, tax deductibility, cash-flow planning, and separation agreements. This distinction is essential when modelling separation settlements because gross payments and after-tax cost can differ sharply.
NEW QUESTION # 40
......
In a year after your payment, we will inform you that when the AFP-Exam-1 exam guide should be updated and send you the latest version. Our company has established a long-term partnership with those who have purchased our AFP-Exam-1 exam questions. We have made all efforts to update our products in order to help you deal with any change, making you confidently take part in the AFP-Exam-1 Exam. Every day they are on duty to check for updates of AFP-Exam-1 study materials for providing timely application. We also welcome the suggestions from our customers, as long as our clients propose rationally.
AFP-Exam-1 Valid Test Questions: https://www.testpassking.com/AFP-Exam-1-exam-testking-pass.html