P.S. Free 2026 Guidewire ClaimCenter-Business-Analysts dumps are available on Google Drive shared by ExamsLabs: https://drive.google.com/open?id=1ReNnxDDv52ITJh-JljZFpB64FBw0hTDo
Authorized test ClaimCenter Business Analyst - Mammoth Proctored Exam dumps Premium Files Test Engine pdf. Updated ClaimCenter-Business-Analysts training topics with question explanations. Free practice Guidewire study demo with reasonable exam price. Guaranteed ClaimCenter-Business-Analysts Questions Answers 365 days free updates. pass ClaimCenter-Business-Analysts exam with excellect pass rate. Positive feedback fromExamsLabs's customwrs. ClaimCenter-Business-Analysts sample questions answers has regualer updates.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
>> ClaimCenter-Business-Analysts Examcollection Questions Answers <<
ExamsLabs ClaimCenter Business Analyst - Mammoth Proctored Exam (ClaimCenter-Business-Analysts) questions in three formats are the go-to source for successful and quick preparation. Three formats of our study material are Guidewire ClaimCenter-Business-Analysts exam PDF questions, desktop practice test software, and web-based ClaimCenter-Business-Analysts practice test. The philosophy behind offering these formats is simple: to create a world-class learning material that can help candidates achieve their ClaimCenter Business Analyst - Mammoth Proctored Exam (ClaimCenter-Business-Analysts) preparation objectives. With the help of ClaimCenter-Business-Analysts exam questions in three formats, you can prepare successfully for the test according to your style.
NEW QUESTION # 17
Succeed Insurance has a strategic initiative to offer pay-as-you-drive personal auto insurance to compete with other large carriers. Customers who choose these policies must either own a vehicle that is equipped with a monitoring device or agree to install a device provided by Succeed. The monitoring device collects information about how the drivers of a covered vehicle drive, including how fast they drive, how hard they brake, and how many miles/kilometers the vehicle travels within a policy period.
This information is logged, and premiums are based on how the insured's driving behavior is categorized.
When a claim is reported, the log files must be obtained in order to
analyze the information captured by the monitoring device at the time of the incident.
Succeed plans to collect and evaluate the Vehicle Monitoring Log files in the first implementation phase, which is scheduled for release in 60 days. The project sponsors have instructed the implementation team to use base product functionality over customization. Integration should be leveraged where possible to avoid manual data entry.
The New Claim Wizard must capture whether or not the vehicle has a monitoring device installed when a personal auto claim is created against a pay-as-you-drive policy.
Which feature of the base product enforces this claim creation requirement?
Answer: A
Explanation:
In Guidewire ClaimCenter, Validation Rules are used to enforce data integrity and business requirements at specific stages of the claim lifecycle. These stages are defined by Validation Levels.
* New Loss Completion (Option B):This validation level is specifically designed as the "gatekeeper" for the New Claim Wizard (FNOL). Rules triggered at this level run when the user attempts to click
"Finish" to submit the new claim. If a rule fails (e.g., "If Policy Type = Pay-as-you-drive AND Monitoring Device is Null"), the system prevents the claim from being created and highlights the missing field. This directly meets the requirement to enforce data capture "when a personal auto claim is created." Why other options are incorrect:
* Ability to Pay (A):This level runs when a user tries to issue a check. Using this would allow the claim to be createdwithoutthe device info, only blocking the user later when they try to pay, which is too late for the requirement.
* Custom Level (C):Creating custom levels is possible but discouraged when a standard level fits the purpose, aligning with the "use base product functionality" principle.
* Load and Save (D):This level runs every time the claim is saved (even as a draft). Enforcing mandatory fields here can frustrate users who need to save their work partially complete.
NEW QUESTION # 18
A car accident in a rural area of Durango, Colorado is reported to Succeed Insurance. The driver of the damaged car reportedly hit the base of a windmill tower while driving at night. There was no other passenger in the car when the accident happened, and the driver has a valid auto policy on file.
While the driver is not physically injured, the entire passenger side of the car has been severely damaged.
Although the windmill is still functioning, the base of the tower has sustained multiple broken parts.
Which two incidents need to be created for the claim based on the reported accident? (Choose two.)
Answer: A,C
Explanation:
In Guidewire ClaimCenter, an Incident is the data object used to capture the specific facts about "what" was damaged or affected during the loss event. It serves as the foundation for creating Exposures (the financial liabilities).
* Vehicle Incident (Option C):The scenario states that the insured's car has been "severely damaged" on the passenger side. To record these facts-including the point of impact, the severity, and the vehicle description-the Adjuster must create aVehicle Incident. This incident will eventually support the collision coverage exposure.
* Property Incident (Option B):The accident involved the car hitting a "windmill tower," resulting in
"broken parts" to the base. In ClaimCenter, damage to third-party non-vehicular objects (like fences, poles, buildings, or towers) is captured using aFixed Property Incident(often referred to generically as a Property Incident). This incident records the damage description and ownership of the windmill, which is necessary to handle the Property Damage Liability claim.
Why other options are incorrect:
* Option E (Injury):The scenario explicitly states the driver is "not physically injured." Therefore, an Injury Incident is not required.
* Option A ("Another structure"):The standard object for third-party fixed property damage is the Property Incident/Fixed Property Incident, not "Another structure."
* Option D (Loss of Use):While possible later, the primary immediate damage is physical. Loss of Use is usually a secondary exposure type, not the primary incident definition for the tower itself.
NEW QUESTION # 19
What two pieces of information enable the Business Analyst (BA) to trace back to the root cause of an issue?
(Choose two.)
Answer: B,D
Explanation:
In Guidewire implementation methodology (Agile/SurePath), Traceability is maintained through specific unique identifiers that link the code and test cases back to the business definition.
* Unique Requirement Numbers (Option E):Every granular business requirement is assigned a unique ID (e.g., CC-FNOL-001). If a defect or issue arises during testing or production, the BA uses this number to find the exact text of the requirement that was implemented. This helps determine if the issue is a "bug" (code doesn't match requirement) or a "gap" (requirement was missing or wrong).
* Unique Story Card Number (Option A):User Stories act as containers for requirements. The Story Card Number (e.g., Story-105) links the individual requirements to the broader feature context. Tracing back to the Story Card allows the BA to review the original scope, the UI mockups, and the Acceptance Criteria associated with that feature to understand the "Root Cause" of the misunderstanding or failure.
Why other options are incorrect:
* Option B (Caution points):These are process diagrams notes, useful for training but not for system traceability.
* Option C (Change History):While useful for seeingwhoedited a document, it does not provide the structural link between a system error and the business definition like the IDs do.
* Option D (Approver Notes):These confirm sign-off but rarely contain the functional detail needed to diagnose a root cause.
NEW QUESTION # 20
A claim for an auto accident in California has been assigned to an insurance Adjuster in the Midwest region for investigation and processing. The claim has been flagged as "Low Complexity" in ClaimCenter. The Adjuster has an authority limit for total reserves of $30,000 and has created reserves totaling $35,000.
What is the correct approval routing for this transaction?
Answer: A
Explanation:
Based on theGuidewire ClaimCenter Financials and Authority Limitsdocumentation, the correct behavior for this scenario is determined by the strict enforcement ofAuthority Limits, regardless of claim complexity or geographic region.
In ClaimCenter, every user is assigned specific authority limits for various financial transactions, including reserves, payments, and recovery reserves. These limits are absolute constraints designed to control financial exposure. In the scenario provided, the Adjuster attempted to set a reserve of$35,000, which exceeds their authorized limit of$30,000.
When a user submits a financial transaction that exceeds their pre-configured authority limit, ClaimCenter automatically triggers anApproval Workflow. The system validates the transaction amount against the user's limit at the time of submission. Since the limit is breached, the transaction is not committed immediately to the database as "Submitted"; instead, it enters a"Pending Approval"status.
Routing Logic:
The standard, out-of-the-box approval routing logic in ClaimCenter follows the Group Hierarchy.
* The system identifies the group to which the Adjuster belongs.
* It creates anApproval Activity.
* This activity is assigned to theSupervisorof that group.
The Supervisor must then review the transaction. If the Supervisor has sufficient authority (greater than
$35,000), they can approve it. If the Supervisor also lacks sufficient authority, they must still "approve" it to escalate the request further up the hierarchy totheirmanager, until it reaches a user with sufficient limits.
Why other options are incorrect:
* A (Complexity):Claim complexity flags (e.g., "Low Complexity") are often used forAssignmentrules (Segment-based assignment) or straight-through processing ofdocuments, but they do not override Financial Authoritycontrols. A low-complexity claim still requires financial oversight if the dollar amount is high.
* B (Peer Approval):Approval routing is hierarchical, not peer-to-peer. It does not look for "any" team member; it looks specifically for the defined Supervisor.
* C (Region):The region mismatch might trigger an assignment rule or a validation warning depending on configuration, but the specific trigger for theapprovalhere is purely the financial discrepancy ($35k
> $30k), not the geography.
NEW QUESTION # 21
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.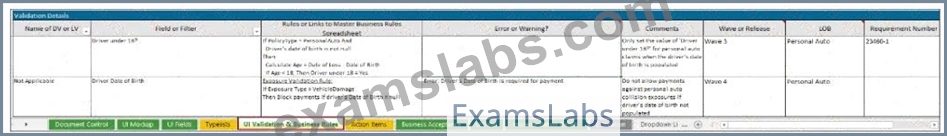
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: A,D
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 22
......
Maybe now you are leading a quite comfortable life. But you also need to plan for your future. Getting the ClaimCenter-Business-Analysts training guide will enhance your ability. Also, various good jobs are waiting for you choose. Your life will become wonderful if you accept our guidance on ClaimCenter-Business-Analysts study questions. We warmly welcome you to try our free demo of the ClaimCenter-Business-Analysts preparation materials before you decide to purchase.
Latest ClaimCenter-Business-Analysts Test Practice: https://www.examslabs.com/Guidewire/Guidewire-Certified-Professional/best-ClaimCenter-Business-Analysts-exam-dumps.html
P.S. Free 2026 Guidewire ClaimCenter-Business-Analysts dumps are available on Google Drive shared by ExamsLabs: https://drive.google.com/open?id=1ReNnxDDv52ITJh-JljZFpB64FBw0hTDo