It is a universally accepted fact that the AFP-Exam-1 exam is a tough nut to crack for the majority of candidates, but there are still a lot of people in this field who long to gain the related certification so that a lot of people want to try their best to meet the challenge of the AFP-Exam-1 Exam. A growing number of people know that if they have the chance to pass the exam, they will change their present situation and get a more decent job in the near future.
| Section | Weight | Objectives |
|---|---|---|
| Client Relationship and Practice Management | 6% | - Practice Management - Communication and Advisory Process - Client Discovery |
| Retirement Planning | 17% | - Registered Retirement Savings Plans - Retirement Income Strategies - Retirement Needs Analysis - Pension Plans |
| Investment Planning | 17% | - Investment Theory - Portfolio Construction - Investment Products - Asset Allocation |
| Estate Planning | 13% | - Trust and Beneficiary Planning - Estate Transfer Strategies - Wills - Powers of Attorney |
| Professional Conduct and Regulatory Compliance | 10% | - Ethics and Professional Standards - Compliance Responsibilities - Regulatory Requirements |
| Asset and Liability Management | 11% | - Debt Management - Personal Balance Sheet Analysis - Budgeting - Cash Flow Management |
| Tax Planning | 14% | - Registered Plans - Income Tax Fundamentals - Tax Deductions and Credits - Tax-Efficient Strategies |
| Risk Management and Insurance | 12% | - Life Insurance - Risk Transfer Strategies - Risk Assessment - Disability and Health Insurance |
>> Exam AFP-Exam-1 Overview <<
The TestSimulate is a leading platform that is committed to ace the AFP-Exam-1 exam preparation and enabling the candidates to pass the final AFP-Exam-1 exam easily. These CSI AFP-Exam-1 exam questions are designed and verified by qualified AFP-Exam-1 subject matter experts. They work closely and check all AFP-Exam-1 Exam Practice test questions step by step and ensure the top standard of AFP-Exam-1 exam questions all the time. So rest assured that with the AFP-Exam-1 exam dumps you will get everything that you need to prepare and pass the Applied Financial Planning Certification Exam 1 (AFP) certification exam with good scores.
NEW QUESTION # 62
A high-income parent gives $80,000 to a 12-year-old child to invest in a non-registered bond fund. The parent expects the child to report the annual interest income. What rule should the planner identify?
Answer: D
Explanation:
Canadian attribution rules are designed to prevent simple income splitting through transfers to related persons, including minor children. When a parent gifts property to a minor child, income such as interest and dividends from the transferred property may attribute back to the parent. The account name alone does not determine the tax result. Option A therefore misses the anti-avoidance rule. Option C is not practical unless the child has earned income and RRSP room, and it does not address attribution. Option D is too narrow; attribution can apply in several family-transfer situations. A planner should consider alternatives such as RESPs, Canada Child Benefit amounts actually belonging to the child, prescribed-rate loan structures with proper interest payment, or investing for capital gains where appropriate and legally supported. The advice must separate legal ownership, tax reporting, and beneficial source of funds. References/topics: income attribution, minor children, family tax planning, non-registered investments.
NEW QUESTION # 63
Keitaro wants his spouse to receive income from his assets for life after his death, but wants the remaining capital to pass to his children from a prior marriage after the spouse dies. Which strategy best fits this objective?
Answer: D
Explanation:
A testamentary spousal trust is a classic blended-family tool. It can provide income or benefit to the surviving spouse during the spouse's lifetime while preserving the remaining capital for children or other remainder beneficiaries. Properly structured, it may also allow a tax-deferred rollover to the trust at death, subject to the spouse-benefit requirements. Option B gives the spouse full control and does not protect the children's remainder interest. Option C can create immediate tax consequences, loss of control, creditor exposure, family law risk, and disputes over beneficial ownership. Option D may increase probate administration and does not, by itself, control the spouse-versus-children distribution problem. The planner should identify the strategy but refer the client to an estate lawyer for drafting. The will must clearly define income rights, capital encroachment rules, trustee powers, tax allocation, and final distribution. References/topics: testamentary spousal trust, blended-family estate planning, tax-deferred rollover, capital beneficiaries. Trustee selection is also central because discretion must be exercised impartially.
NEW QUESTION # 64
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: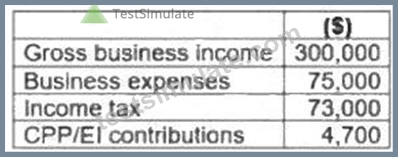
What is Terry's net business income?
Answer: D
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 65
Demario, age 28, has just started his own law firm. He met with his financial planner, Ivy, and she told him that he needs insurance, but Ivy did not specify which type. Demario is single and owns his own home. At this point in his career, his greatest asset is his human capital. Which type of insurance should Ivy have specified to purchase in order for Demario to best protect this asset?
Answer: B
Explanation:
Demario's human capital is his capacity to earn professional income from his law practice. A disability can destroy that earning capacity without causing death and without necessarily triggering critical illness coverage. Disability insurance is therefore the correct product to protect his greatest asset. Term life insurance would be more relevant if he had dependants, estate obligations, or a debt-repayment need at death. Extended health care helps with medical and dental costs but does not replace a lawyer's income if he cannot work.
Critical illness insurance pays on diagnosis of specified illnesses and can supplement planning, but it does not provide the same ongoing income-replacement function as disability coverage. Because Demario is self- employed, policy features such as own-occupation definition, elimination period, benefit period, and business overhead coverage should be reviewed carefully. Study Guide focus: human capital, disability insurance, self- employed professionals, income replacement, and risk management. The recommendation is therefore built around income continuity, not estate creation or reimbursement of medical expenses.
NEW QUESTION # 66
Clara invested $150,000 with Roper Counsel, a member of CIRO. Her portfolio consists entirely of Canadian mutual funds. Roper Counsel recently became insolvent and declared bankruptcy. Where can Clara seek help to recover her financial losses due to this event?
Answer: C
Explanation:
Clara should seek protection through the Canadian Investor Protection Fund because the firm is a CIRO member and the issue is insolvency of an investment dealer or investment firm with client property potentially missing. CIPF protection is not investment-loss insurance; it does not reimburse normal market declines in mutual funds. It addresses eligible client assets when a member firm becomes insolvent and cannot return property. OSFI supervises federally regulated financial institutions but is not the client compensation fund for this fact pattern. Assuris protects policyholders of member life insurance companies. The former MFDA Investor Protection Corporation has been replaced in the current self-regulatory structure; CIRO-related client asset protection points to CIPF. The planner should explain the difference between product risk, issuer risk, and dealer insolvency. Study Guide focus: regulatory bodies, CIRO, CIPF, client asset protection, and investment dealer insolvency. The client should be directed to the fund's eligibility process and advised that ordinary mutual fund market losses remain outside coverage.
NEW QUESTION # 67
......
We would like to benefit our customers from different countries who decide to choose our AFP-Exam-1 study guide in the long run, so we cooperation with the leading experts in the field to renew and update our AFP-Exam-1 learning materials. Our leading experts aim to provide you the newest information in this field in order to help you to keep pace with the times and fill your knowledge gap. As long as you bought our AFP-Exam-1 Practice Engine, you are bound to pass the AFP-Exam-1 exam for sure.
Reliable AFP-Exam-1 Study Notes: https://www.testsimulate.com/AFP-Exam-1-study-materials.html