BONUS!!! Download part of PDFVCE PF1 dumps for free: https://drive.google.com/open?id=1XH_3GP4uOYOCVRBlLj0lDuL4VdpDZqjo
We provide the National Payroll Institute PF1 exam questions in a variety of formats, including a web-based practice test, desktop practice exam software, and downloadable PDF files. PDFVCE provides proprietary preparation guides for the certification exam offered by the PF1 Exam Dumps. In addition to containing numerous questions similar to the PF1 exam, the Payroll Fundamentals 1Exam (PF1) exam questions are a great way to prepare for the National Payroll Institute PF1 exam dumps.
| Section | Objectives |
|---|---|
| Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
| Earnings, Deductions, and Taxation | - Deductions and remittances
|
| Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
Your personal experience convinces all. You can easily download the free demo of PF1 brain dumps on our PDFVCE. Our professional IT team will provide the most reliable PF1 study materials to you. If you have any questions about purchasing PF1 Exam software, you can contact with our online support who will give you 24h online service.
NEW QUESTION # 25
An employee who lives in Ontario and reports to work at a permanent establishment of the employer in Quebec will have income tax deducted based on which province?
Answer: A
Explanation:
For payroll deductions, the key concept is the employee's province of employment (POE)-not where they live. The CRA states that the POE is determined primarily by the employer's establishment where the employee "reports for work." If an employee reports for work at an employer's establishment located in Quebec, then the POE is Quebec, even if the employee's province of residence is Ontario.
This matters because Quebec has distinct payroll requirements. The CRA notes that when the POE is Quebec, employers must apply Quebec-based payroll rules, including deducting Quebec Pension Plan (QPP) contributions instead of CPP, and deducting Quebec parental insurance plan (QPIP) premiums, along with Quebec provincial income tax withholding.
In practice, payroll must set up the employee using Quebec as the POE and ensure stakeholders (HR, finance, the employee) understand why deductions may differ from Ontario residents working in Ontario. Any over
/under-withholding due to POE vs. residence is typically reconciled when the employee files their personal tax return.
NEW QUESTION # 26
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)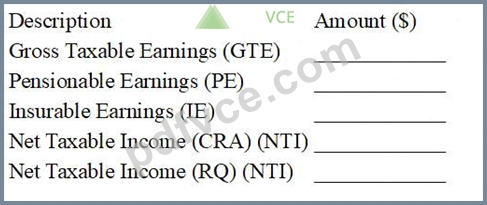
STATUTORY DEDUCTIONS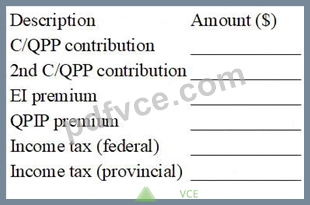
OTHER DEDUCTIONS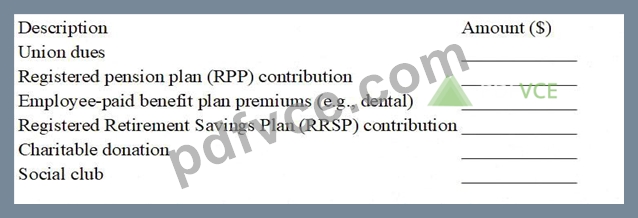
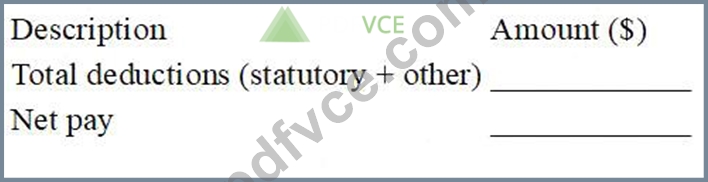
Given Data (Reference)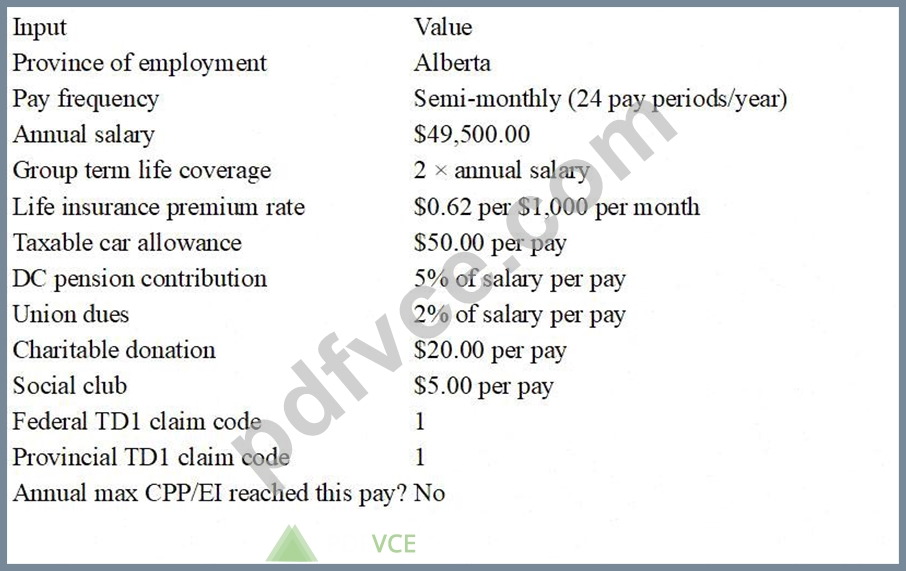
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 27
The authorization for hiring form should contain a checklist to ensure the organization obtains all required information. What is an example of an item that could be on that checklist?
Answer: B
Explanation:
A strong hire-authorization/onboarding checklist ensures payroll and HR collect documents needed to pay the employee accurately and enroll them in required programs. Abenefit enrollment formis a practical, common checklist item because many employers offer benefit plans that require employee elections (for example, health/dental coverage levels, beneficiary information, dependent details, etc.). Indeed's Canadian onboarding guidance explicitly notes employers often collectbenefits enrollmentpaperwork as part of essential new employee forms and onboarding checklists.
By contrast, aT1213(Request to Reduce Tax Deductions at Source) is not routinely required for all hires; it is only used when an employee applies for CRA authorization to reduce tax withheld. A "clearance certificate" is not a standard Canada-wide payroll onboarding requirement for typical employment relationships.
Therefore, "All of the above" is not correct.
Selectingbenefit enrollment formbest matches the purpose of a hiring authorization checklist: ensuring all employment setup steps are completed (pay setup, statutory forms, and benefits enrollment where offered) so payroll deductions and coverage are handled correctly from the start.
NEW QUESTION # 28
An interruption of earnings occurs when there is a period of how many days with no insurable earnings?
Answer: A
Explanation:
Service Canada's ROE Guide defines an interruption of earnings under the "7-day rule." It occurs when an employee has had, or is expected to have, 7 consecutive calendar days with no work and no insurable earnings from the employer.
This is specifically calendar days, not business days. That means weekends and holidays count in the seven- day sequence. The rule commonly applies when employees quit, are laid off, or are terminated, and it helps determine when an employer must issue an ROE (subject to certain listed exceptions and special situations, such as some employees with non-standard work patterns or employees mainly paid by commission).
From a payroll operations standpoint, correctly identifying the interruption of earnings is critical because it triggers ROE deadlines and affects the employee's ability to access EI benefits without delay. So the correct answer is Seven calendar days (option D).
NEW QUESTION # 29
Duncan Drapak was employed in Ontario. Upon termination of his employment, he will be paid $7,760.00 legislated wages in lieu of notice together with his final weekly pay of $875.00. Calculate Duncan's Canada Pension Plan (CPP) contribution if the yearly maximum contribution will not be exceeded.
Answer:
Explanation:
$509.78
Explanation:
Legislated wages in lieu of notice are treated as pensionable employment earnings for CPP purposes, so they are included with the employee's final regular pay when calculating CPP deductions (assuming no CPP exemption applies).
Step 1: Determine total pensionable earnings for the week:
$7,760.00 + $875.00 = $8,635.00.
Step 2: Subtract the CPP basic exemption (Year's Basic Exemption is $3,500 annually). For a weekly payroll, the basic exemption is prorated:
$3,500 ÷ 52 = $67.31.
CPP contributory earnings for the week:
$8,635.00 # $67.31 = $8,567.69.
Step 3: Apply the 2026 CPP employee contribution rate of 5.95% (base CPP). The question states the annual maximum will not be exceeded, so no capping is required in this calculation.
CPP contribution:
$8,567.69 × 5.95% = $509.7777..., rounded to $509.78.
NEW QUESTION # 30
......
Do you have registered for National Payroll Institute PF1 exam? With the drawing near of the examination, I still lack of confidence to pass PF1 test. Then I have not enough time to read reference books. About the above problem, how should I do? Is there shortcut to pass the exam? Do you have such a mood like that, now? There is no need for hurry. Even if the examination time is near, you are also given the opportunity to prepare for PF1 Certification test. And what is the opportunity? It is PDFVCE PF1 dumps which is the most effective materials and can help you prepare for the exam in a short period of time. What's more, PDFVCE practice test materials have a high hit rate. 100% satisfaction guarantee! As well as you memorize these questions and answers in our dumps, you must pass National Payroll Institute PF1 certification.
New PF1 Dumps Ebook: https://www.pdfvce.com/National-Payroll-Institute/PF1-exam-pdf-dumps.html
DOWNLOAD the newest PDFVCE PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1XH_3GP4uOYOCVRBlLj0lDuL4VdpDZqjo