P.S. Free & New ClaimCenter-Business-Analysts dumps are available on Google Drive shared by PracticeTorrent: https://drive.google.com/open?id=1gvGrOnE79eLaI4OowK9uuOrdcrXD8Qqd
we believe that all students who have purchased ClaimCenter-Business-Analysts practice materials will be able to successfully pass the professional ClaimCenter-Business-Analysts qualification exam as long as they follow the content provided by our ClaimCenter-Business-Analysts study materials, study it on a daily basis, and conduct regular self-examination through mock exams. Of course, before you buy, our ClaimCenter-Business-Analysts Study Materials offer you a free trial service, as long as you log on our website, you can download our trial questions bank for free. I believe that after you try ClaimCenter-Business-Analysts test engine, you will love them.
| Certification Vendor: | Guidewire |
|---|---|
| Exam Name: | ClaimCenter Business Analyst - Mammoth Proctored Exam |
| Exam Number: | ClaimCenter-Business-Analysts |
| Related Certifications: | Guidewire InsuranceSuite Analyst Certification |
| Available Languages: | English |
| Exam Format: | Multiple Choice, Multiple Select, Scenario-based Questions |
| Real Exam Qty: | 50-70 (varies by version) |
| Exam Registration: | Guidewire Education Portal |
| Sample Questions: | Guidewire ClaimCenter-Business-Analysts Sample Questions |
| Exam Way: | Online proctored (Mammoth Proctored Exam) |
| Pre Condition: | Recommended: Guidewire InsuranceSuite Analyst foundational training (no strict formal prerequisite publicly specified) |
>> Valid Guidewire ClaimCenter-Business-Analysts Exam Dumps <<
The customers can immediately start using the ClaimCenter Business Analyst - Mammoth Proctored Exam (ClaimCenter-Business-Analysts) exam dumps of PracticeTorrent after buying it. In this way, one can save time and instantly embark on the journey of ClaimCenter-Business-Analysts test preparation. 24/7 customer service is also available at PracticeTorrent. Feel free to reach our customer support team if you have any questions about our ClaimCenter-Business-Analysts Exam Preparation material.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
NEW QUESTION # 20
An Adjuster at Succeed Insurance is handling a personal auto claim for an insured who hit a tree after swerving to avoid a child who ran into the road.
The Adjuster has this Authority Limit Profile: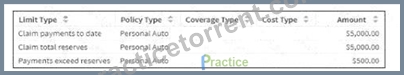
The Adjuster creates a collision exposure and sets the initial reserves so that payments can be made to the insured for repairs to the damaged vehicle. No payments have been created yet.
The current financials for the claim are as follows:
Which two financial transactions will not require approval given that each option is the only transaction change rather than a cumulative change? (Choose two.)
Answer: C,D
Explanation:
To determine if a transaction requires approval, we must compare the proposed transaction against the Adjuster's Authority Limits and the current financial state of the claim.
* Current State:Total Reserves = $3,000 ($2,500 Indemnity + $500 Expense). Total Paid = $0.
* Adjuster Limits:
* Claim Total Reserves Limit: $5,000
* Payments Exceed Reserves Limit: $500
Evaluation of Options:
* Option B (No Approval Required):Making a $2,000 payment against the "Claim Cost - Auto body" reserve.
* The available reserve is $2,500. Since $2,000 < $2,500, the payment does not exceed the reserve.
* The total payments on the claim would be $2,000, which is well below the "Claim payments to date" limit of $5,000.
* Option D (No Approval Required):Increasing the Expense reserve to $550.
* This increases the total claim reserves from $3,000 to $3,050 ($2,500 + $550).
* Since $3,050 is below the Adjuster's "Claim total reserves" limit of $5,000, no approval is triggered.
Why other options require approval:
* Option A:A payment of $1,100 against a $500 reserve means the payment exceeds the reserve by$600.
The Adjuster's limit for "Payments exceed reserves" is only$500. Since $600 > $500, approval is required.
* Option C:Increasing the Auto body reserve to $6,000 would raise the total claim reserves to$6,500 ($6,000 + $500). This exceeds the Adjuster's "Claim total reserves" limit of $5,000, triggering an approval.
NEW QUESTION # 21
Succeed Insurance has a strategic initiative to offer pay-as-you-drive personal auto insurance to compete with other large carriers. Customers who choose these policies must either own a vehicle that is equipped with a monitoring device or agree to install a device provided by Succeed. The monitoring device collects information about how the drivers of a covered vehicle drive, including how fast they drive, how hard they brake, and how many miles/kilometers the vehicle travels within a policy period.
This information is logged, and premiums are based on how the insured's driving behavior is categorized.
When a claim is reported, the log files must be obtained to analyze the information captured by the monitoring device at the time of the incident.
Succeed plans to collect and evaluate the Vehicle Monitoring Log files in the first implementation phase, which is scheduled for release in 60 days. The project sponsors have instructed the implementation team to use base product functionality over customization. Integration should be leveraged where possible to avoid manual data entry.
No payments can be made on the claim until a flag indicating that the Vehicle Monitoring Log file has been processed has been set to 'Yes'.
Which feature of the base product prevents payments from being made on the claim?
Answer: D
Explanation:
In Guidewire ClaimCenter, the Ability to Pay validation level is the specific "gatekeeper" designed to verify that a claim is mature enough and has sufficient data to allow financial transactions to be issued.
* Validation Levels:ClaimCenter uses validation levels (e.g., Load, New Loss, Ability to Pay) to enforce data integrity at different stages of the claim lifecycle.
* Blocking Payments:When a user attempts to create a check, the system triggers the rules associated with theAbility to Paylevel. If any rule at this level fails (returns an error), the system prevents the payment wizard from completing.
* Scenario Application:The Business Analyst can define a rule at the "Ability to Pay" level that checks the condition:"If Policy Type is Pay-as-you-drive AND Log Processed Flag is NOT 'Yes', then throw an error."This fulfills the requirement to strictly block payments ("No payments can be made") rather than just route them for approval.
Why other options are incorrect:
* Authority Limits (B)control theamountof money a user can approve, not the prerequisites (like data flags) for making a payment.
* Transaction Validation requiring approval (C)would route the payment to a supervisor, but it implies the paymentcouldbe made if approved. The requirement states "No payments can be made," implying a hard system stop, which validation rules provide.
* Send to External System (D)validates data just before it leaves the system (e.g., for check printing), which is often too late in the workflow for business-logic stops like reviewing a log file.
NEW QUESTION # 22
Succeed Insurance needs the ability to associate a primary hospital with an injury incident if the injured party received treatment. When treatment is needed, the primary hospital name should display on the injury incident screen along with other details about the injury and treatment received.
The primary hospital should be added to the injury incident in one of the following ways:
. Select the name from a list of medical care organizations already associated with the claim.
. Enter the contact details directly in the incident.
. Search the Address Book from the incident to locate a hospital.
Which two requirements must be documented to associate the primary hospital with the claim? (Choose two.)
Answer: B,D
Explanation:
To implement the functionality of associating a specific contact (the "Primary Hospital") with an entity (the
"Injury Incident") in Guidewire ClaimCenter, two core configuration components are required:
* A new primary hospital role (Option B):In ClaimCenter, the relationship between a Contact and a Claim (or Incident) is defined by aRole. While the contact itself might be a "Medical Care Organization" (existing subtype), thecontextof its relationship to this specific incident is that it is the
"Primary Hospital". Defining this role allows the system to distinguish this hospital from other medical providers on the same claim.
* A new field on the incident screen (Option C):To allow the user to select, add, or view this contact, a UI element (specifically aClaim Contact Pickeror Input widget) must be added to the Injury Incident screen. This field will be configured to store the relationship and allows the user to perform the required actions: selecting from existing contacts (filtered by the role), entering new ones, or searching the Address Book.
Why other options are incorrect:
* A (New Subtype):The base product already includes the MedicalCareOrg contact subtype, which is sufficient to store hospital data. Creating a new subtype is unnecessary unless the data structure (fields) of a hospital is fundamentally different from other medical providers.
* D (Address Book Field):Contacts in the Address Book are typically identified by tags or their Subtype, not by adding a custom field just to identify them as a vendor/hospital.
NEW QUESTION # 23
Drivers for Rideshare companies need insurance that provides protection when they are driving the vehicle for personal reasons. This will be the Succeed Insurance standard Personal Auto Policy. However, they also need insurance to protect them from the increased risks associated with working as a Rideshare Driver. This would include when they are logged in to the Rideshare application waiting for a customer match, on their way to pick up a customer, but not when a customer has entered the vehicle.
When a driver is working as a Rideshare Driver, this new Rideshare coverage will protect them from the following types of risks, and there is a need to be able to collect the appropriate information about the losses:
. Injury to a first-party driver
. Damaged personal property of the third-party passengers
Which two exposures need to be configured? (Choose two.)
Answer: B,D
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
To satisfy the requirements for the new "Rideshare" coverage product, the Business Analyst must map the described risks to the correct Exposure Types in the ClaimCenter data model.
* Risk: Injury to a first-party driver:In insurance terminology, "First Party" refers to the insured (the driver). Coverage for injuries sustained by the driver themselves is typically handled byMedical Payments(MedPay) or Personal Injury Protection (PIP). Among the choices provided,Rideshare Medical Payments (Option C)is the correct exposure type to cover medical costs for the driver regardless of fault. (Option E, Liability Bodily Injury, would cover injuries toothersthat the driver hit).
* Risk: Damaged personal property of third-party passengers:This refers to liability for damage to property belonging to others. While typically "Property Damage Liability," the specific option provided that fits this description isRideshare Personal Property Protection (Option B). This exposure would be configured to capture details about the damaged items (e.g., luggage, electronics) belonging to the passengers.
Why other options are incorrect:
* Option E (Liability Bodily Injury):This is for Third Party injuries (e.g., pedestrians or people in other cars), not the First Party driver.
* Option D (Under Insured Motorist):This applies when the Rideshare driver is hit by someone else who doesn't have enough insurance. The prompt focuses on the risksofthe driver working, not the financial failure of others.
NEW QUESTION # 24
What is a reason to assign a unique identification number to each User Story Card in ClaimCenter implementation projects?
Answer: A
Explanation:
In Guidewire implementation methodology (such as SurePath), traceability and organization are maintained through strict naming conventions.
* Naming Convention (Option C):A unique identification number is assigned to every User Story Card to create a consistent naming structure:Product - Theme - Subtheme - ID. (For example: CC - FNOL - Vehicle - 001).
* Purpose:This convention allows Business Analysts, Developers, and QA testers to easily reference, search, and trace requirements across different tools (e.g., from the Story Card in Excel/Jira to the code in Studio and the test cases in the testing suite).
* Why not A, B, or D?Time estimation (A) uses "Story Points," not the ID. Burndown charts (B) track velocity/points, not criteria IDs. Backlogs (D) are organized byBusiness Value/Priority, not just numerically by ID.
NEW QUESTION # 25
......
ClaimCenter-Business-Analysts Test Price: https://www.practicetorrent.com/ClaimCenter-Business-Analysts-practice-exam-torrent.html
P.S. Free & New ClaimCenter-Business-Analysts dumps are available on Google Drive shared by PracticeTorrent: https://drive.google.com/open?id=1gvGrOnE79eLaI4OowK9uuOrdcrXD8Qqd