DOWNLOAD the newest TestValid PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=16eFPH-dHjdRUnUS5MUMCdo4w90kgEn4a
Life is full of ups and downs. We cannot predicate what will happen in the future. To avoid being washed out by the artificial intelligence, we must keep absorbing various new knowledge. Our PF1 learning questions will inspire your motivation to improve yourself. Tens of thousands of our loyal customers are benefited from our PF1 Study Materials and lead a better life now after they achieve their PF1 certification.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Topic 2: Communication and Compliance | 10% | - Stakeholder communication
|
| Topic 3: Individual Pay Calculations | 40% | - Non-regular earnings
|
| Topic 4: Termination and Special Payments | 30% | - Leaves and absences
|
>> PF1 Exam Guide Materials <<
With the intense competition in labor market, it has become a trend that a lot of people, including many students, workers and so on, are trying their best to get a PF1 certification in a short time. The PF1 exam prep is produced by our expert, is very useful to help customers pass their exams and get the certificates in a short time. We are going to show our PF1 Guide braindumps to you. We can sure that our product will help you get the certificate easily. If you are wailing to believe us and try to learn our PF1 exam torrent, you will get an unexpected result.
NEW QUESTION # 60
The source deductions form completed by all new employees in Quebec is called:
Answer: D
Explanation:
In Quebec, employees must complete a Quebec-specific source deductions form so the employer can calculate Quebec income tax to withhold. Revenu Quebec identifies Form TP-1015.3-V (Source Deductions Return) as the form employees complete and provide to their employer/payer for this purpose. It is part of the onboarding
/payroll setup process in Quebec and is used to determine personal tax credits and any additional withholding instructions for Quebec provincial income tax.
The other options are not the standard Quebec source deductions return for new employees: T1213 is a CRA form used to request a reduction in tax deductions at source (federal), TD1-AB is a provincial TD1 for Alberta (not Quebec), and T2222 is not the Quebec source deductions return. From a payroll communication standpoint, the employer should request both the applicable federal TD1 and the Quebec TP-1015.3-V, then retain them on file to support accurate withholding calculations.
NEW QUESTION # 61
An employee who lives in Ontario and reports to work at a permanent establishment of the employer in Quebec will have income tax deducted based on which province?
Answer: B
Explanation:
For payroll deductions, the key concept is the employee's province of employment (POE)-not where they live. The CRA states that the POE is determined primarily by the employer's establishment where the employee "reports for work." If an employee reports for work at an employer's establishment located in Quebec, then the POE is Quebec, even if the employee's province of residence is Ontario.
This matters because Quebec has distinct payroll requirements. The CRA notes that when the POE is Quebec, employers must apply Quebec-based payroll rules, including deducting Quebec Pension Plan (QPP) contributions instead of CPP, and deducting Quebec parental insurance plan (QPIP) premiums, along with Quebec provincial income tax withholding.
In practice, payroll must set up the employee using Quebec as the POE and ensure stakeholders (HR, finance, the employee) understand why deductions may differ from Ontario residents working in Ontario. Any over
/under-withholding due to POE vs. residence is typically reconciled when the employee files their personal tax return.
NEW QUESTION # 62
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
STATUTORY DEDUCTIONS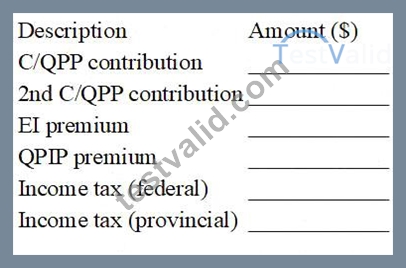
OTHER DEDUCTIONS

Given Data (Reference)
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 63
The employee-employer relationship is deemed to be severed when:
Answer: D
Explanation:
In ROE administration, the key concept is whether the employment relationship is still "active" (that is, whether there is an ongoing expectation the employee will work again). Service Canada's ROE guidance ties ROE issuance to an interruption of earnings and specifically identifies situations where an employee is no longer on the employer's active employment list (for example, no expectation of future work) as a trigger for issuing an ROE.
Options A and B describe circumstances that can still align with an ongoing employment relationship. For example, employees may remain eligible for certain benefits after a last day worked, and a right to recall means the employer may still consider the employee attached to the workplace (often still "active" depending on the arrangement). In contrast, when there is no expectation of work to be performed, the relationship is effectively ended for ROE purposes, and the employer generally proceeds with separation reporting and ROE completion based on the interruption of earnings rules.
NEW QUESTION # 64
Steve is physically disabled and his employer pays for his parking spot. This is considered:
Answer: A
Explanation:
Employer-provided parking is often a taxable benefit, generally valued at the fair market value of the parking spot. However, the CRA provides a specific exception for employees with disabilities. CRA guidance on employer-provided parking states that if your employee has a disability, the parking benefit is generally not taxable, including situations involving a severe and prolonged mobility impairment or blindness.
In Steve's case, the fact pattern explicitly says he is physically disabled and the employer pays for his parking.
Under CRA's general rule for disability-related parking, this would generally not be included in income as a taxable benefit, meaning it is not a taxable allowance and not a taxable benefit (cash or non-cash) for payroll purposes.
Payroll should still document why the parking is being treated as non-taxable (for example, disability-related need) and ensure the treatment aligns with CRA guidance if questioned. If the facts were different (non- disability parking or preferential parking provided to employees generally), the taxable benefit rules would usually apply.
NEW QUESTION # 65
......
You may be also one of them, you may still struggling to find a high quality and high pass rate Payroll Fundamentals 1Exam study question to prepare for your exam. Your search will end here, because our study materials must meet your requirements. The PF1 torrent prep contains the real questions and simulation questions of various qualifying examinations. It is very worthy of study efficiently. Time is constant development, and proposition experts will set questions of Real PF1 Exam continuously according to the progress of the society change tendency of proposition, and consciously highlight the hot issues and policy changes.
PF1 New Practice Questions: https://www.testvalid.com/PF1-exam-collection.html
What's more, part of that TestValid PF1 dumps now are free: https://drive.google.com/open?id=16eFPH-dHjdRUnUS5MUMCdo4w90kgEn4a