DOWNLOAD the newest VCETorrent IIA-CIA-Part3 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1Iv0kGQA7yAxJsSocfRgCul0GHQ3F8kCr
Our IIA-CIA-Part3 exam questions are authoritatively certified. Our goal is to help you successfully pass relevant exam in an efficient learning style. Due to the quality and reasonable prices of our IIA-CIA-Part3 training materials, our competitiveness has always been a leader in the world. Our IIA-CIA-Part3 Learning Materials have a higher pass rate than other IIA-CIA-Part3 training materials, so we are confident to allow you to gain full results.
| Certification Vendor: | IIA (The Institute of Internal Auditors) |
|---|---|
| Exam Name: | Internal Audit Function |
| Exam Number: | IIA-CIA-Part3 |
| Exam Duration: | 120 minutes |
| Exam Format: | Multiple Choice Questions |
| Related Certifications: | Certified Internal Auditor (CIA) |
| Real Exam Qty: | 100 |
| Available Languages: | Simplified Chinese, Portuguese, Polish, English, Thai, Japanese, German, Spanish, Traditional Chinese, French, Arabic, Indonesian, Korean, Turkish, Russian |
| Exam Price: | USD 280 (IIA Member) / USD 415 (Non-member) / USD 215 (Student) |
| Certificate Validity Period: | CIA certification requires ongoing CPE; exam scores valid for program window (typically 3 years) |
| Passing Score: | 600 (scaled score out of 750) |
| Sample Questions: | IIA IIA-CIA-Part3 Sample Questions |
| Exam Way: | Computer-based testing at Pearson VUE test centers worldwide. As of May 28, 2025, online proctored testing has been discontinued; all exams must be taken in-person at authorized Pearson VUE testing centers. |
| Pre Condition: | Candidates must have an active CIA program enrollment through The IIA's Certification Candidate Management System (CCMS). A bachelor's degree or equivalent is required for CIA certification. Part 3 can be taken in any order, but all three parts must be passed within the program eligibility window (typically 3 years from acceptance). |
| Official Syllabus URL: | https://www.theiia.org/globalassets/certifications/cia-exam-syllabus/cia-part-3-syllabus.pdf |
>> Customizable IIA-CIA-Part3 Exam Mode <<
Our IIA-CIA-Part3 real study guide materials can help you get better and better reviews. This is a very intuitive standard, but sometimes it is not enough comprehensive, therefore, we need to know the importance of getting the test IIA-CIA-Part3 certification, qualification certificate for our future job and development is an important role. Only when we have enough qualifications to prove our ability can we defeat our opponents in the harsh reality. We believe our IIA-CIA-Part3 actual question will help you pass the IIA-CIA-Part3 qualification examination and get your qualification faster and more efficiently.
IIA-CIA-Part3 exam is a computer-based test that consists of 100 multiple-choice questions. Candidates are given two and a half hours to complete the exam. To be eligible to take IIA-CIA-Part3 Exam, candidates must have completed the IIA-CIA-Part1 and IIA-CIA-Part2 exams. Passing IIA-CIA-Part3 exam is a critical step towards obtaining the CIA certification, which is recognized globally as the standard for excellence in internal auditing.
Passing the IIA-CIA-Part3 exam is a significant achievement for internal auditors. It demonstrates that they have a solid understanding of business concepts and how they relate to internal auditing. This knowledge is essential for internal auditors, as it enables them to identify risks and opportunities within an organization and make informed recommendations to management. Internal Audit Function certification also demonstrates a commitment to professional development and a willingness to invest in one's career.
NEW QUESTION # 725
Which of the following concepts of managerial accounting is focused on allocating overheads to products?
Answer: D
NEW QUESTION # 726
A manufacturer uses a materials requirements planning 1RP) system to track inventory, orders, and raw material requirements. A preliminary audit assessment indicates that the organization's inventory is understated. Using audit software, what conditions should the auditor search for in the MRP database to support this hypothesis?
I. Item cost set at zero.
II. Negative quantities on hand.
III. Order quantity exceeding requirements.
IV.
Inventory lead times exceeding delivery schedule.
Answer: C
Explanation:
If there is no monetary amount in the database for existing inventory, inventory will be understated. Moreover, inadequate edit checks or uncontrolled borrow/paybacks could cause negative quantities to be reported. This condition would cause inventory to be understated. If the amount ordered exceeds requirements, the result is an increase in inventory. However, by itself, this condition would not cause inventory to be understated or overstated. Also, if lead times are longer than delivery times, the effect is an increase in inventory but not necessarily a misstatement.
NEW QUESTION # 727
Which of the following would most likely be found in an organization that uses a decentralized organizational structured?
Answer: D
NEW QUESTION # 728
An entity uses the retail method of inventory estimation for interim reporting purposes.
Management expects some normal shrinkage in the inventory because of theft. What effect will the failure to consider this shrinkage have on the computation of1) the cost retail ratio, and2) the estimated ending inventory at retail?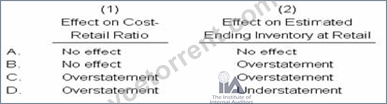
Answer: D
Explanation:
The retail method of inventory estimation applies a cost-retail ratio to the ending inventory at retail to determine ending inventory at cost For example, a popular method calculates the ratio as goods available for sale at cost divided by goods available at retail, with markups but not markdowns included in the calculation of the retail amount. Normal inventory is subtracted from the retail amount of goods available because are not available. However, abnormal amounts of theft, etc., are removed from the cost and retail amounts. The reason for the difference in treatment is that normal but not abnormal inventory losses are anticipated and included in the selling retail value). Accordingly, failure to account for normal inventory shrinkage has no effect on the calculate cost-retail ratio but overstates ending inventory at retail.
NEW QUESTION # 729
Which of the following is a systems software control?
Answer: C
NEW QUESTION # 730
......
Exam IIA-CIA-Part3 Questions Answers: https://www.vcetorrent.com/IIA-CIA-Part3-valid-vce-torrent.html
P.S. Free & New IIA-CIA-Part3 dumps are available on Google Drive shared by VCETorrent: https://drive.google.com/open?id=1Iv0kGQA7yAxJsSocfRgCul0GHQ3F8kCr