What's more, part of that ITdumpsfree IFC dumps now are free: https://drive.google.com/open?id=1dNfcQK2Y0y5SY2NcrJYVHXwd-9iXeDiA
When preparing for the test IFC certification, most clients choose our products because our IFC learning file enjoys high reputation and boost high passing rate. Our products are the masterpiece of our company and designed especially for the certification. Our IFC latest study question has gone through strict analysis and verification by the industry experts and senior published authors. The clients trust our products and treat our products as the first choice. So the total amounts of the clients and the sales volume of our IFC learning file is constantly increasing.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
ITdumpsfree provides 24/7 customer support to answer any of your queries or concerns regarding the Investment Funds in Canada (IFC) Exam (IFC) certification exam. They have a team of highly skilled and experienced professionals who have a thorough knowledge of the Investment Funds in Canada (IFC) Exam (IFC) exam questions and format. With the aim of helping aspirants to achieve the Investment Funds in Canada (IFC) Exam (IFC) certification, ITdumpsfree is committed to providing the best quality and updated CISI IFC exam dumps.
NEW QUESTION # 491
You have been researching Canadian equity mutual funds for a new client. You come across the following information.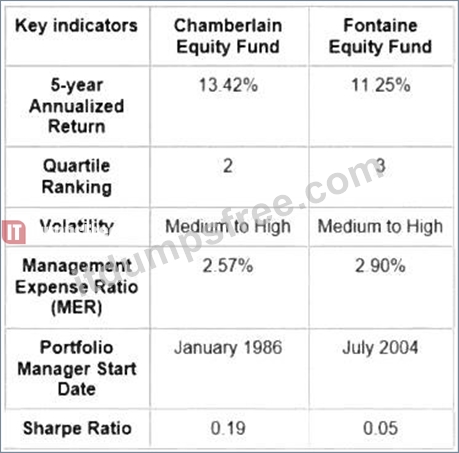
What can you conclude from this information?
Answer: A
Explanation:
The management expense ratio (MER) is the percentage of a fund's assets that is paid to the fund manager for operating and managing the fund. A higher MER means that more of the fund's returns are eaten up by fees, leaving less for the investors. Therefore, Fontaine Equity Fund's higher MER of 2.99% contributes to its lower 5-year annualized return of 11.25%, compared to Chamberlain Equity Fund's MER of 2.57% and 5- year annualized return of 13.42%. Therefore, D is the correct answer. , Management Expense Ratio (MER):
Definition and How It Works - Investopedia
NEW QUESTION # 492
Marta is turning 71 years old this year. She will have to convert her registered retirement savings plan (RRSP) to a registered retirement income fund (RRIF). Which of the following statements is TRUE?
Answer: D
Explanation:
The statement that is true about Marta's situation is option D. A registered retirement income fund (RRIF) is a type of registered account that provides income in retirement by converting savings from an RRSP or other sources. A RRIF holder must withdraw a minimum amount from their RRIF each year, starting from the year after they open their RRIF. The minimum amount is calculated based on a percentage factor set by the Canada Revenue Agency (CRA) and the value of the RRIF at the beginning of each year. However, due to the COVID-19 pandemic, the CRA has reduced the required minimum withdrawals from RRIFs by 25% for 2020 and 2021. Therefore, Marta does not have to withdraw the minimum amount this year if she chooses to take advantage of this temporary measure. Therefore, option D is true about Marta's situation. The other statements are not true about Marta's situation. Option A is false because she will not be able to continue contributing to her RRIF and be subject to the same annual limits as her RRSP; rather, she will not be able to make any further contributions to her RRIF once she converts her RRSP to a RRIF. Option B is false because she will not incur a tax liability when she converts her RRSP to a RRIF; rather, she will only pay tax on the amount that she withdraws from her RRIF each year. Option C is false because she will not be subject to annual maximum withdrawal limits; rather, she will be able to withdraw any amount from her RRIF as long as she meets the minimum withdrawal requirement. References: [Registered Retirement Income Fund (RRIF)
| GetSmarterAboutMoney.ca], [Making RRIF withdrawals | GetSmarterAboutMoney.ca], [RRIF minimum withdrawal factors], [RRIFs: Temporary 25% reduction in minimum withdrawals for 2020 and 2021]
NEW QUESTION # 493
Justin and Yvonne both open a Registered Education Savings Plan (RESP) for their daughter Grace. They plan to regularly contribute $1,000 per year until Grace reaches the age of 17.
Which of the following statements relating to RESP is CORRECT?
Answer: A
Explanation:
A Registered Education Savings Plan (RESP) is a tax-advantaged savings plan that helps parents and family members save for a child's post-secondary education. The government also contributes to the plan through the Canada Education Savings Grant (CESG) and the Canada Learning Bond (CLB), depending on the family income and the amount of contributions. However, there are some rules and limits that apply to RESP contributions and government grants. One of them is the lifetime contribution limit, which is the maximum amount that can be contributed to an RESP for a beneficiary from all sources. The lifetime contribution limit is $50,000 per beneficiary, regardless of how many RESPs are opened for them or who contributes to them.
Therefore, statement A is correct. Justin and Yvonne may contribute a combined lifetime maximum of
$50,000 for Grace to their RESP.
The other statements are incorrect for the following reasons:
* Statement B: RESPs are not tax-free investment plans. They are tax-deferred plans, meaning that the contributions are made with after-tax dollars and the investment income earned in the plan is not taxed until it is withdrawn as an educational assistance payment (EAP) for the beneficiary. The EAPs are taxed in the hands of the beneficiary, who usually has little or no income and pays little or no tax.
* Statement C: There is no annual contribution limit for RESP contributions. However, there is an annual limit for the CESG, which is 20% of the first $2,500 contributed per beneficiary per year, up to a maximum of $500 per year. The CESG also has a lifetime limit of $7,200 per beneficiary.
* Statement D: Contributions made to an RESP are not eligible for a tax deduction in the year they are contributed. They are made with after-tax dollars and do not reduce the contributor's taxable income.
1: Canadian Investment Funds Course, Unit 9, Section 9.1
NEW QUESTION # 494
What type of risk remains unaffected by diversification?
Answer: B
NEW QUESTION # 495
Frederic recently sold his units in a US dollar (USD) denominated mutual fund. He wants to convert the proceeds back to Canadian dollars (CAD). If he received proceeds of $1,200 USD from the sale and the exchange rate is $1 CAD for $0.99 USD, how much will Frederic receive in Canadian dollars?
Answer: D
Explanation:
To convert the proceeds from USD to CAD, Frederic needs to divide the amount in USD by the exchange rate. The exchange rate is $1 CAD for $0.99 USD, which means that $0.99 USD is equivalent to $1 CAD.
Therefore, Frederic will receive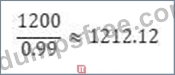
A math problem with numbers AI-generated content may be incorrect.
CAD in Canadian dollars.
NEW QUESTION # 496
......
In this website, you can find three different versions of our IFC guide torrent which are prepared in order to cater to the different tastes of different people from different countries in the world since we are selling our IFC test torrent in the international market. Most notably, the simulation test is available in our software version. With the simulation test, all of our customers will have an access to get accustomed to the IFC Exam atmosphere and pass easily in the real IFC exam.
IFC Accurate Test: https://www.itdumpsfree.com/IFC-exam-passed.html
P.S. Free & New IFC dumps are available on Google Drive shared by ITdumpsfree: https://drive.google.com/open?id=1dNfcQK2Y0y5SY2NcrJYVHXwd-9iXeDiA