P.S. Free & New ClaimCenter-Business-Analysts dumps are available on Google Drive shared by Pass4cram: https://drive.google.com/open?id=1tWcO17Im6IlZY2c2ejRqdG5UwbU3nLKi
We have tens of thousands of supporters around the world eager to pass the exam with our ClaimCenter-Business-Analysts learning guide which are having a steady increase on the previous years. Exam candidates around the world are longing for learning from our practice materials. If you want to have an outline and brief understanding of our ClaimCenter-Business-Analysts Preparation materials we offer free demos for your reference. You can have a look of our ClaimCenter-Business-Analysts exam questions for realistic testing problems in them.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
>> ClaimCenter-Business-Analysts Sample Questions Answers <<
We offer you free update for one year if you buy ClaimCenter-Business-Analysts training materials from us. That is to say, in the following year, you will get the latest version once the ClaimCenter-Business-Analysts exam dumps update. It can save your money for buying new version. In addition, the ClaimCenter-Business-Analysts learning materials of us is compiled by experienced experts, and the quality can be guaranteed, you can pass your exam just one time by using ourClaimCenter-Business-Analysts Exam Dumps. We also have online and offline service stuff, if you have any question, you can consult us.
NEW QUESTION # 32
Succeed Insurance has a requirement to add a new high-risk indicator to the Claim Status screen for property claims that have a lien on the property. A new icon will be added to the configuration to provide a visual indicator making it easier for Adjusters and other ClaimCenter users to determine that a claim has a lien.
Which two common areas of the user interface (UI) can display the new lien icon? (Choose two.)
Answer: B,D
Explanation:
In the standard Guidewire ClaimCenter User Interface architecture, high-priority alerts and claim indicators are displayed in two primary locations to ensure visibility:
* The Info Bar (Option D):This is the persistent strip located at the top of the claim file (just below the Tab Bar). It remains visible regardless of which specific claim sub-screen (Medical, Financials, Notes) the user is navigating. It is designed specifically to host "High Risk Indicators" such as Litigation, Fatalities, Coverage issues, and in this scenario, a "Lien" indicator. This ensures the adjuster is aware of the critical status immediately upon opening the claim.
* The Screen Area (Option A):Specifically, theClaim Status(or Summary) screen-which resides in the main Screen Area-contains a dedicated section for "Claim Indicators." Here, the icon is displayed along with a text description and potential toggle status (On/Off). The prompt explicitly mentions the requirement to "add a new high-risk indicator to the Claim Status screen," confirming the Screen Area as the second location.
Why other options are incorrect:
* Sidebar (B):The sidebar (left panel) is used for the "Actions" menu and navigation links (steps) to move between screens. It does not typically host status icons for the claim object itself.
* Workspace (C):While "Workspace" can refer to the application frame, in UI terminology, it often refers to the specific worksheets (bottom pane) or the container, not the specific UI element for indicators.
* Tab Bar (E):The Tab Bar is for high-level navigation (Claim, Desktop, Administration, Search) and does not display claim-specific data icons.
NEW QUESTION # 33
What two pieces of information enable the Business Analyst (BA) to trace back to the root cause of an issue?
(Choose two.)
Answer: C,E
Explanation:
In Guidewire implementation methodology (Agile/SurePath), Traceability is maintained through specific unique identifiers that link the code and test cases back to the business definition.
* Unique Requirement Numbers (Option E):Every granular business requirement is assigned a unique ID (e.g., CC-FNOL-001). If a defect or issue arises during testing or production, the BA uses this number to find the exact text of the requirement that was implemented. This helps determine if the issue is a "bug" (code doesn't match requirement) or a "gap" (requirement was missing or wrong).
* Unique Story Card Number (Option A):User Stories act as containers for requirements. The Story Card Number (e.g., Story-105) links the individual requirements to the broader feature context. Tracing back to the Story Card allows the BA to review the original scope, the UI mockups, and the Acceptance Criteria associated with that feature to understand the "Root Cause" of the misunderstanding or failure.
Why other options are incorrect:
* Option B (Caution points):These are process diagrams notes, useful for training but not for system traceability.
* Option C (Change History):While useful for seeingwhoedited a document, it does not provide the structural link between a system error and the business definition like the IDs do.
* Option D (Approver Notes):These confirm sign-off but rarely contain the functional detail needed to diagnose a root cause.
NEW QUESTION # 34
Drivers for Rideshare companies need insurance that provides protection when they are driving the vehicle for personal reasons. This will be the Succeed Insurance standard Personal Auto Policy. However, they also need insurance to protect them from the increased risks associated with working as a Rideshare Driver. This would include when they are logged in to the Rideshare application waiting for a customer match, on their way to pick up a customer, but not when a customer has entered the vehicle.
When a driver is working as a Rideshare Driver, this new Rideshare coverage will protect them from the following types of risks, and there is a need to be able to collect the appropriate information about the losses:
. Injury to a first-party driver
. Damaged personal property of the third-party passengers
Which two exposures need to be configured? (Choose two.)
Answer: C,E
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
To satisfy the requirements for the new "Rideshare" coverage product, the Business Analyst must map the described risks to the correct Exposure Types in the ClaimCenter data model.
* Risk: Injury to a first-party driver:In insurance terminology, "First Party" refers to the insured (the driver). Coverage for injuries sustained by the driver themselves is typically handled byMedical Payments(MedPay) or Personal Injury Protection (PIP). Among the choices provided,Rideshare Medical Payments (Option C)is the correct exposure type to cover medical costs for the driver regardless of fault. (Option E, Liability Bodily Injury, would cover injuries toothersthat the driver hit).
* Risk: Damaged personal property of third-party passengers:This refers to liability for damage to property belonging to others. While typically "Property Damage Liability," the specific option provided that fits this description isRideshare Personal Property Protection (Option B). This exposure would be configured to capture details about the damaged items (e.g., luggage, electronics) belonging to the passengers.
Why other options are incorrect:
* Option E (Liability Bodily Injury):This is for Third Party injuries (e.g., pedestrians or people in other cars), not the First Party driver.
* Option D (Under Insured Motorist):This applies when the Rideshare driver is hit by someone else who doesn't have enough insurance. The prompt focuses on the risksofthe driver working, not the financial failure of others.
NEW QUESTION # 35
At Succeed Insurance, new personal auto claims involving a fatality are assigned to a High Complexity Auto group made up of Adjusters with at least eight years of experience dealing with the issues and emotions commonly found in claims involving fatalities. Fatality claims typically take 18 to 24 days to complete. The assigned Business Analyst (BA) will document the assignment rule for this requirement in User Story Card Assign Claims Exposures and Activities for a Personal Auto Claim - Foundational. The existing tab UI Validation & Business Rules shown below is not a good fit for assignment rules, so a new tab will be added to the Story Card.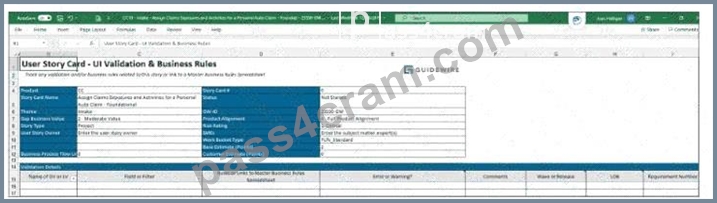
Which two sets of columns should the new tab include to accurately capture the assignment rule requirements? (Choose two.)
Answer: A,B
Explanation:
When documenting Assignment Rules (or any business logic) in a User Story Card or a separate Business Rules spreadsheet, the Business Analyst must capture specific metadata that allows developers to implement the logic correctly in Gosu (Guidewire's programming language).
* Option D (Entity, Line of Business, Rule Conditions, Rule Actions):This is the core logical definition of the rule.
* Entity:Defines what object is being assigned (e.g., Claim, Exposure, Activity).
* Line of Business:Specifies the scope (e.g., Personal Auto).
* Rule Conditions:Captures the "IF" logic (e.g., "IF Loss Cause = Fatality AND LOB = Personal Auto").
* Rule Actions:Captures the "THEN" logic (e.g., "THEN Assign to Group: High Complexity Auto").
* This structure mimics the actual implementation pattern in Guidewire Studio (Rule Sets).
* Option E (Comments, Wave or Release, Requirement Number):These are standard project management and traceability columns required foranyrequirements artifact.
* Requirement Number:Links the specific rule row back to the high-level business requirement.
* Wave or Release:Indicates when this specific rule needs to be deployed.
* Comments:Provides context or clarification for the developer.
Why other options are incorrect:
* Option A:These columns ("Name of DV or LV", "Field or Filter") are specific toUI Validation(the tab currently shown in the image). They describe screen widgets and validation errors, not backend assignment logic.
* Option B:While "Global Assignment Rule" and "Default Group Assignment Rule" are valid Guidewire concepts, listing them ascolumnsis not the standard way to document a list of requirements. Usually, the ruletypewould be a single column, but "Exit Type" is a technical implementation detail (part of the rule set execution) rather than a business requirement column.
* Option C:"Error or Warning?" is specific to Validation Rules (stopping a user from proceeding), not Assignment Rules (routing a work item).
Next Step:Would you like me to generate a sample "Assignment Rule" table structure that shows exactly how this Fatality claim rule would be entered into the columns described in Option D?
NEW QUESTION # 36
An Adjuster at Succeed Insurance is handling a homeowners claim with a dwelling exposure for damage to the insured's home. The Adjuster's Authority Limit Profile has the following limits: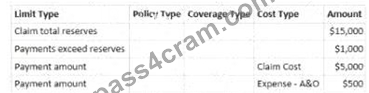
The table below is a view of the property claims organization within Succeed Insurance. The Adjuster is a member of the group Property - Team A.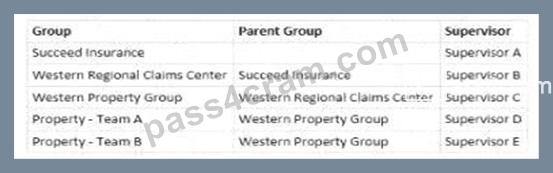
The Adjuster creates a payment in the amount of $6,500 for repairs to the insured's home. How will it be processed assuming that the claim has sufficient reserves for the payment?
Answer: A
Explanation:
This scenario involves checking financial Authority Limits and determining the correct Approval Routing hierarchy in Guidewire ClaimCenter.
* Check Authority Limits:First, compare the transaction amount against the user's specific limits.
* The payment is for "repairs to the insured's home," which is classified asClaim Cost(Indemnity).
* According to the provided Authority Limit Profile, the Adjuster has a "Payment amount" limit of
$5,000for Claim Cost.
* The transaction amount is$6,500.
* Since$6,500 > $5,000, the limit is exceeded, meaning the paymentrequires approval(Ruling out Option B).
* Determine Routing:When a financial transaction requires approval, ClaimCenter routes the approval activity to the supervisor of the group to which the user belongs.
* The Adjuster is a member ofProperty - Team A.
* According to the Organization chart provided, the Supervisor for "Property - Team A" is Supervisor D.
* Therefore, the system will generate an approval activity and assign it specifically to Supervisor D). Supervisor C is the manager of theparentgroup (Western Property Group), so the activity would only go to them if Supervisor Dalsolacked the authority to approve the $6,500, requiring further escalation. However, the initial routing is always to the immediate supervisor.
Why other options are incorrect:
* Option A:Supervisor C is the "Grand-boss" (Supervisor of the parent group), not the immediate supervisor.
* Option B:The amount ($6,500) clearly exceeds the defined limit ($5,000), so automatic processing is impossible.
* Option C:Supervisor A is at the top of the hierarchy (Succeed Insurance), far removed from the initial approval step.
NEW QUESTION # 37
......
The Guidewire ClaimCenter-Business-Analysts pdf questions learning material provided to the customers from Pass4cram is in three different formats. The first format is PDF format which is printable and portable. It means it can be accessed from tablets, laptops, and smartphones to prepare for the ClaimCenter Business Analyst - Mammoth Proctored Exam exam. The Guidewire ClaimCenter-Business-Analysts Pdf Format can be used offline, and candidates can even prepare for it in the classroom or library by printing questions or on their smart devices.
ClaimCenter-Business-Analysts New Test Camp: https://www.pass4cram.com/ClaimCenter-Business-Analysts_free-download.html
BONUS!!! Download part of Pass4cram ClaimCenter-Business-Analysts dumps for free: https://drive.google.com/open?id=1tWcO17Im6IlZY2c2ejRqdG5UwbU3nLKi