You can trust VCE4Dumps AFP-Exam-1 exam real questions and start preparation without wasting further time. We are quite confident that with the VCE4Dumps AFP-Exam-1 real exam questions you will get everything that you need to learn, prepare and pass the challenging CSI AFP-Exam-1 Certification Exam easily.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Tax Planning | 14% | - Tax-Efficient Strategies - Tax Deductions and Credits - Income Tax Fundamentals - Registered Plans |
| Topic 2: Professional Conduct and Regulatory Compliance | 10% | - Compliance Responsibilities - Regulatory Requirements - Ethics and Professional Standards |
| Topic 3: Retirement Planning | 17% | - Retirement Income Strategies - Pension Plans - Registered Retirement Savings Plans - Retirement Needs Analysis |
| Topic 4: Estate Planning | 13% | - Estate Transfer Strategies - Powers of Attorney - Wills - Trust and Beneficiary Planning |
| Topic 5: Risk Management and Insurance | 12% | - Risk Assessment - Disability and Health Insurance - Risk Transfer Strategies - Life Insurance |
| Topic 6: Client Relationship and Practice Management | 6% | - Client Discovery - Communication and Advisory Process - Practice Management |
| Topic 7: Asset and Liability Management | 11% | - Debt Management - Cash Flow Management - Personal Balance Sheet Analysis - Budgeting |
| Topic 8: Investment Planning | 17% | - Portfolio Construction - Asset Allocation - Investment Products - Investment Theory |
If you do not have extraordinary wisdom, do not want to spend too much time on learning, but want to reach the pinnacle of life through AFP-Exam-1 exam, then you must have AFP-Exam-1 question torrent. The goal of AFP-Exam-1 exam torrent is to help users pass the exam with the shortest possible time and effort. With AFP-Exam-1 Exam Torrent, you neither need to keep yourself locked up in the library for a long time nor give up a rare vacation to review. You will never be frustrated by the fact that you can't solve a problem.
NEW QUESTION # 82
Todd, a financial planner, is meeting with Vanessa, a new client, to review her investment goals and objectives. During the meeting, Vanessa states that she believes the markets are very efficient and should reflect all available information in the price of securities. She is looking for an investment option that will reflect a similar level of risk and return characteristics as the Canadian market. What investment option should Todd recommend with Vanessa that would reflect her opinions?
Answer: D
Explanation:
Vanessa's belief points directly to passive market exposure. If she accepts that markets are efficient and wants risk and return characteristics similar to the Canadian market, an exchange-traded fund tracking a broad Canadian equity index is the most consistent recommendation. An ETF can provide diversified Canadian market exposure, transparent holdings, intraday liquidity, and typically lower management cost than many actively managed strategies. A Canadian value mutual fund is an active or style-biased mandate and may depart materially from total market characteristics. A neutral balanced fund includes fixed income and therefore will not mirror the Canadian equity market. A hedge fund may use leverage, short positions, derivatives, or absolute-return strategies, which do not match her stated view. Todd must still confirm KYC information and suitability, but among the options, the Canadian ETF best operationalizes an efficient-market philosophy. Study Guide focus: passive investing, ETFs, diversification, efficient markets, and investment objective alignment. The recommendation should still be framed inside Vanessa's KYC profile rather than presented as a universal market rule.
NEW QUESTION # 83
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.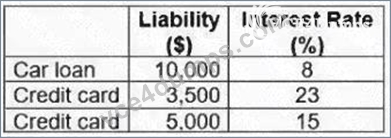
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: D
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 84
Gina plans to take a one-year leave of absence from her employer without pay. Gina has a TFSA invested in equity mutual funds which is currently below book value, an RRSP invested in cash, a Nova Scotia LIRA invested in GICs, and a line of credit. Assuming all have sufficient funds, which plan should Gina access to ensure she meets her goal of budget effectiveness during this time?
Answer: B
Explanation:
Gina needs a practical cash-flow source for a one-year unpaid leave. The LIRA is generally locked in and unavailable for ordinary spending. A line of credit would meet the cash need but would add interest expense and weaken the budget during a period with no salary. Her TFSA is invested in equity mutual funds below book value, so redeeming it would crystallize a market loss and remove the possibility of recovery inside the TFSA. The RRSP is already in cash and Gina's income during the leave will be low, making the withdrawal less tax-costly than it would be in a normal salary year. Although RRSP withdrawals are taxable and reduce retirement assets, in the specific fact pattern it is the best budget-effectiveness choice among the available sources. The planner should still calculate withholding tax and the minimum amount required. Study Guide focus: source-of-funds analysis, registered accounts, LIRA restrictions, tax brackets, and cash-flow planning.
NEW QUESTION # 85
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: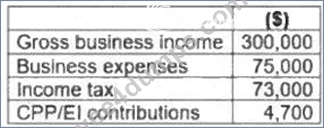
What is Terry's net business income?
Answer: A
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 86
Which assets will flow through an estate?
Answer: A
Explanation:
Estate administration begins with ownership form. A joint tenancy with right of survivorship normally passes directly to the survivor, while an inter vivos trust owns the property outside the deceased's personal estate and a properly funded buy-sell arrangement directs business continuity through contract. Tenancy in common is different: each owner holds a separate, divisible interest. On death, that interest does not disappear and does not vest automatically in the other co-owner. It is property of the deceased and is administered under the will or, if there is no valid will, under intestacy legislation. For AFP purposes, the tested distinction is probate exposure versus survivorship or beneficiary transfer. The asset described in option B is therefore the one that flows through the estate. Study Guide focus: estate ownership, survivorship, trusts, probate property, and estate administration. This distinction is central when determining executor authority, probate value, and whether an asset bypasses estate administration by contract or title.
NEW QUESTION # 87
......
With the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) web-based practice exam, you get the same features as a AFP-Exam-1 desktop practice test software. It includes real CSI AFP-Exam-1 exam questions to help you understand each topic. The web-based AFP-Exam-1 Practice Exam is compatible with every operating system including Mac, Linux, iOS, Windows, and Android. This CSI AFP-Exam-1 practice exam works fine on Chrome, Internet Explorer, Microsoft Edge, Opera, etc.
Test AFP-Exam-1 Guide Online: https://www.vce4dumps.com/AFP-Exam-1-valid-torrent.html