DOWNLOAD the newest ITdumpsfree PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1Le8KqBX__frkw0oO9bIyYnm66_nL78Gw
ITdumpsfree try hard to makes National Payroll Institute Payroll Fundamentals 1Exam exam preparation easy with its several quality features. Our PF1 exam dumps come with 100% refund assurance. We are dedicated to your accomplishment, hence pledges you victory in PF1 Certification exam in a single attempt. If for any reason, a user fails in PF1 exam then he will be refunded the money after the process. Also, we offer one year free updates to our PF1 Exam esteemed users; and these updates will be entitled to your account right from the date of purchase. Also the 24/7 Customer support is given to users, who can email us if they find any haziness in the PF1 exam dumps, our team will merely answer to your all PF1 exam product related queries.
| Section | Objectives |
|---|---|
| Topic 1: Payroll Records and Compliance Reporting | - Government reporting
|
| Topic 2: Payroll Fundamentals and Compliance Framework | - Payroll system overview in Canada
|
| Topic 3: Earnings, Deductions, and Taxation | - Types of earnings
|
ITdumpsfree aims to assist its clients in making them capable of passing the National Payroll Institute PF1 certification exam with flying colors. It fulfills its mission by giving them an entirely free Payroll Fundamentals 1Exam (PF1) demo of the dumps. Thus, this demonstration will enable them to scrutinize the quality of the National Payroll Institute PF1 study material.
NEW QUESTION # 41
Dollar amounts that are paid to an employee to cover expenses that they incurred while performing their job, but are not considered in the calculation of an employee's earnings are:
Answer: B
Explanation:
An expense reimbursement is a repayment to an employee for business costs they already paid personally (for example, meals, mileage, supplies), typically supported by receipts or an expense report. CRA's guidance explains that a reimbursement is a payment made to repay amounts the employee spent while conducting the employer's business, and that a reasonable reimbursement is generally not included in the employee's income.
That's why reimbursements are generally not part of "earnings" for payroll calculations-they are not compensation for work performed; they are repayment of a business expense. This differs from an allowance, which is usually a fixed amount paid without requiring receipts; allowances are often taxable unless a specific CRA exception applies.
So the correct term for "dollar amounts paid to cover job expenses incurred, but not considered earnings" is expense reimbursements (option D). Payroll best practice is to ensure reimbursements are properly documented and reasonable to support non-taxable treatment.
NEW QUESTION # 42
Jasmine works for a Saskatchewan employer and earns $500.00 weekly. Calculate her Employment Insurance (EI) premium.
Answer:
Explanation:
$8.15 (employee EI premium for the week)
Explanation:
For employees whose province of employment is outside Quebec (including Saskatchewan), EI premiums are calculated by multiplying the employee's insurable earnings by the employee EI premium rate for the year, up to the annual maximum insurable earnings. For 2026, the employee EI premium rate outside Quebec is $1.63 per $100 of insurable earnings (which is 1.63%).
Jasmine earns $500.00 weekly and (based on the question) we assume all earnings are insurable and she has not reached the annual maximum. Her EI premium is:
$500.00 × 1.63% = $500.00 × 0.0163 = $8.15.
This amount is deducted from the employee's pay and later remitted to the CRA as part of the employer's regular payroll remittance. The maximum insurable earnings for 2026 is $68,900, but at $500 per week she would only hit the maximum later in the year (if at all), so the weekly premium calculation above applies.
NEW QUESTION # 43
Which pension plan requires the services of an actuary to study and forecast future needs of the plan to ensure the plan remains sufficiently funded to provide employees with their retirement benefits?
Answer: B
NEW QUESTION # 44
The source deductions form completed by all new employees in Quebec is called:
Answer: C
Explanation:
In Quebec, employees must complete a Quebec-specific source deductions form so the employer can calculate Quebec income tax to withhold. Revenu Quebec identifies Form TP-1015.3-V (Source Deductions Return) as the form employees complete and provide to their employer/payer for this purpose. It is part of the onboarding
/payroll setup process in Quebec and is used to determine personal tax credits and any additional withholding instructions for Quebec provincial income tax.
The other options are not the standard Quebec source deductions return for new employees: T1213 is a CRA form used to request a reduction in tax deductions at source (federal), TD1-AB is a provincial TD1 for Alberta (not Quebec), and T2222 is not the Quebec source deductions return. From a payroll communication standpoint, the employer should request both the applicable federal TD1 and the Quebec TP-1015.3-V, then retain them on file to support accurate withholding calculations.
NEW QUESTION # 45
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
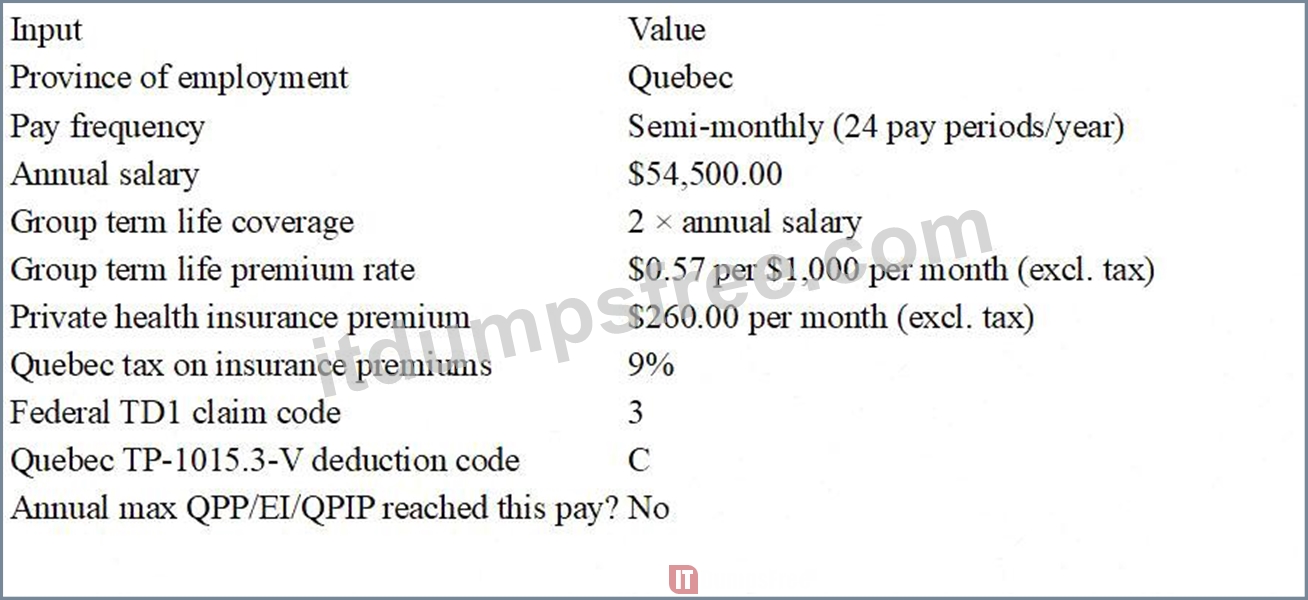
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases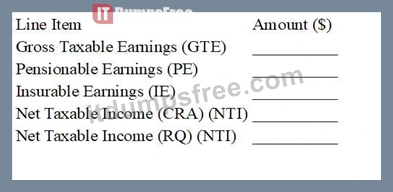
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
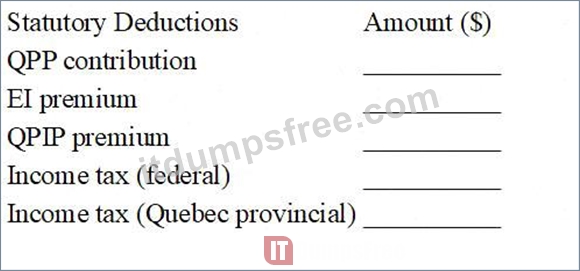
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
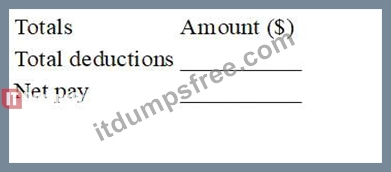
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 46
......
To improve our products’ quality we employ first-tier experts and professional staff and to ensure that all the clients can pass the test we devote a lot of efforts to compile the PF1 learning guide. Even if you unfortunately fail in the test we won’t let you suffer the loss of the money and energy and we will return your money back at the first moment. After you pass the PF1 test you will enjoy the benefits the certificate brings to you such as you will be promoted by your boss in a short time and your wage will surpass your colleagues. In short, buying the PF1 exam guide deserves your money and energy spent on them.
Exam PF1 Topics: https://www.itdumpsfree.com/PF1-exam-passed.html
DOWNLOAD the newest ITdumpsfree PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1Le8KqBX__frkw0oO9bIyYnm66_nL78Gw