Through our investigation and analysis of the real problem over the years, our AFP-Exam-1 prepare questions can accurately predict the annual AFP-Exam-1 exams. And the AFP-Exam-1 quiz guide’s experts still have the ability to master propositional trends. Believe that such a high hit rate can better help users in the review process to build confidence, and finally help users through the qualification examination to obtain a certificate. All in all, we want you to have the courage to challenge yourself, and our AFP-Exam-1 Exam Prep will do the best for the user's expectations.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Tax Planning | 14% | - Tax-Efficient Strategies - Tax Deductions and Credits - Income Tax Fundamentals - Registered Plans |
| Topic 2: Asset and Liability Management | 11% | - Budgeting - Cash Flow Management - Personal Balance Sheet Analysis - Debt Management |
| Topic 3: Investment Planning | 17% | - Investment Theory - Asset Allocation - Portfolio Construction - Investment Products |
| Topic 4: Client Relationship and Practice Management | 6% | - Client Discovery - Practice Management - Communication and Advisory Process |
| Topic 5: Retirement Planning | 17% | - Registered Retirement Savings Plans - Retirement Income Strategies - Pension Plans - Retirement Needs Analysis |
| Topic 6: Estate Planning | 13% | - Trust and Beneficiary Planning - Estate Transfer Strategies - Powers of Attorney - Wills |
| Topic 7: Risk Management and Insurance | 12% | - Risk Assessment - Life Insurance - Risk Transfer Strategies - Disability and Health Insurance |
| Topic 8: Professional Conduct and Regulatory Compliance | 10% | - Regulatory Requirements - Ethics and Professional Standards - Compliance Responsibilities |
>> AFP-Exam-1 Testing Center <<
Improvement in AFP-Exam-1 science and technology creates unassailable power in the future construction and progress of society. AFP-Exam-1 practice test can be your optimum selection and useful tool to deal with the urgent challenge. With over a decade's striving, our AFP-Exam-1 training materials have become the most widely-lauded and much-anticipated products in industry. We have full technical support from our professional elites in planning and designing AFP-Exam-1 Practice Test. Do not hesitate anymore. You will never regret buying AFP-Exam-1 study engine!
NEW QUESTION # 88
Leena and Harry are married and hold RRSPs with a value exceeding $500,000. They are concerned about their final tax liability and want to cover the taxes after they have both died. What would their financial planner recommend them to implement in order for the couple to achieve the objective?
Answer: A
Explanation:
A joint last-to-die permanent life insurance policy is designed for a tax liability that arises after both spouses have died. Leena and Harry are concerned about the final tax exposure on large RRSP balances. If one spouse dies first and the surviving spouse is the beneficiary or successor annuitant, RRSP/RRIF amounts may generally roll to the survivor on a tax-deferred basis. The larger tax problem usually appears on the second death, when no spouse remains for rollover and the registered assets are included in income. Last-to-die coverage pays at that point and can provide estate liquidity for taxes without forcing asset sales. A testamentary trust does not itself fund the tax bill. Updating beneficiaries to each other helps deferral but not the final liability. An inter vivos trust cannot simply receive RRSP assets without tax consequences. Study Guide focus: RRSP/RRIF death taxation, spousal rollover, permanent insurance, estate liquidity, and last-to- die planning.
NEW QUESTION # 89
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.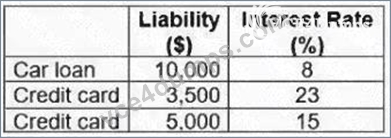
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: D
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 90
Tony, a financial planner, is meeting with his client, Howard, age 42. Howard would like to retire in 15 years.
His retirement goal is to have an annual gross income of $30,000 (in today's dollars). He is currently contributing $2,400 each year to his RRSP which is currently worth $275,000. Assume an average annual inflation rate of 3%, rate of return of 4% for the registered assets and a life expectancy to age 90. What will Tony determine as Howard's current surplus/shortfall at retirement?
Answer: C
Explanation:
Howard has a retirement shortfall of approximately $16,801. The calculation requires inflating the $30,000 annual income goal for 15 years at 3%, projecting the current RRSP and annual $2,400 contributions at 4%, and then comparing the accumulated capital with the amount needed to fund income from retirement to age
90. The figures show that his current capital and planned contributions do not quite support the inflation- adjusted income target over the expected retirement period. Option A and option D incorrectly show a surplus. Option B uses the wrong shortfall amount. This question tests retirement projection mechanics:
nominal retirement income must reflect inflation, and registered asset growth must be projected using the assumed rate of return. The planner should discuss increasing savings, adjusting retirement age, reducing income objectives, or revising investment assumptions within risk tolerance. Study Guide focus: retirement needs analysis, inflation, future value, capital sufficiency, and surplus/shortfall calculation.
NEW QUESTION # 91
Kendrick, age 55, owns a successful small business, ZXC Inc., valued at $800,000. Kendrick has extensive savings outside of the business and would like to pass the company onto his son at some point in the future.
Kendrick expects the business to increase in value $25,000 per year. If Kendrick decides to use an estate freeze to reduce the amount of taxes he will be required to pay, his financial planner should recommend that he implement the estate freeze at which point in relation to gifting the business to his son?
Answer: D
Explanation:
The estate freeze should be implemented immediately if Kendrick expects the business to continue appreciating. The purpose of the freeze is to lock in the current value of the owner's interest, usually by exchanging growth shares for fixed-value preferred shares, while future growth accrues to the successor generation or a trust. Waiting until the gift date, one month before the gift, or death allows additional appreciation to remain taxable to Kendrick. Since the company is already valued at $800,000 and expected to grow by $25,000 per year, every year of delay increases the value exposed to future tax in Kendrick's estate.
A freeze also needs legal and tax design, including valuation, share terms, control, income needs, and succession intentions. Among the options, immediate implementation best achieves the objective of reducing future tax growth in his hands. Study Guide focus: estate freezes, business succession, preferred shares, future growth transfer, and tax minimization.
NEW QUESTION # 92
Jenny and Herman are looking for tax strategies that will help them better manage their marginal annual tax rates. Jenny is currently the primary income earner in the household. She has a large non-registered portfolio that holds only plain vanilla S & P 500 index funds. Jenny and Herman have a 14-year-old daughter, and they would also like to know what income-splitting opportunities exist. They've presented several ideas to their tax planner, Isaac, for review. Which of the following will likely result in tax attribution to Jenny?
Answer: B
Explanation:
Jenny's gift to her minor daughter is the transaction most likely to trigger attribution back to Jenny. When a high-income parent transfers income-producing property to a minor child, income such as interest and dividends generally attributes back to the parent. The rule prevents simple income splitting by gift. A spousal RRSP converted to a RRIF can avoid attribution on required minimum RRIF withdrawals, subject to detailed timing rules. A sale of securities to Herman at fair market value can avoid attribution if proper consideration is paid and the transaction is documented. A prescribed-rate loan to Herman can also avoid attribution if interest is charged at the prescribed rate and paid by the required deadline. The key AFP issue is distinguishing prohibited income splitting from properly structured transfers or loans. The minor-child gift in option A is the clearly attributive arrangement. Study Guide focus: attribution rules, minor children, spousal transfers, prescribed-rate loans, and family tax planning.
NEW QUESTION # 93
......
If you are having the same challenging problem, don't worry; CSI is here to help. Our direct and dependable CSI Treasury with Applied Financial Planning Certification Exam 1 (AFP) Exam Questions in three formats will surely help you pass the CSI Treasury with AFP-Exam-1 certification exam. Because this is a defining moment in your career, do not undervalue the importance of our Treasury with Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam dumps. Profit from the opportunity to get these top-notch exam questions for the AFP-Exam-1 certification test.
AFP-Exam-1 Detailed Answers: https://www.vce4dumps.com/AFP-Exam-1-valid-torrent.html