P.S. Free & New ClaimCenter-Business-Analysts dumps are available on Google Drive shared by Prep4King: https://drive.google.com/open?id=1902CtjPpEWD4yXt0JiOuulqsp0bWjunz
All kinds of exams are changing with dynamic society because the requirements are changing all the time. To keep up with the newest regulations of the ClaimCenter Business Analyst - Mammoth Proctored Exam exam, our experts keep their eyes focusing on it. Expert team not only provides the high quality for the ClaimCenter-Business-Analysts Quiz guide consulting, also help users solve problems at the same time, leak fill a vacancy, and finally to deepen the user's impression, to solve the problem of ClaimCenter Business Analyst - Mammoth Proctored Exam test material and no longer make the same mistake.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
>> Exam ClaimCenter-Business-Analysts Vce <<
Many times getting a right method is important and more efficient than spending too much time and money in vain. Our Prep4King team devote themselves to studying the best methods to help you pass ClaimCenter-Business-Analysts exam certification. From the time when you decide whether to purchase our ClaimCenter-Business-Analysts exam software or not, we have provided you with comprehensive guarantees, including free demo download before buying, payment guarantee in purchase process, one-year free update service after you purchased ClaimCenter-Business-Analysts Exam software, and full refund guarantee of dump cost if you fail ClaimCenter-Business-Analysts exam certification, which are all our promises to ensure customer interests.
NEW QUESTION # 30
During claim intake and adjudication, Adjusters capture contact information for the insured and all claimants.
To improve customer service and reduce the time required to reach these contacts to gather additional claim information, Succeed Insurance will capture the preferred contact method for all person contacts. The new field will be added to the contact details screen of the user interface (UI) as a drop-down list displaying all valid contact methods including email, mail, and phone.
Which version correctly lists the preferred contact methods in the Typelists tab of the Parties Involved User Story Card?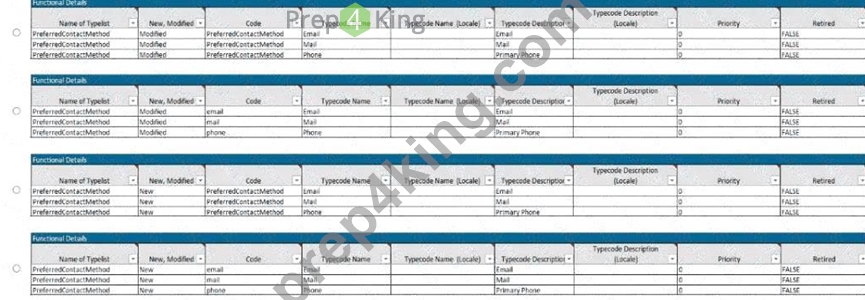
Answer: C
Explanation:
To correctly document a Typelist in a User Story Card, the Business Analyst must understand both the data structure (Codes vs. Names) and the configuration state (New vs. Modified).
* Code Validity:In Guidewire, aTypecode(the value stored in the database) must be a unique identifier for each option in the list.
* Option Bcorrectly lists distinct codes: email, mail, and phone.
* Options A and Care incorrect because they list theTypelist Name(PreferredContactMethod) as the Codefor every single row. You cannot have multiple entries with the same primary key (Code) in one list.
* Configuration State (New vs. Modified):The PreferredContactMethod typelist is a standardBase Productfeature in Guidewire ClaimCenter. It already exists out-of-the-box.
* Option Bcorrectly identifies the Status as"Modified". When you add values to or configure an existing base typelist, you document it as "Modified".
* Option Dis incorrect because it lists the Status as"New". This would imply creating a brand new custom typelist (e.g., MyCustomList_Ext), which is not necessary for standard contact methods.
Therefore,Option Bis the only version that has valid, unique codes and the correct configuration status.
NEW QUESTION # 31
A claim for an auto accident in Tampa, Florida has been reported and recorded in ClaimCenter. The ClaimCenter base product Global Claim Assignment Rule is utilized for automatic assignment to Adjusters regardless of complexity of claims.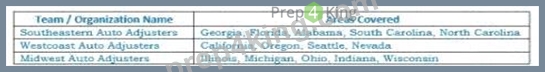
What is the likely path of assignment for this claim?
Answer: C
Explanation:
Claim Assignment in Guidewire ClaimCenter follows a two-step logic: Global Assignment (finding the right Group) and Group Assignment (finding the right User).
* Group Identification (Global Assignment):The first step relies on the geography of the loss.
According to the provided organization table, theSoutheastern Auto Adjustersgroup is responsible for
"Georgia,Florida, Alabama, South Carolina, North Carolina." Since the accident occurred inTampa, Florida, the Global Assignment rule will route the claim to the Southeastern Auto Adjusters group.
* User Assignment (Group Assignment):The prompt specifies the use of "automatic assignment...
regardless of complexity." In ClaimCenter's base configuration, the standard method for distributing claims automatically within a group isRound Robin(or Cyclical) assignment. This method assigns the claim to the next available adjuster in the list, ensuring an even distribution of volume without complex weighting calculations.
Why other options are incorrect:
* Option B (Midwest):Incorrect geography. The Midwest group covers IL, MI, OH, IN, WI, not Florida.
* Option C (Weighted Workload):While "Dynamic Assignment" (workload balancing) is a feature, the standard "automatic assignment" described implies a simple cyclical rotation (Round Robin). Weighted assignment is a more advanced configuration typically used when complexityisa factor (e.g., assigning fewer claims to junior adjusters).
* Option D (Supervisor):Assigning to a Supervisor is a manual fallback or "Assign to Supervisor" rule, usually triggered when no suitable adjuster is available or for complex exceptions. It is not the primary path for standard automatic assignment.
NEW QUESTION # 32
An Adjuster at Succeed Insurance increases the reserve on a claim's exposure from $1,000 to $1,500 to account for inflation in repair costs. A week later, a Supervisor reviews the claim and wants to know specifically who made this change, the exact date and time it was made, and what the previous value was.
The Supervisor needs a chronological audit trail of changes to the claim file without navigating through complex financial ledgers.
Which screen in the ClaimCenter user interface should the Supervisor access to find this information?
Answer: C
Explanation:
In Guidewire ClaimCenter, the History screen serves as the automated audit trail for the claim file. It is designed to capture and display a chronological list of significant events and user actions that have occurred throughout the claim's lifecycle.
* Audit Trail Functionality:The History screen automatically records specific types of events, including:
* Field Changes:When critical fields (like Reserve Amounts) are modified, the system logs the
"Old Value" and the "New Value."
* Assignment Changes:Tracks when the claim was transferred from one user to another.
* Rule Execution:Logs when specific business rules (like "Exception Flagged") are triggered.
* Data Points:For each entry, the History screen displays theUserwho performed the action, the Timestampof the event, and aDescriptionof the change.
Why other options are incorrect:
* Financials > Transactions (A):While this screen shows the financial T-account entries (debits/credits) for the reserve increase, its primary purpose is accounting analysis. It is less efficient for a supervisor looking for a simple "Who/When/What" audit trail compared to the History screen.
* Notes (C):Notes are typically used for qualitative narratives and manual entry. While a system notecan be generated for a reserve change, the History screen is the dedicated, non-editable system of record for tracking field changes.
* Loss Details > Status (D):This screen shows thecurrentstate of the claim (e.g., Open, Closed, Litigation Status) but does not provide a historical log of previous values or the specific user actions that led to the current state.
NEW QUESTION # 33
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.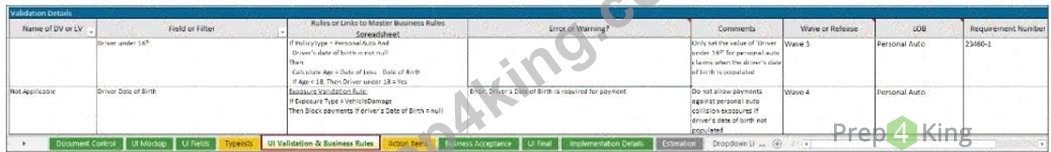
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: B,D
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 34
Drivers for Rideshare companies need insurance that provides protection when they are driving the vehicle for personal reasons. This will be the Succeed Insurance standard Personal Auto Policy. However, they also need insurance to protect them from the increased risks associated with working as a Rideshare Driver. This would include when they are logged in to the Rideshare application waiting for a customer match, on their way to pick up a customer, but not when a customer has entered the vehicle.
When a driver is working as a Rideshare Driver, this new Rideshare coverage will protect them from the following types of risks, and there is a need to be able to collect the appropriate information about the losses:
. Injury to a first-party driver
. Damaged personal property of the third-party passengers
Which two exposures need to be configured? (Choose two.)
Answer: A,E
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
To satisfy the requirements for the new "Rideshare" coverage product, the Business Analyst must map the described risks to the correct Exposure Types in the ClaimCenter data model.
* Risk: Injury to a first-party driver:In insurance terminology, "First Party" refers to the insured (the driver). Coverage for injuries sustained by the driver themselves is typically handled byMedical Payments(MedPay) or Personal Injury Protection (PIP). Among the choices provided,Rideshare Medical Payments (Option C)is the correct exposure type to cover medical costs for the driver regardless of fault. (Option E, Liability Bodily Injury, would cover injuries toothersthat the driver hit).
* Risk: Damaged personal property of third-party passengers:This refers to liability for damage to property belonging to others. While typically "Property Damage Liability," the specific option provided that fits this description isRideshare Personal Property Protection (Option B). This exposure would be configured to capture details about the damaged items (e.g., luggage, electronics) belonging to the passengers.
Why other options are incorrect:
* Option E (Liability Bodily Injury):This is for Third Party injuries (e.g., pedestrians or people in other cars), not the First Party driver.
* Option D (Under Insured Motorist):This applies when the Rideshare driver is hit by someone else who doesn't have enough insurance. The prompt focuses on the risksofthe driver working, not the financial failure of others.
NEW QUESTION # 35
......
Exam ClaimCenter-Business-Analysts is just a piece of cake if you have prepared for the exam with the helpful of Prep4King's exceptional study material. If you are a novice, begin from ClaimCenter-Business-Analysts study guide and revise your learning with the help of testing engine. Exam ClaimCenter-Business-Analysts Brain Dumps is another superb offer of Prep4King that is particularly helpful for those who want to the point and the most relevant content to pass exam. With all these products, your success is assured with 100% money back guarantee.
Official ClaimCenter-Business-Analysts Study Guide: https://www.prep4king.com/ClaimCenter-Business-Analysts-exam-prep-material.html
BTW, DOWNLOAD part of Prep4King ClaimCenter-Business-Analysts dumps from Cloud Storage: https://drive.google.com/open?id=1902CtjPpEWD4yXt0JiOuulqsp0bWjunz