BTW, DOWNLOAD part of Real4test Accounting-for-Decision-Makers dumps from Cloud Storage: https://drive.google.com/open?id=1t2ruZNkBxGmSej2NoL-_Ck2jG11vrg3F
With our WGU Accounting-for-Decision-Makers study matetials, you can make full use of those time originally spent in waiting for the delivery of exam files so that you can get preparations as early as possible. There is why our WGU Accounting-for-Decision-Makers learning prep exam is well received by the general public.
| Section | Weight | Objectives |
|---|---|---|
| Financial Analysis | 45–50% | - Purpose and components of financial statements
|
| Budgeting and Decision Making | 10–15% | - Master budget and components
|
| Cost Systems | 20–25% | - Cost concepts and classification
|
| Controls and Regulations | 10–15% | - Internal control systems and principles
|
| Profit Planning | 10–15% | - Cost-volume-profit (CVP) analysis
|
>> Detailed Accounting-for-Decision-Makers Answers <<
After the user has purchased our Accounting-for-Decision-Makers learning materials, we will discover in the course of use that our product design is extremely scientific and reasonable. Details determine success or failure, so our every detail is strictly controlled. For example, our learning material's Windows Software page is clearly, our Accounting-for-Decision-Makers Learning material interface is simple and beautiful. There are no additional ads to disturb the user to use the WGU Accounting for Decision Makers C213 VAC2 qualification question. Once you have submitted your practice time, Accounting-for-Decision-Makers study tool system will automatically complete your operation.
NEW QUESTION # 53
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.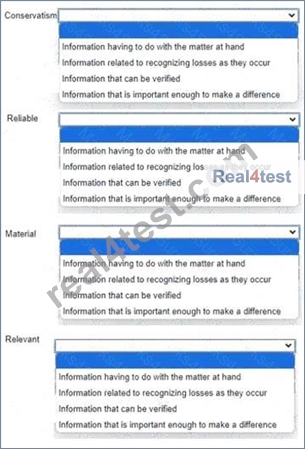
Answer:
Explanation: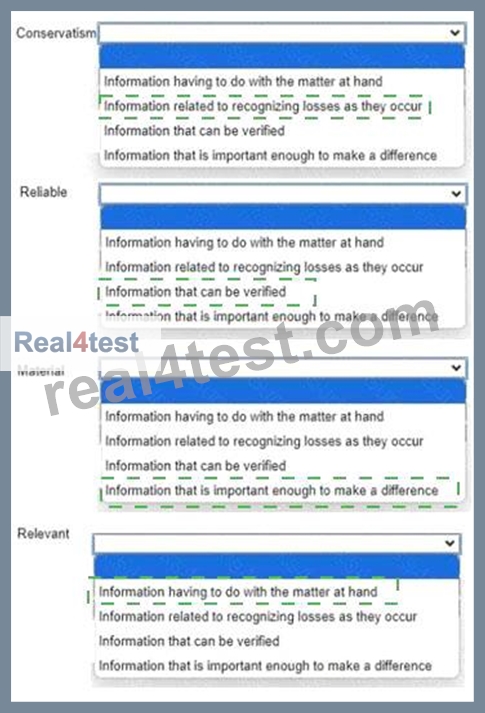
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 54
A company allocates overhead based on the number of shoes produced.
The company estimates the following costs and shoe production for the upcoming year:
Estimated total overhead = $1,250,000
Estimated number of shoes = 4,000,000
Actual overhead = $1,350,000
Actual number of shoes = 4,100,000
What is the predetermined overhead rate?
Answer: A
Explanation:
The correct answer is A. $0.313 . A predetermined overhead rate is calculated at the beginning of the period using estimated overhead costs and the estimated amount of the allocation base. OpenStax states that the rate is found by dividing estimated manufacturing overhead by the estimated activity base.
The formula is:
Predetermined overhead rate = Estimated total overhead / Estimated allocation base Using the numbers in the question:
$1,250,000 / 4,000,000 shoes = $0.3125 per shoe
Rounded to three decimal places, that equals $0.313 per shoe .
The actual overhead and actual number of shoes produced are not used to compute the predetermined rate.
Those figures are used later when applying overhead or analyzing overapplied and underapplied overhead.
That is why choices based on actual data are incorrect.
Option B, $0.329 , comes from dividing actual overhead by actual production, but that is an actual rate, not the predetermined one asked for here. Since predetermined overhead always relies on estimates made in advance, the correct answer is $0.313 , which makes Option A correct.
NEW QUESTION # 55
A company has projected the following sales for the spring quarter of a year:
April = $300,000
May = $325,000
June = $375,000
Cash is used to pay for 65% of all sales. The remainder is on credit.
The pattern for credit receivables collections is as follows:
* Month of sale = 60%
* Month after sale = 30%
* Second month after sale = 10%
What are the projected cash sales for all three months of the spring quarter?
Answer: C
Explanation:
The correct answer is D. $650,000 . The question asks for projected cash sales for all three months of the spring quarter , not total cash collections including receivables from credit sales. Since 65% of all sales are cash sales , simply multiply total spring-quarter sales by 65%.
First, calculate total sales for April through June:
$300,000 + $325,000 + $375,000 = $1,000,000
Now calculate the cash-sales portion:
65% × $1,000,000 = $650,000
Therefore, the projected cash sales for the quarter are $650,000 .
The credit collection percentages are not needed for this specific question because it asks only about cash sales , not total cash receipts. Those credit collection percentages would matter if the question asked for cash collections by month or by quarter from both current and prior credit sales.
Because 65% of the quarter's $1,000,000 total sales are made in cash, the projected cash sales amount is
$650,000 , which makes Option D correct.
NEW QUESTION # 56
What are two examples of product costs?
Choose 2 answers.
Answer: A,D
Explanation:
The correct answers are B. Direct labor and D. Raw materials . Product costs are the costs incurred to manufacture or acquire a product that will be sold. In a manufacturing setting, product costs normally include direct materials (raw materials) , direct labor , and manufacturing overhead . Corporate Finance Institute summarizes product costs as including direct material, direct labor, and manufacturing overhead.
Option A. Selling and administrative expenses is incorrect because those are period costs , not product costs. Option C. Period expenses is also incorrect for the same reason. Period costs are expensed in the period incurred and are not attached to inventory production. Lumen Learning similarly distinguishes product costs from period costs by explaining that product costs include direct materials, direct labor, and overhead, while selling and administrative expenses are period costs.
Because the question asks for two examples of costs directly associated with making a product, the best answers are Direct labor and Raw materials . These are core manufacturing inputs and become part of inventory until the goods are sold.
NEW QUESTION # 57
Which overhead cost is associated with batch-level activities?
Answer: B
Explanation:
The correct answer is B. Machine setups . In activity-based costing , batch-level activities are performed each time a batch of goods is processed, regardless of how many units are in that batch. A classic example is the machine setup required before production of a batch can begin. ABC materials commonly identify setup costs as batch-level because the activity occurs per batch rather than per individual unit.
Option A, property taxes , and Option C, factory insurance , are usually considered facility-level or organization-sustaining overhead because they support the factory as a whole rather than a specific batch.
Option D, product engineering wages , is more closely related to product-level activities , since engineering work often supports a particular product line rather than each batch run. Batch-level costs increase with the number of production batches, not necessarily with the number of units produced. Since machine setups are incurred each time a batch is started, they are the standard example of a batch-level overhead cost. Therefore, Option B is the correct answer.
NEW QUESTION # 58
......
Our Accounting-for-Decision-Makers practice test is designed to accelerate your professional knowledge and improve your ability to solve the difficulty of Accounting-for-Decision-Makers real questions. Well preparation of certification exam is the first step of passing Accounting-for-Decision-Makers Exam Tests and can save you lots time and money. Our latest Accounting-for-Decision-Makers dumps torrent contains the valid questions and answers which updated constantly.
Test Accounting-for-Decision-Makers Quiz: https://www.real4test.com/Accounting-for-Decision-Makers_real-exam.html
BTW, DOWNLOAD part of Real4test Accounting-for-Decision-Makers dumps from Cloud Storage: https://drive.google.com/open?id=1t2ruZNkBxGmSej2NoL-_Ck2jG11vrg3F