DOWNLOAD the newest LatestCram C11 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1Crz1PcAJhuUA1XpSYpocQ8sBkLMLNJpT
The IIC C11 certification is one of the top-rated career advancement certifications in the market. This Principles and Practice of Insurance (C11) certification exam has been inspiring candidates since its beginning. Over this long time period, thousands of C11 Exam candidates have passed their Principles and Practice of Insurance (C11) certification exam and now they are doing jobs in the world's top brands. You can also be a part of this wonderful community.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Property Insurance | 15-20% | - Property Coverage Forms - Valuation and Coinsurance - Policy Conditions and Exclusions |
| Topic 2: Automobile Insurance | 15-20% | - Commercial Automobile Coverage - Personal Automobile Coverage - Mandatory Coverage Requirements |
| Topic 3: Insurance Operations and Contracts | 20-25% | - Insurance Contract Basics - Underwriting Process - Policy Structure and Interpretation - Fundamental Principles of Insurance |
| Topic 4: Risk and Insurance | 15-20% | - Risk Identification and Measurement - Risk Management Process - Nature of Risk - Insurable Risk |
| Topic 5: Insurance Industry Overview | 10-15% | - Claims Handling - Regulation and Legislation - Insurance Market Structure |
| Topic 6: Liability Insurance | 15-20% | - Commercial General Liability (CGL) - Professional Liability - General Liability Concepts |
LatestCram play the key role for assuring your success in Private Cloud Monitoring and Operations with C11 exam. We incline your interest towards professional way of learning; motivate you to execute your learned concepts in practical industry. No more exam phobia exits if you have devotedly prepared through our C11 Exam products, certain boost comes in your confidence level that routes you towards success pathway.
NEW QUESTION # 40
What is needed to change older statutes that tend to be all-inclusive statements of law on a particular subject?
Answer: C
Explanation:
Statutes-especially older, comprehensive ones-can only be amended or repealed by an act of the legislative authority that created them. In Canada, this means a provincial or federal legislature must formally pass a new act or amendment. Legislatures are the bodies responsible for enacting, revising, or modernizing statutory law to reflect new legal, social, or commercial developments.
Option B is incorrect because Canada does not change statutes through public votes (referenda), except in rare constitutional matters. Option C is incorrect and uses U.S. terminology ("congress"), which does not apply to the Canadian system. Even if compared to Parliament, a bill alone does not change a statute until it is passed into law by the legislature. Option D is incorrect because the Supreme Court interprets law, but does not rewrite statutes.
Thus, only an act of legislature can formally alter statutory law, making A the correct answer.
NEW QUESTION # 41
An insurer's agency or production department is the equivalent of which department in other businesses?
Answer: C
Explanation:
The agency or production department within an insurance company is responsible for generating new business, managing distribution channels, working with brokers and agents, and promoting the insurer's products. These functions align directly with sales and marketing departments found in other industries. Their goals include increasing premium volume, maintaining relationships with intermediaries, and ensuring the insurer's products reach the marketplace effectively.
Option B is incorrect because finance and production refer to cost control and manufacturing, neither of which parallels insurance distribution. Option C does not align because administration and HR handle internal operations, not customer acquisition. Option D deals with internal systems and support functions, unrelated to the business-production role of generating and selling insurance.
Therefore, the insurer's agency or production department corresponds to A: Sales and marketing.
NEW QUESTION # 42
What type of company has the authority to bind coverage for a specific line of business as outlined by an insurer?
Answer: C
Explanation:
A cover holder is a business entity authorized by an insurer-most often within the Lloyd's structure-to bind coverage, issue policies, collect premiums, and sometimes handle claims for specific lines of business. This authority is granted through a binding authority agreement, which outlines the scope of operations, underwriting limits, and compliance requirements. Cover holders extend the market reach of insurers while maintaining oversight through strict reporting and audit mechanisms.
A reinsurer assumes risk from insurers but does not issue retail policies or bind coverage for individual clients. A factory mutual is a specialized mutual insurer focusing on highly protected risks, not delegated binding authority. A syndicate mutual is not a recognized category in Canadian P&C operations. Since only a cover holder has formal delegated binding authority from an insurer, the correct answer is B.
NEW QUESTION # 43
Whose signatures wouldusuallyappear on therisk's policy?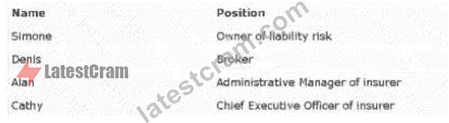
Answer: A
Explanation:
Apolicyis a legal contract issued by theinsurer, not the broker and not the policyholder. Therefore, the individuals who sign the policy are usually the insurer's authorized signing officers.
These are typically:
The CEO or President, and
Another authorized senior officer, such as the Administrative Manager or Underwriting Officer.
In the table:
Cathy(CEO) is an authorized signer.
Alan(Administrative Manager) is also an authorized insurer representative.
The insured (Simone) doesnotsign the actual policy document; their signature is not required for the policy to be valid. The broker (Denis) also doesnotsign policies; he facilitates placement but is not a party to the contract.
Thus, the correct pair isAlan and Cathy.
NEW QUESTION # 44
An insurer writes a $60,000,000 risk for a premium of $30,000. Using pro rata reinsurance, it transfers 25% of the risk to the reinsurer. The risk then suffers a $100,000 loss. How much does the reinsurer contribute to this loss?
Answer: C
Explanation:
In pro rata (proportional) reinsurance, the reinsurer assumes a fixed percentage of both the risk and the premium, and in return pays the same percentage of any losses. Here, the insurer cedes 25% of the risk to the reinsurer. Therefore, the reinsurer must contribute 25% of any loss that occurs on that policy.
The loss amount is $100,000.
Reinsurer's share = 25% × $100,000 = $25,000.
The insurer retains the remaining 75%, or $75,000. Proportional reinsurance helps insurers manage exposure by sharing both costs and losses. Options B, C, and D do not correctly reflect proportional-sharing principles.
The reinsurer does not pay the full loss; it only pays its agreed percentage.
Thus, the correct answer is A: $25,000.
NEW QUESTION # 45
......
If you are on the bus, you can choose the APP version of C11 training engine. On one hand, after being used for the first time in a network environment, you can use it in any environment. The APP version of C11 Study Materials can save you traffic. And on the other hand, the APP version of C11 exam questions can be applied to all kinds of electronic devices, so that you can practice on the IPAD or phone.
C11 Practice Test Pdf: https://www.latestcram.com/C11-exam-cram-questions.html
P.S. Free 2026 IIC C11 dumps are available on Google Drive shared by LatestCram: https://drive.google.com/open?id=1Crz1PcAJhuUA1XpSYpocQ8sBkLMLNJpT