DOWNLOAD the newest PassTorrent Financial-Management PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1aQzzZo_HWr0y0-_vU_RK6jH3Bu819Tvu
Our Financial-Management practice tests have established impressive recognition throughout the industry, diversified modes of learning enables the Financial-Management exam candidates to capture at the real exam scenario. Tremendous quality of our Financial-Management products makes the admirable among the professionals. Our practice tests are on demand, attending the needs of Financial-Management Exams more comprehensively and dynamically as well. Lift up your learning tendency with PassTorrent practice tests training. Conceptual understanding matters the most for your success, technical excellence is certain with PassTorrent training as our experts keep it on high priority.
| Section | Objectives |
|---|---|
| Financial Statement Analysis | - Financial ratios - Balance sheet and income statement interpretation - Cash flow analysis |
| Time Value of Money | - Annuities and perpetuities - Present and future value calculations |
| Risk and Return | - Portfolio risk and diversification - Expected return |
| Capital Budgeting | - Internal rate of return (IRR) - Payback period analysis - Net present value (NPV) |
| Cost of Capital and Valuation | - Bond and stock valuation basics - Weighted average cost of capital (WACC) |
>> Financial-Management Practice Exams Free <<
The WGU Financial-Management Exam Questions give you a complete insight into each chapter and an easy understanding with simple and quick-to-understand language. The WGU Financial-Management exam dumps are the best choice to make. The common problem WGU Financial-Management Exam applicants face is seeking updated and real WGU Financial-Management practice test questions to prepare successfully for the cherished WGU Financial Management VBC1 Financial-Management certification exam.
NEW QUESTION # 24
What is a limitation of historical mean returns when estimating the cost of common equity?
Answer: A
Explanation:
A limitation of using historical mean returns to estimate the cost of common equity is that past performance may not accurately reflect future investor expectations or future market conditions. Historical averages are backward-looking measures. They summarize what returns were earned over a past period, but they do not directly account for changing economic conditions, shifts in interest rates, changes in business risk, new competition, or revised growth expectations. Because the cost of equity is a forward-looking required return, relying only on historical mean returns can produce misleading estimates if the future differs materially from the past. Choice C is correct because it identifies the main weakness: historical returns may ignore current market conditions and future prospects. Choice A is incorrect because historical returns are usually straightforward to calculate. Choice B describes a dividend-based model, not a historical-return approach.
Choice D is also incorrect because the limitation is not that the method only applies to large firms. Financial managers often compare historical-return estimates with other methods, such as CAPM or dividend-growth approaches, to form a more balanced estimate of the cost of equity. Therefore, C is the correct answer.
========
NEW QUESTION # 25
Why might tax expense on the income statement not reflect the actual taxes paid by a firm?
Answer: A
Explanation:
Tax expense reported on the income statement is calculated using accrual accounting, which recognizes revenues and expenses when they are earned or incurred, not necessarily when cash is paid. In contrast, actual taxes paid are based on tax laws and cash payments made to tax authorities. Differences arise due to temporary and permanent timing differences between financial reporting rules and tax regulations. Examples include depreciation methods, revenue recognition timing, loss carryforwards, and deferred tax assets or liabilities. These differences cause tax expense to diverge from cash taxes paid in a given period. Financial managers and analysts must understand this distinction to accurately assess cash flows, particularly when forecasting free cash flow or valuing firms. Option A correctly explains this discrepancy, whereas the other options either deny the existence of differences or incorrectly characterize tax expense accounting.
NEW QUESTION # 26
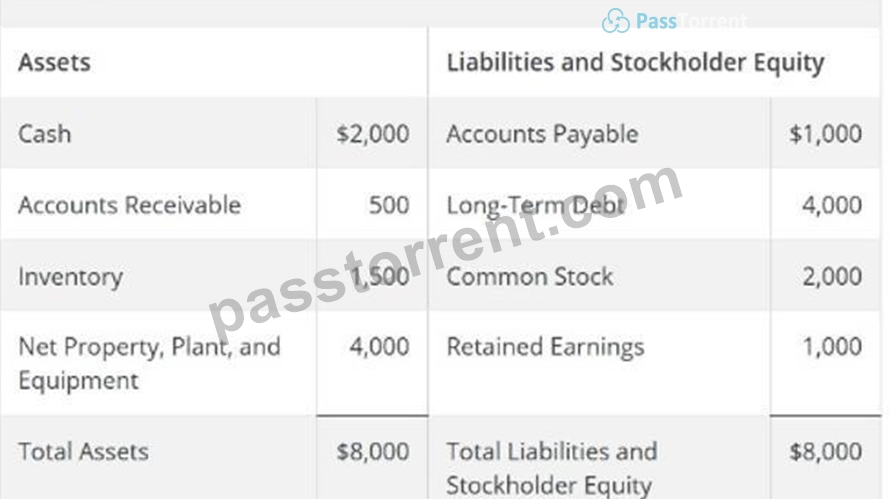
Use Whole Pine Inc.'s financial statements for 20X3 below to answer the following question.
What is Whole Pine Inc.'stotal asset turnoverfor 20X3?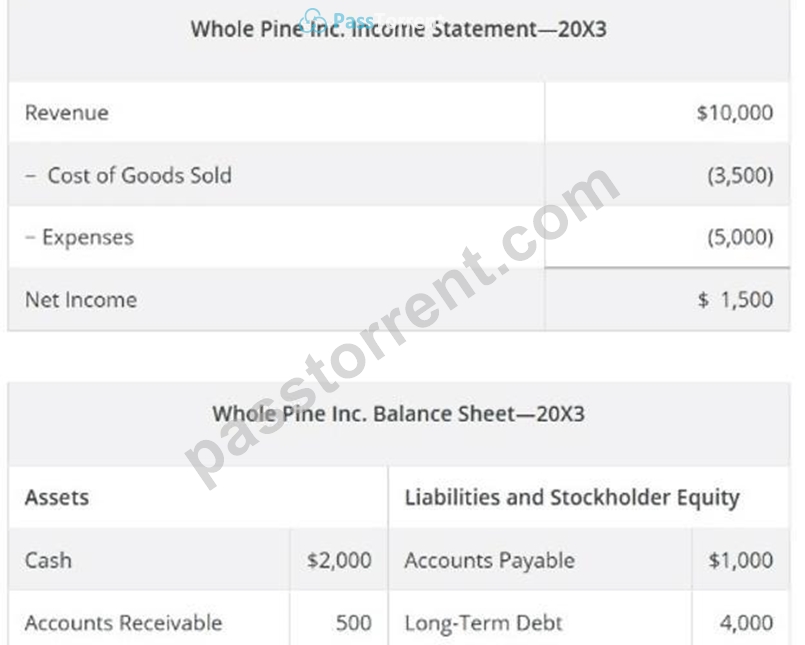
Answer: B
Explanation:
Total asset turnover measures how efficiently a firm uses its assets to generate revenue. It is calculated as Sales ÷ Total Assets. For Whole Pine Inc., sales for 20X3 are $10,000 and total assets are $8,000.
Dividing $10,000 by $8,000 yields a total asset turnover of 1.25. This means the company generates
$1.25 in sales for every $1.00 invested in assets. From a financial management perspective, this ratio is a key indicator of operating efficiency and is commonly compared across firms within the same industry or across time. A higher turnover suggests more efficient use of assets, while a lower turnover may indicate underutilized capacity or inefficient asset deployment. Asset turnover is also a component of the DuPont analysis, linking operational efficiency to return on equity. Option B correctly reflects both the calculation and interpretation consistent with standard financial analysis practice.
NEW QUESTION # 27
A recent news article reported that a popular tech start-up has not yet reached profitability or experienced a period of positive cash flows from operations. Instead, the company has been focused primarily on capturing market share and attracting new customers.
What does the continued negative cash flow from operations (CFO) signal about this firm?
Answer: B
Explanation:
Cash flow from operations reflects the cash generated (or consumed) by a firm's core business activities. When CFO is consistently negative, it indicates that operating expenses and working capital needs exceed cash inflows from sales. For start-ups, this is common during early growth phases, as firms spend heavily on marketing, technology, and customer acquisition to build scale and future revenue potential. However, from a financial management perspective, negative CFO also signals cash burn. Unless offset by financing inflows (equity or debt) or expected future positive cash flows, continued operating losses can threaten liquidity and solvency. Analysts closely monitor burn rate, funding runway, and the firm's ability to transition to sustainable operations. Option C accurately captures this risk-focused interpretation, whereas the other options either mischaracterize negative CFO or contradict its fundamental meaning.
NEW QUESTION # 28
Which type of company would likely have a high credit rating for its bonds?
Answer: A
Explanation:
Bond credit ratings assess the likelihood that a borrower will meet its interest and principal obligations.
Rating agencies evaluate factors such as earnings stability, cash flow coverage, leverage, liquidity, and overall business risk. Companies with strong, consistent earnings and low leverage are viewed as less risky because they have greater capacity to service debt even during economic downturns. High liquidity further reduces default risk by ensuring near-term obligations can be met. Option C best matches these criteria. Firms with a history of default, excessive leverage, weak liquidity, or uncertain business models face higher perceived risk and therefore receive lower credit ratings. High credit ratings allow firms to borrow at lower interest rates, reducing financing costs and improving financial flexibility-key goals in long-term financial management.
NEW QUESTION # 29
......
If you still have a trace of enterprise, you really want to start working hard! Financial-Management exam questions are the most effective helpers on your path. By using Financial-Management study engine, your abilities will improve and your mindset will change. Who does not want to be a positive person? This is all supported by strength! In any case, a lot of people have improved their strength through Financial-Management Exam simulating. They now have the opportunity they want. Whether to join the camp of the successful ones, purchase Financial-Management study engine, you decide for yourself!
Financial-Management Flexible Learning Mode: https://www.passtorrent.com/Financial-Management-latest-torrent.html
What's more, part of that PassTorrent Financial-Management dumps now are free: https://drive.google.com/open?id=1aQzzZo_HWr0y0-_vU_RK6jH3Bu819Tvu