P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by Prep4sureExam: https://drive.google.com/open?id=1pA4EPOREe2h_yTqfpQY3BQmi_wB6uYRZ
No matter where you are or what you are, PF1 practice questions promises to never use your information for commercial purposes. If you attach great importance to the protection of personal information and want to choose a very high security product, PF1 Real Exam is definitely your first choice. And we always have a very high hit rate on the PF1 study guide by our customers for our high pass rate is high as 98% to 100%.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Termination and Special Payments | 30% | - Termination payments
|
| Topic 2: Individual Pay Calculations | 40% | - Regular earnings
|
| Topic 3: Communication and Compliance | 10% | - Accuracy and documentation
|
| Topic 4: Record of Employment (ROE) | 20% | - Submission and deadlines
|
As we all know, HR form many companies hold the view that candidates who own a PF1 professional certification are preferred, because they are more likely to solve potential problems during work. And the PF1 certification vividly demonstrates the fact that they are better learners. Concentrated all our energies on the study PF1 learning guide we never change the goal of helping candidates pass the exam. Our PF1 test questions’ quality is guaranteed by our experts’ hard work. So what are you waiting for? Just choose our PF1 exam materials, and you won’t be regret.
NEW QUESTION # 47
An employee who lives in Ontario and reports to work at a permanent establishment of the employer in Quebec will have income tax deducted based on which province?
Answer: D
Explanation:
For payroll deductions, the key concept is the employee's province of employment (POE)-not where they live. The CRA states that the POE is determined primarily by the employer's establishment where the employee "reports for work." If an employee reports for work at an employer's establishment located in Quebec, then the POE is Quebec, even if the employee's province of residence is Ontario.
This matters because Quebec has distinct payroll requirements. The CRA notes that when the POE is Quebec, employers must apply Quebec-based payroll rules, including deducting Quebec Pension Plan (QPP) contributions instead of CPP, and deducting Quebec parental insurance plan (QPIP) premiums, along with Quebec provincial income tax withholding.
In practice, payroll must set up the employee using Quebec as the POE and ensure stakeholders (HR, finance, the employee) understand why deductions may differ from Ontario residents working in Ontario. Any over
/under-withholding due to POE vs. residence is typically reconciled when the employee files their personal tax return.
NEW QUESTION # 48
In Block 6 of the Record of Employment, what pay period type is entered for employees who are paid salary plus regularly paid commission?
Answer: A
Explanation:
In Block 6 (Pay period type), Service Canada instructs employers to enter the employee's actual pay period type-one of the standard types such as weekly, biweekly, semi-monthly, monthly, or 13 pay periods a year.
Service Canada identifies a special rule only for employees "paid solely on commission or on salary plus irregularly paid commission": in those cases, the employer must use a weekly pay period and average earnings using the weekly averaging formula.
Because this question specifies salary plus regularly paid commission (not irregularly paid commission), the
"special situation" rule does not apply. Therefore, you enter the pay period type that matches the employer's normal payroll cycle for that employee (for example, weekly, biweekly, semi-monthly, monthly, etc.).
NEW QUESTION # 49
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.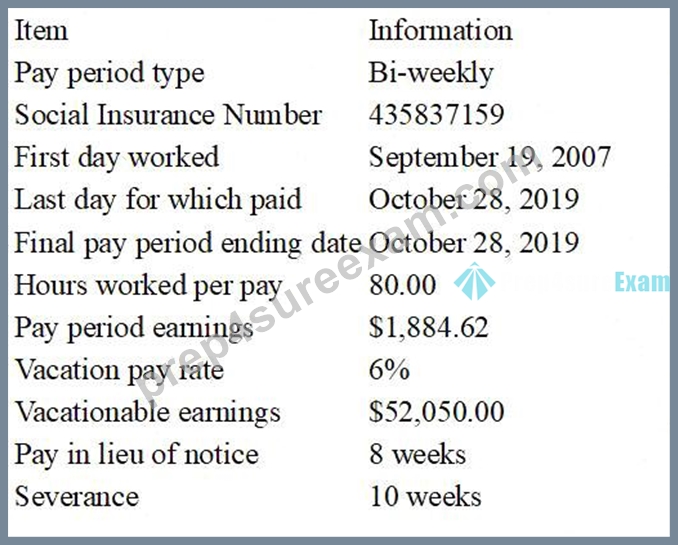
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)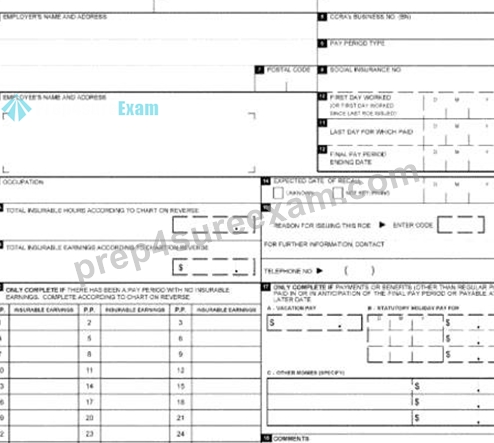
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 50
Elodie is paid her commissions together with her bi-weekly salary of $1,000.00. This pay period her commissions are $4,300.00. Calculate her Quebec Pension Plan (QPP) contribution for this pay period.
Answer:
Explanation:
$325.42
Explanation:
Because Elodie is subject to QPP, her pensionable earnings for the pay period include both salary and commissions (both are pensionable employment earnings, assuming no exemptions apply). First, determine total pensionable earnings for the bi-weekly pay:
$1,000.00 + $4,300.00 = $5,300.00.
For 2026, Revenu Quebec shows the QPP basic exemption is $3,500 annually and the (employee) QPP contribution rate on earnings up to the maximum pensionable earnings is 6.30%.
Payroll applies the exemption per pay period. For bi-weekly pay (26 pay periods):
$3,500 ÷ 26 = $134.62 (rounded to cents).
Pensionable earnings subject to QPP this pay:
$5,300.00 # $134.62 = $5,165.38.
QPP contribution:
$5,165.38 × 6.30% = $5,165.38 × 0.063 = $325.41894, which rounds to $325.42.
NEW QUESTION # 51
Which of the following situations would not require an employer to issue a Record of Employment?
Answer: D
Explanation:
An ROE is required when an employee experiences an interruption of earnings, such as 7 consecutive calendar days with no work and no insurable earnings (the "7-day rule"), or when earnings fall below 60% of regular weekly earnings for specific reasons (the "60% rule"). That means a 6-week unpaid leave (A) typically triggers an interruption of earnings, and a drop to 40% of normal earnings (B) meets the "below
60%" threshold (when due to the listed leave reasons). A layoff with no recall (D) also triggers an interruption of earnings under the 7-day rule.
However, Service Canada lists a special situation for a change in ownership: the former employer does not have to issue ROEs if (1) there is no actual break in the employee receiving earnings, and (2) payroll records are available to the new owner and the new owner agrees to issue a single ROE covering both periods if needed. That is exactly option C, so no ROE is required in that scenario.
NEW QUESTION # 52
......
Our Prep4sureExam PF1 certification exam information is suitable for all IT certification PF1 exam. Its usability is fit for various fields of IT. Prep4sureExam's PF1 exam certification training materials is worked out by senior IT specialist team through their own exploration and continuous practice. Its authority is undoubtdul. If there is any quality problem of PF1 Exam Dumps and answers you buy or you fail PF1 certification exam, we will give full refund unconditionally
PF1 Pdf Exam Dump: https://www.prep4sureexam.com/PF1-dumps-torrent.html
P.S. Free & New PF1 dumps are available on Google Drive shared by Prep4sureExam: https://drive.google.com/open?id=1pA4EPOREe2h_yTqfpQY3BQmi_wB6uYRZ