First-grade Practice NISM-Series-VII Exam Fee–Pass NISM-Series-VII First Attempt

P.S. Free 2026 NISM NISM-Series-VII dumps are available on Google Drive shared by DumpsFree: https://drive.google.com/open?id=1ehAjwOJJO-m2q0xB-jZPiw-JFscIEP_T
Students are worried about whether the NISM-Series-VII practice materials they have purchased can help them pass the exam and obtain a certificate. They often encounter situations in which the materials do not match the contents of the exam that make them waste a lot of time and effort. But with NISM-Series-VII exam dump, you do not need to worry about similar problems. Because our study material is prepared strictly according to the exam outline by industry experts, whose purpose is to help students pass the exam smoothly. As the authoritative provider of NISM-Series-VII Test Guide, we always pursue high passing rates compared with our peers to gain more attention from potential customers. In order to gain the trust of new customers, NISM-Series-VII practice materials provide 100% pass rate guarantee for all purchasers. We have full confidence that you can successfully pass the exam as long as you practice according to the content provided by NISM-Series-VII exam dump. Of course, if you fail to pass the exam, we will give you a 100% full refund.
| Section | Objectives |
|---|
| Topic 1: Securities Market Operations | - Trading process
- 1. Trade confirmation and reporting
- 2. Order execution and trade lifecycle
- Market participants and structure
- 1. Order types and trading mechanism basics
- 2. Roles of brokers, exchanges, and investors
|
| Topic 2: Clearing and Settlement | - Settlement systems
- 1. T+1/T+2 settlement cycles
- 2. Margining and risk adjustments
- Clearing mechanisms
- 1. Clearing corporations and counterparties
- 2. Netting and settlement obligations
|
| Topic 3: Depository Operations | - Demat account framework
- 1. Account opening and maintenance
- 2. NSDL and CDSL roles
- Corporate actions
- 1. Record dates and entitlement processing
- 2. Dividends, bonuses, splits
|
| Topic 4: Risk Management in Securities Markets | - Risk mitigation systems
- 1. Surveillance and compliance mechanisms
- 2. Margins and collateral systems
- Market and operational risk
- 1. Operational risk controls
- 2. Types of financial risks
|
>> Practice NISM-Series-VII Exam Fee <<
Valid NISM-Series-VII Learning Materials | NISM-Series-VII Exam Simulator Fee
DumpsFree's study material is available in three different formats. The reason we have introduced three formats of the NISM Series VII - Securities Operations and Risk Management Certification (NISM-Series-VII) practice material is to meet the learning needs of every student. Some candidates prefer NISM-Series-VII practice exams and some want real NISM Series VII - Securities Operations and Risk Management Certification (NISM-Series-VII) questions due to a shortage of time. At DumpsFree, we meet the needs of both types of aspirants. We have NISM-Series-VII PDF format, a web-based practice exam, and NISM Series VII - Securities Operations and Risk Management Certification (NISM-Series-VII) desktop practice test software.
NISM Series VII - Securities Operations and Risk Management Certification Sample Questions (Q77-Q82):
NEW QUESTION # 77
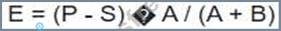
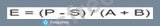
To calculate the Adjustment Factor for a **Rights Issue** in the Equity F&O segment, the 'Benefits per share (E)' must first be determined. Which formula correctly represents the calculation of 'E'?
Answer: D
Explanation:
In the context of Rights Issue adjustment, Benefits per share (E) is calculated using the formula: E = (P - S) * A1 (A + B), where P is the underlying close price on the last cum date, S is the issue price of the rights, A is the Rights Entitlement, and B is the Number of Existing shares.
NEW QUESTION # 78
Which of the following scenarios is explicitly EXEMPT from the mandatory periodic settlement of running accounts for funds?
- A. Clients trading in the derivatives segment only.
- B. Institutional clients settling trades through custodians.
- C. Clients who have a credit balance of less than Rs. 1 lakh.
- D. High Net Worth Individuals (HNls) who have provided a written waiver.
- E. Clients who have logged into their trading account at least once in the last 30 days.
Answer: B
Explanation:
Periodic settlement of running accounts may not be necessary in specific cases, including: 'In case of institutional clients settling trades through custodians'. Other exceptions include clients availing margin trading facility (to the extent of funds relating to MTF) and funds received as BG/FDR collaterals.
NEW QUESTION # 79
When a corporate action adjustment (such as a bonus ratio of 3:7) results in fractions, a specific methodology is adopted to minimize fraction settlements. How are the Strike Price and Market Lot rounded off in this process?
- A. Strike Price: Rounded up to nearest integer; Market Lot: Rounded down to nearest 100
- B. Strike Price: Nearest tick size; Market Lot: Nearest integer
- C. Strike Price: Rounded down to nearest tick; Market Lot: Rounded up to nearest integer
- D. Strike Price: Nearest integer; Market Lot: Nearest tick size
- E. Strike Price: Exact value up to 2 decimal places; Market Lot: Exact value
Answer: B
Explanation:
With a view to minimizing fraction settlements, the methodology adopted includes carrying out rounding off for the Strike Price to the nearest tick size and Market Lot to the nearest integer.
NEW QUESTION # 80
A Trading Member executes trades in both T+1 and T+0 settlement cycles for the same security on the same day. Which of the following statements correctly describes the netting of obligations between these two segments?
- A. Obligations are netted at the client level but not at the member level.
- B. Funds are netted across segments, but securities are settled separately.
- C. Sell obligations in T+0 are netted against Buy obligations in T+1 to reduce margin requirements.
- D. There shall be no netting in pay-in and pay-out obligations between T+1 and T+0 settlement cycle.
- E. Netting is permitted only if the member opts for the 'Unified Settlement' facility.
Answer: D
Explanation:
The operational details for T+0 settlement explicitly state: 'There shall be no netting in pay-in and pay-out obligations between T+1 and T+0 settlement cycle.'
NEW QUESTION # 81
Identify the correct combination of the minimum Net Worth requirement for a Portfolio Manager and the minimum investment amount they must accept from a client (excluding accredited investors/co-investment managers) as per current regulations.
- A. Net Worth: Rs. 3 Crore; Minimum Investment: Rs. 50 Lakh
- B. Net Worth: Rs. 5 Crore; Minimum Investment: Rs. 25 Lakh
- C. Net Worth: Rs. 2 Crore; Minimum Investment: Rs. 25 Lakh
- D. Net Worth: Rs. 5 Crore; Minimum Investment: Rs. 50 Lakh
- E. Net Worth: Rs. 10 Crore; Minimum Investment: Rs. 1 Crore
Answer: D
Explanation:
The applicant must fulfill the net worth requirement of not less than Rs. 5 Crores. The portfolio manager shall not accept from the clients, funds or securities worth less than Rs. 50 lakh.
NEW QUESTION # 82
......
Please don’t worry about the purchase process because it’s really simple for you. The first step is to select the NISM-Series-VII test guide, choose your favorite version, the contents of different versionof our NISM-Series-VII exam questions are the same, but different in their ways of using. We have three different versions for you to choose: PDF, Soft and APP versions. The second step: fill in with your email and make sure it is correct, because we send our NISM-Series-VII learn tool to you through the email. Later, if there is an update, our system will automatically send you the latest NISM-Series-VII version.
Valid NISM-Series-VII Learning Materials: https://www.dumpsfree.com/NISM-Series-VII-valid-exam.html
- Best NISM NISM-Series-VII Dumps [2026] With Real Exam Questions 😺 Go to website 【 www.testkingpass.com 】 open and search for ▛ NISM-Series-VII ▟ to download for free 😒NISM-Series-VII Real Questions
- 100% Pass 2026 High Pass-Rate NISM-Series-VII: Practice NISM Series VII - Securities Operations and Risk Management Certification Exam Fee 🔓 Search for ⮆ NISM-Series-VII ⮄ and download exam materials for free through ➤ www.pdfvce.com ⮘ 🛤NISM-Series-VII Valid Practice Materials
- New NISM-Series-VII Test Topics 🟦 NISM-Series-VII Real Questions 💏 NISM-Series-VII Brain Exam 😹 Search on “ www.dumpsquestion.com ” for ➡ NISM-Series-VII ️⬅️ to obtain exam materials for free download 🏎NISM-Series-VII Real Questions
- New NISM-Series-VII Dumps 🦘 NISM-Series-VII Valid Practice Materials 👲 Latest NISM-Series-VII Test Online ⏬ The page for free download of “ NISM-Series-VII ” on ▷ www.pdfvce.com ◁ will open immediately 🚧NISM-Series-VII Reliable Exam Vce
- 100% Pass 2026 High Pass-Rate NISM-Series-VII: Practice NISM Series VII - Securities Operations and Risk Management Certification Exam Fee ☎ { www.validtorrent.com } is best website to obtain 「 NISM-Series-VII 」 for free download 💧Latest NISM-Series-VII Test Online
- 100% Pass 2026 High Pass-Rate NISM-Series-VII: Practice NISM Series VII - Securities Operations and Risk Management Certification Exam Fee 📹 Open ➡ www.pdfvce.com ️⬅️ and search for ➤ NISM-Series-VII ⮘ to download exam materials for free 🐞NISM-Series-VII Real Questions
- Training NISM-Series-VII For Exam 😻 Training NISM-Series-VII For Exam 😤 Training NISM-Series-VII For Exam 🍸 Open ➽ www.examcollectionpass.com 🢪 and search for “ NISM-Series-VII ” to download exam materials for free 🔻NISM-Series-VII Valid Test Sims
- Training NISM-Series-VII For Exam 💰 New NISM-Series-VII Dumps 🐘 NISM-Series-VII Latest Real Test 🔼 Search for “ NISM-Series-VII ” on ▷ www.pdfvce.com ◁ immediately to obtain a free download 🕒NISM-Series-VII Real Questions
- High Pass-Rate Practice NISM-Series-VII Exam Fee Help You to Get Acquainted with Real NISM-Series-VII Exam Simulation 🥥 Immediately open ⇛ www.practicevce.com ⇚ and search for 【 NISM-Series-VII 】 to obtain a free download 📉Review NISM-Series-VII Guide
- NISM-Series-VII Sample Test Online 🔴 Valid NISM-Series-VII Exam Sample 🅿 NISM-Series-VII Reliable Exam Vce 🕯 Enter ➽ www.pdfvce.com 🢪 and search for 【 NISM-Series-VII 】 to download for free 🔇NISM-Series-VII Reliable Exam Vce
- 100% Pass Quiz 2026 NISM-Series-VII: NISM Series VII - Securities Operations and Risk Management Certification – Reliable Practice Exam Fee 💻 Open website 《 www.pdfdumps.com 》 and search for ▶ NISM-Series-VII ◀ for free download 💆NISM-Series-VII Valid Test Sims
- p.me-page.com, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, Disposable vapes
P.S. Free 2026 NISM NISM-Series-VII dumps are available on Google Drive shared by DumpsFree: https://drive.google.com/open?id=1ehAjwOJJO-m2q0xB-jZPiw-JFscIEP_T