P.S. Free 2026 CISI IFC dumps are available on Google Drive shared by Prep4away: https://drive.google.com/open?id=1CPUyf1QHh5gO9NMxyqfWpNVZMSuZApIy
Obtaining this IFC certificate is not an easy task, especially for those who are busy every day. However, if you use our IFC exam torrent, we will provide you with a comprehensive service to overcome your difficulties and effectively improve your ability. If you can take the time to learn about our IFC Quiz prep, I believe you will be interested in our IFC exam questions. Our IFC learning materials are practically tested, choosing our IFC exam guide, you will get unexpected surprise.
| Certification Vendor: | CISI (Chartered Institute for Securities & Investment) |
|---|---|
| Exam Name: | Investment Funds in Canada (IFC) Exam |
| Exam Number: | IFC |
| Real Exam Qty: | 100 |
| Exam Format: | Proctored (online or test centre), Multiple Choice |
| Passing Score: | 60% |
| Related Certifications: | Conduct and Practices Handbook (CPH) Canadian Securities Course (CSC) |
| Exam Duration: | 180 minutes |
| Certificate Validity Period: | 1 year enrolment period (certification validity not explicitly fixed; varies by regulator/employer context) |
| Available Languages: | English, French |
| Recommended Training: | CSI official IFC Study Materials CSI learning platform (study tools & practice) |
| Exam Registration: | CSI IFC official course page CSI IFC exam information |
| Sample Questions: | CISI IFC Sample Questions |
| Exam Way: | Proctored exam (online remote or in-person test centre) |
| Pre Condition: | No formal prerequisite exams required; typically taken as an entry-level mutual funds licensing qualification in Canada. |
| Official Syllabus URL: | https://www.csi.ca/en/learning/courses/ifc/exam-credits |
Our company employs experts in many fields to write IFC study guide, so you can rest assured of the quality of our IFC learning materials. What’s more, preparing for the exam under the guidance of our IFC Exam Questions, you will give you more opportunities to be promoted and raise your salary in the near future. So when you are ready to take the exam, you can rely on our IFClearning materials!
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
NEW QUESTION # 331
Darryl has a diversified investment portfolio of mutual funds in a non-registered account with Investwell Mutual Funds, a mutual fund dealer. Darryl's diversified portfolio is composed of 3 mutual funds. Each mutual fund is currently worth about $100,000. The ABC Canadian Equity Fund has a total return of 6%, the DEF Bond Fund has a total return of 8% and GHI Global Equity Fund has a total return of 10%. Darryl wants to make an in-kind contribution to his registered retirement savings plan (RRSP) account. He has unused RRSP contribution room of $60,000.
From a tax-efficient viewpoint, which funds contribute in-kind to his RRSP account?
Answer: A
Explanation:
Moving the DEF Bond Fund to the RRSP would be more tax-efficient than moving any of the other funds.
This is because bond funds generate interest income, which is fully taxable at the investor's marginal tax rate in a non-registered account. By moving the bond fund to an RRSP, Darryl can defer paying taxes on the interest income until he withdraws it from the RRSP. Moving the GHI Global Equity Fund to the RRSP (B) would not be tax-efficient, as global equity funds generate foreign income and dividends, which are subject to foreign withholding taxes in an RRSP. Moving $20,000 from each of the three funds to the RRSP © would not be tax-efficient, as it would trigger capital gains taxes on all three funds in proportion to their returns.
Moving the ABC Canadian Equity Fund to the RRSP (D) would not be tax-efficient, as Canadian equity funds generate Canadian dividends, which are eligible for a dividend tax credit in a non-registered account. By moving the Canadian equity fund to an RRSP, Darryl would lose this tax advantage and pay taxes on the dividends at his marginal tax rate when he withdraws them from the RRSP.
NEW QUESTION # 332
Recently interest rates have gone up. Your customer, Mr. Corelli, has asked you how this will affect the value of his mortgage fund. What is the best response to give to Mr. Corelli?
Answer: D
Explanation:
Comprehensive and Detailed Explanation From Exact Extract:
Fixed-income securities, including mortgage funds, decrease in value when interest rates rise because existing mortgages with lower rates become less attractive compared to new, higher-yielding mortgages. The feedback from the document states:
"Fixed-income securities move in the opposite direction to market interest rates... Let's assume you are the fund manager for a mortgage mutual fund, which has mortgages paying 5%. If mortgage rates suddenly increase to 6%, only the interest rates on newly negotiated mortgages would increase... The investor would not pay you par for a 5% rate. If you wished to sell the mortgages, then you would have to lower your price until the price paid-given the 5% fixed payments to be made-results in a return to the buyer of 6%, the
'going rate' on mortgages. In other words, the market value of your par value mortgages must fall." Reference:Chapter 11 - Conservative Mutual Fund ProductsLearning Domain:Analysis of Mutual Funds
NEW QUESTION # 333
What criteria is used to compare equity mutual funds and global bond funds to determine suitability?
Answer: D
Explanation:
The appropriate criterion is the investment objective . Equity funds and global bond funds belong to fundamentally different investment categories and have different risk-return characteristics, so their historical performance should not be compared directly as though they were peers. IFC emphasizes that suitability requires matching an investment recommendation to the client ' s unique circumstances and investment objectives. For performance evaluation, a peer group should consist of funds with similar investment mandates; IFC 8-0 expressly identifies peer-group comparison as comparing funds with similar mandates.
Consequently, when determining whether an equity fund or global bond fund is suitable for a particular investor, the critical comparison is whether the fund ' s investment objective corresponds to the client ' s objective, rather than simply comparing manager performance or capital appreciation potential.
NEW QUESTION # 334
What statement CORRECTLY describes a key difference between bonds and debentures?
Answer: A
Explanation:
Bonds and debentures are both types of debt instruments that can be issued by corporations or governments to raise capital. However, they differ in the way they are secured. Bonds are backed by the specific assets of the issuer, such as property, equipment, or inventory. This means that if the issuer defaults on the bond payments, the bondholders have a claim on those assets and can sell them to recover their money. Debentures, on the other hand, are not secured by any real assets or collateral. They are only backed by the general creditworthiness and reputation of the issuer. This means that if the issuer defaults on the debenture payments, the debenture holders have no recourse to any specific assets and have to rely on the issuer's ability to pay from its future earnings or liquidation proceeds.
Canadian Investment Funds Course, Unit 5, Section 5.1
NEW QUESTION # 335
The following table shows Sabrina's earned income for the past few years: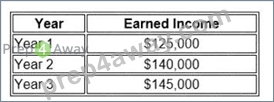
Sabrina has always maximized her RRSP contributions, so she has no carry-forward room available. If the maximum contribution limit for Year 3 is $24,270, what is her RRSP contribution room for Year 3?
Answer: A
Explanation:
Sabrina's RRSP contribution room for Year 3 is $24,270. This is because the maximum contribution limit for Year 3 is $24,270 and Sabrina has always maximized her RRSP contributions, so she has no carry-forward room available.
Canadian Investment Funds Course, Chapter 5: Registered Plans
NEW QUESTION # 336
......
New IFC Exam Camp: https://www.prep4away.com/CISI-certification/braindumps.IFC.ete.file.html
2026 Latest Prep4away IFC PDF Dumps and IFC Exam Engine Free Share: https://drive.google.com/open?id=1CPUyf1QHh5gO9NMxyqfWpNVZMSuZApIy